One of the widest financial choices that an Indian family makes is when they ship a child overseas to pursue higher studies. The recent upsurge in tuition, the depreciation of the rupee and the disastrous loan documents are piling the overseas education planning for parents. This guide effectively simplifies the university selection, real costs, scholarships, and education loans. We have taken thousands of students through the education loan process over the years, and this article shares with you what this experience has taught us. Throughout the process, you will be armed with the knowledge of how to plan, budget and finance the international degree of your child.
The reason why Overseas Education Planning for Parents is important in 2026.
Prudent overseas parental education is no longer a choice. The appreciation of the US dollar and increasing global tuition have pegged the currency between about 70 and almost 85 against US currency in a span of a few years, which is an augmentation of over 20% to the actual expenses of Indian families.
Early planning helps parents avoid panic when time runs out. They compare loans, apply for scholarships and construct a realistic budget far before the admission deadline. This is the core of viable overseas education planning for parents.
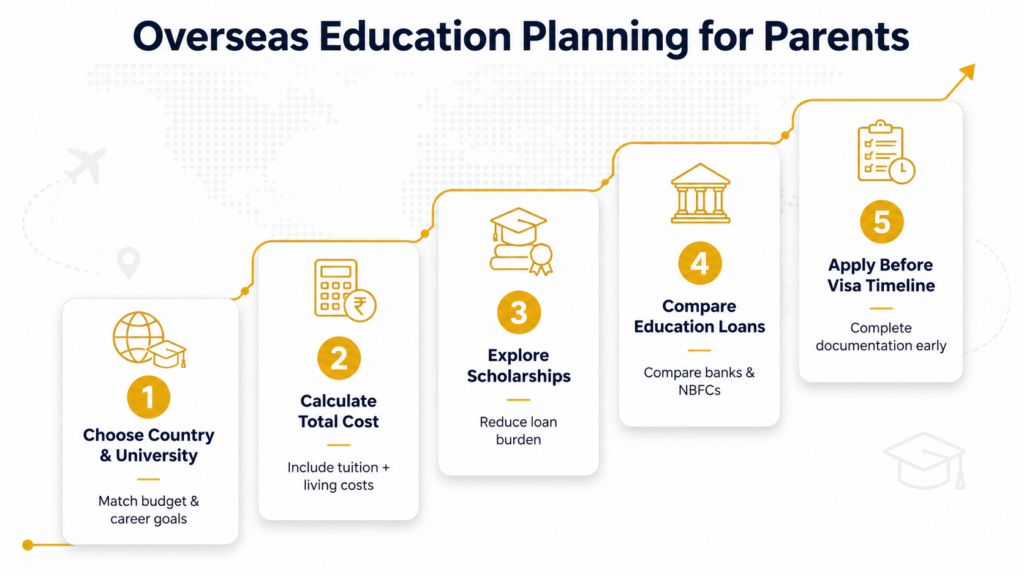
Overseas education planning for parents is inclusive of three pillars:
- Deciding on the country and university to attend according to the budget and career ambitions.
- Realising the actual total cost, not the tuition fee that is posted on the site.
- Obtaining an appropriate education loan to study overseas before visa restrictions run out.
A lot of parents also thought that they would not be qualified to take a loan, and we made them realise their eligibility. This clarity early modifies the whole process of planning.
Best Countries to Send Child Abroad for Education
The selection of the best countries to take a child abroad and pursue studies is based on budget, duration of study, as well as post-study work. Each country presents an alternative combination of price and potential.
| Country | Typical Living Cost (INR/year) | Typical Annual Tuition (INR) | Course Duration |
| Germany | ₹8–10 lakh | ₹0–3 lakh (public universities) | 2 years |
| UK | ₹10–15 lakh | ₹22–35 lakh (MBA up to ₹76 lakh) | 1 year (most Master’s) |
| Canada | ₹7–10 lakh | ₹8–20 lakh | 1–2 years |
| USA | ₹10–18 lakh | ₹18–44 lakh (MBA up to ₹73 lakh) | 1–2 years |
| Australia | ₹8–12 lakh | ₹15–30 lakh | 1–2 years |
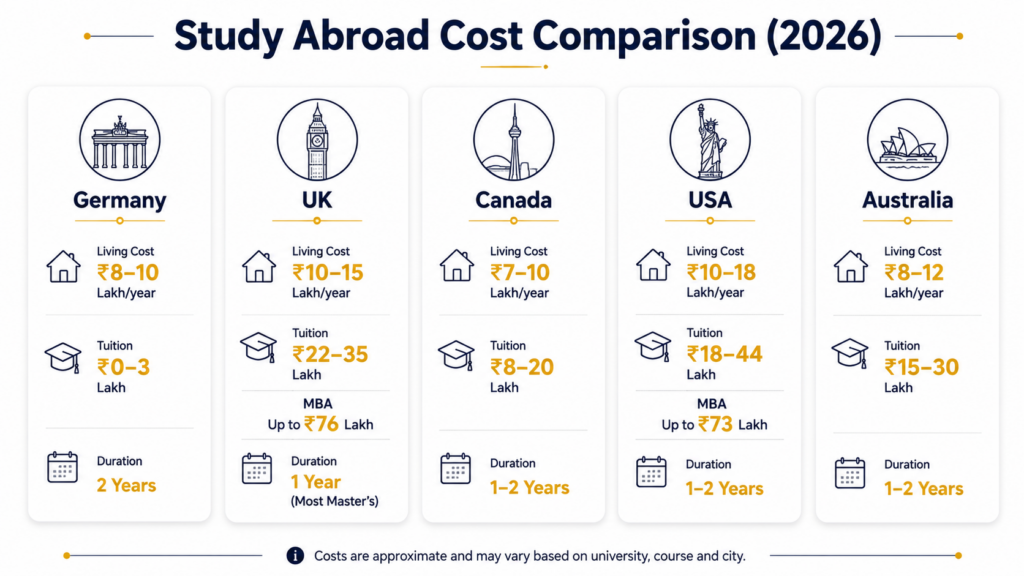
Germany and some destinations in Europe are good bets among families which want to have zero tuition or close to it. Canada and Australia strike a balance between quality education and an average total expenditure.
It is a stage at which parents tend to begin when planning serious overseas education planning for parents to attend will determine all the costs and loans you will incur.
The one-year Master’s in the UK works out at fewer dollars despite the apparent high yearly expenditures. This is part of the reason why it has always featured in the list of the best countries to take children on a study abroad trip for low-budget families.
When parents request us to identify the most suitable countries where to send a child abroad to study, we consider tuition, safety and rules on part-time work and post-study visa in combination and not on tuition fees alone.
Total Cost of Studying Abroad for Parents: What to Expect
The case of parents knowing the overall cost of studying in a foreign country implies not just tuition. Real expenses are estimated to be 10-20 per cent less than the estimates which families make, and therefore a buffer value is necessary.
The overall amount that it costs parents to study abroad usually involves:
- The university fee imposed on the whole period of the programme.
- Housing accommodations or renting, on-campus or in-house.
- Food, domestic communication, cell phone bills, daily personal spending.
- Most of the study destinations have health insurance that is mandatory.
- Visa processing, airline tickets and one-time relocation costs.
- Cost of books, course material and equipment.
In most popular destinations, Indian students on average require ₹12 lakh and ₹55 lakh annually based on the programme and country. This is the reason why it is so crucial to compute the true cost of studying abroad to parents prior to taking a loan.
After getting a clear realistic annual family budget, one of our students has made a funding available through the SBI, through comparing with several types of lenders via our platform.
These are the numbers that need to be calculated early in the overseas education planning for parents, and it will avoid the recent financial shocks nearer to departure.
Scholarships for Studying Abroad: Reducing the Loan Burden
Studying abroad scholarships can be significant in terms of the amount of money you borrow. They can be based on merit, need, or university- or government-financed.
Some of the usual types of scholarships to study abroad involve:
- Merit scholarships based on good grades and test results.
- Scholarships based on need to be provided to children in less affluent families.
- Scholarships related to a specific country, like the DAAD in Germany or the Chevening in the UK.
- Scholarships at universities where tuition is automatically decreased upon admission.
The study abroad scholarships, when combined with a taken study abroad education loan of a lesser amount, will reduce your EMI and overall interest payment.
Parents regularly report that once they have talked to our experts, they have a much easier time understanding the loan process, particularly once they realise how many dollars a scholarship will counter.
Education Loan for Study Abroad: The Complete Guide
An education loan to study abroad plays the role of bridging social savings to the actual cost of the programme. The selection of the correct lender is as crucial as the selection of the correct university.
Secured vs Unsecured Education Loans.
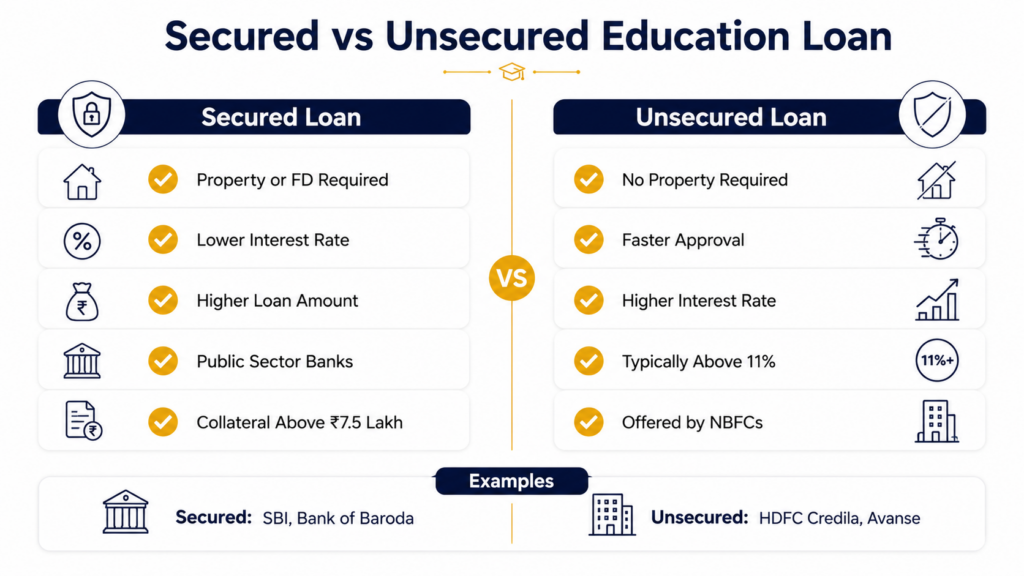
A secured study abroad education loan involves providing property/fixed deposit as security, whereas the unsecured loan does not.
- Secured loans usually have lower interest rates and increased sums of money.
- Unsecured loans are quicker and generally charged at a higher rate than 11%.
- The public sector banks largely demand collateral above 7.5 lakh to study abroad.
- NBFCs such as HDFC Credila and Avanse have 100 per cent financing without collateralising any property.
Loan Eligibility Assistance
The education loan requirements to study abroad are based on the academic background, the offer of admission and the income of the co-applicant. This is an essential component in overseas education planning for parents, which needs to happen early on amongst parents.
- The student should possess a confirmed offer letter from a recognised university.
- Almost all lenders require a co-applicant, who is often a parent.
- Increased co-applicant income enhances the sanctioned loan amount.
- A history of the co-applicant with clean credit makes it faster to be approved.
Documents Required
You can make a list ahead of time and avoid procrastination in your parents’ timeline for an overseas education plan.
- University Admission or offer letter together with university fee structure.
- IELTS or GRE standard test scores and academic mark sheets.
- Photocopies of income, bank statements and IT returns of the co-applicant.
- The existence of collateral documents, such as property valuation papers, implicates this but only on a case-by-case basis.
Interest Rates: Banking Partners comparison.
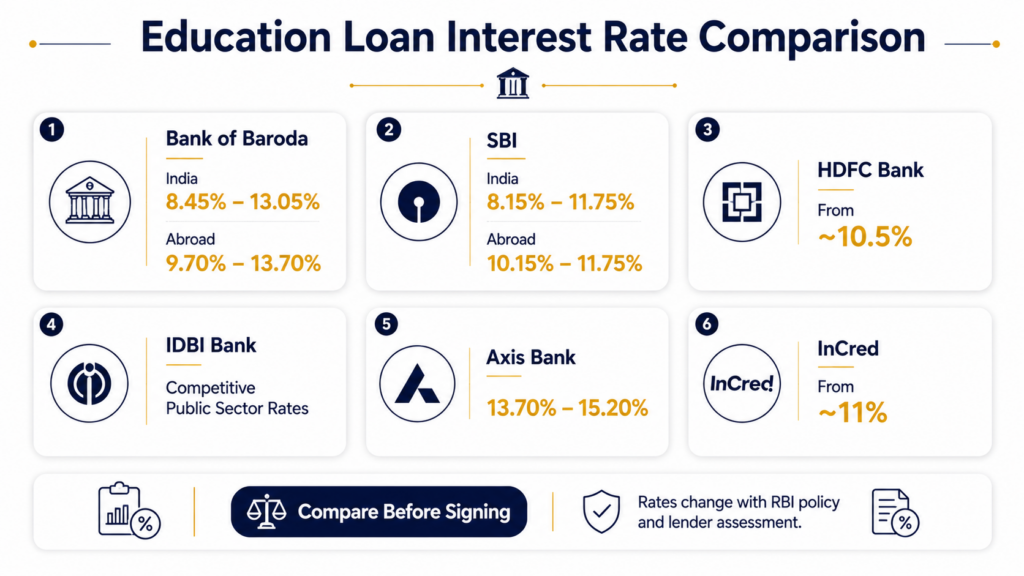
Lenders differ widely in interest rates; hence, the crux of smart overseas education planning for parents lies in comparison of lenders. It is this one or only comparison step that can frequently save families the most money during the loan term.
| Lender | Collateral | Indicative Interest Rate (p.a.) |
| Bank of Baroda | Required above ₹7.5 lakh | 8.45% – 13.05% (India)9.70% – 13.70% (abroad) |
| SBI | Required above ₹7.5 lakh | 8.15% – 11.75% (India)10.15% – 11.75% (abroad) |
| HDFC Bank | Case-dependent | From ~10.5% |
| IDBI Bank | Required above threshold | Competitive public-sector rates |
| Axis Bank | Often unsecured | 13.70% – 15.20% |
| InCred | Usually unsecured | From ~11% |
Rates are constantly fluctuating in accordance with the policy of the RBI and the risk evaluation of the lender; thus, it is always best to verify the most up-to-date rates directly with the bank prior to signing.
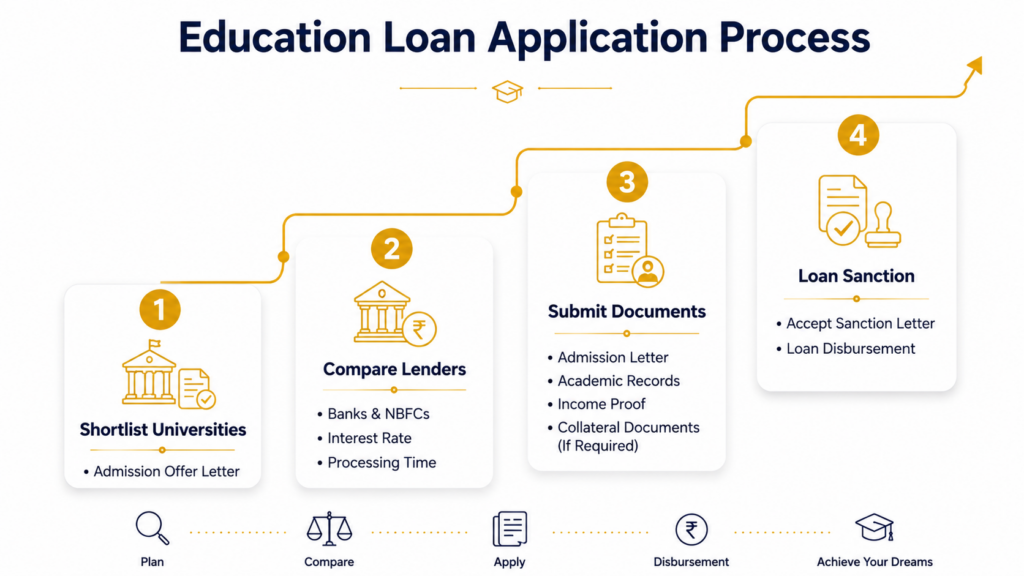
Loan Application Process
An education loan abroad will also be much less stressful with a clear step-by-step procedure, and that will put your general overseas education planning for parents on the right track.
- Identify and shortlist universities and ensure the admission offer letter.
- Compare interest rates and processing time of various banks and NBFCs.
- Provide documentation and undergo application and collateral checks.
- Accept the sanction letter and finalise disbursement procedures.
I believed that acquiring an education loan was quite cumbersome, but the process of obtaining an education loan was explained by the staff at Gateway International and assisted me in selecting the appropriate bank, a sentiment that we continue to hear echoing throughout even after the process has been finished.
Common Mistakes Parents Make
This will save your child’s admission schedule and your budget by avoiding such mistakes.
- Waiting until it is too late and almost time to get the visa to apply.
- Disregards the interest that accrues during the period of the moratorium, which accrues when not paid.
- Selecting a lender by brand name rather than the actual interest rate.
- Failing to compare among banks before signing any loan agreement.
Making comparisons across different banks without the need to visit each bank became the greatest relief after using our site to compare offers, one parent enthused.
Financial Planning Tips Before Departure
Overseas education planning for parents doesn’t end with an education loan. Planning finances as a smart pre-departure step also allows for managing expenses of studying abroad and ensures a decrease in financial strain, irrespective of where your child is going to school.
- Repay the interest paid over the period of moratorium to pay less interest and decrease future EMIs.
- Keep an eye on the exchange rates of currency and move money when the exchange rates are in favour to have maximum savings.
- Always make sure you have a backup budget of at least 1520 percent of the amount of money you are supposed to spend on education in case of unplanned costs.
- Make the best out of your tax savings by claiming Section 80E tax benefits on interest payments on loans incurred to finance your education.
- Compare your repayment plan after your child has a part-time job, internship or a campus placement to fast-track loan repayment.
Adhering to such financial habits makes the overseas education planning for parents more organised, as the parent families are sure to control the costs and aid the interest of the child to have access to international education.
Choosing the Right Lender: A Quick Checklist for Overseas Education Planning for Parents
One of the most important aspects of overseas education planning for parents is the choice of an education loan. Looking over the advertised rate can enable families to save on the cost of borrowing and prevent unforeseen costs.
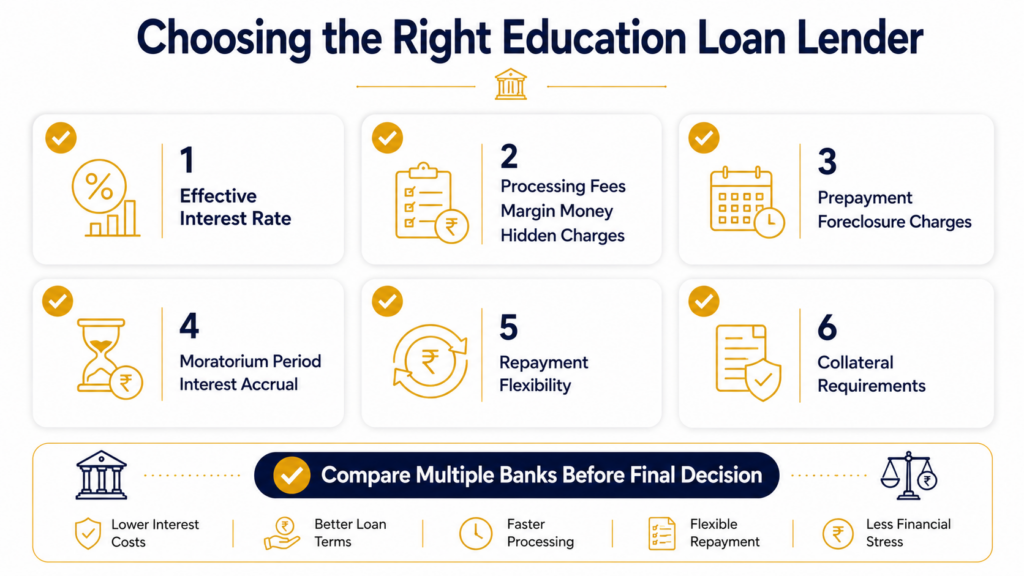
- Find out the effective interest rate, not only the amount being advertised by lenders.
- Check processing fees, margin money requirement and pre-application hidden charges.
- Establish whether there are prepayment or foreclosure fees in case you intend to pay the loan before it becomes due.
- Know the life of the moratorium and the rate of accumulation of interest while enrolled in a course and during the holiday of repayment of your child’s loan.
- Compare loan requirements, repayment, and collateral requirements to come up with the best option to meet the financial needs of your family.
As an extension of your overseas education planning for parents, you can also easily compare education loans with some of the banks with a single application. Our counsellors will assist you in finding the lender that will best suit your financial request, making it easier and less expensive to have a study abroad experience.
FAQs
Who qualifies to get a study abroad education loan?
Any Indian student who has confirmed an offer of university admission and a financially eligible co-applicant, typically a parent, can apply for an education loan to study abroad.
Is it possible to take a loan without security?
Yes, a number of NBFCs and some banks are providing unsecured education loans to study abroad, but they come at a higher interest rate than the secured or guaranteed ones.
What is the duration of the Loan Procedure?
It can take public sector banks between four and eight weeks, and in numerous cases, it takes a couple of weeks for NBFCs to sanction an education loan to study abroad.
Is it possible to decrease my education loan amount by using scholarships?
Yes, studying abroad as a scholar reduces your loan amount, and thus the volume of EMI and the sum of interest you pay over the course of your loan decreases.
Which forms do you need when applying for a loan to finance your education?
The admission letter, academic records, proof of co-applicant income, bank statements and collateral documentation (when the loan is secured) are generally required.
Conclusion
Careful overseas education planning for parents makes financial planning a stress experience to a stress free confident process. It is an art fundamentally premised on inquiry, comparison, and temporality. To know the total cost of studying abroad as a parent to decide on the right education loan to study abroad, each step counts. Through scholarships, the right banking partner, and preparing early, it is possible to make your child realise his or her dream. There are 23,000+ students and families across the USA, UK, Canada, Australia, Germany, and others that have been assisted by Gateway International over 15+ years. Get a meeting about your free education loan today at Gateway International and make the next sure step towards your child’s global education.