A practical guide for Indian students and parents comparing NBFC education loans when conventional income documents are unavailable.
Finding the best NBFC for education loan without income proof is not as simple as choosing a lender offering unsecured loans. Current lender information shows that income assessment can still matter even when an ITR is unavailable. Some lenders may consider other financial documents, an additional co-applicant, collateral, academic strength or future earning potential.
The key distinction is that no ITR does not automatically mean no income proof. Likewise, a collateral free education loan does not imply that the lender does not pay attention to the repayment power.
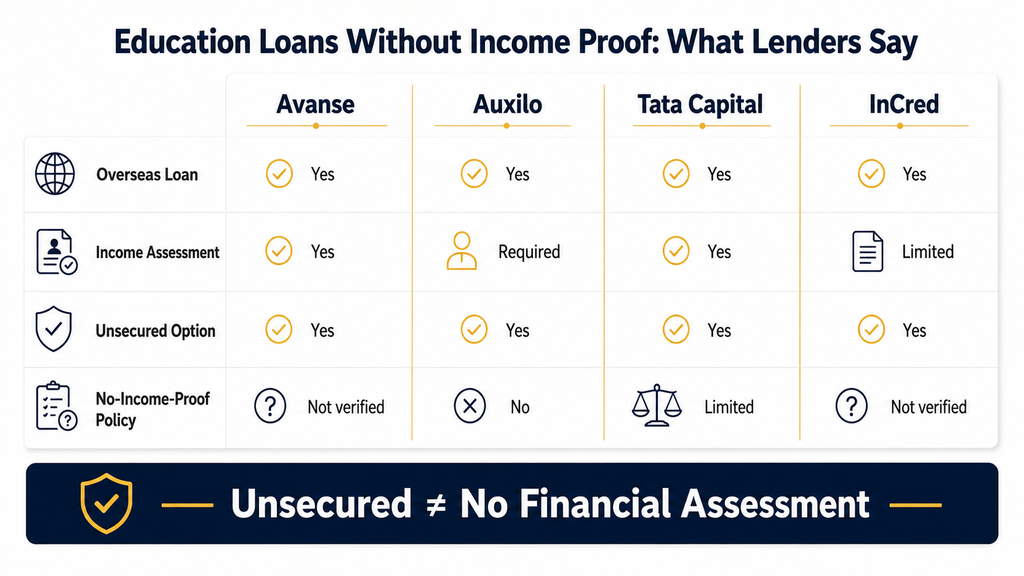
Overview: Education Loans Without Income Proof
| Lender | Overseas Education Loan | Income/Co-applicant Assessment | Unsecured Option | No-Income-Proof Policy Verified? |
| Avanse | Yes | Yes | Yes | No blanket policy verified |
| Auxilo | Yes | Earning co-borrower required | Yes | No |
| Tata Capital | Yes | Yes | Yes | Limited flexibility mentioned |
| InCred | Yes | Public information is limited | Yes, subject to terms | Not verified |
Key takeaway: Applicants searching for the best NBFC for education loan without income proof should not interpret unsecured lending as lending without financial assessment.
Can You Really Get an Education Loan Without Income Proof in India?
Possibly in limited circumstances, but the phrase education loan no income proof India needs to be understood carefully.
Students themselves may have no employment income. A lender can instead assess the co-applicant’s repayment capacity, financial documents, credit profile or other eligibility factors.
Tata Capital’s official education-loan documentation guide states that an education loan may still be considered when income proof is unavailable if repayment capability can be established through factors such as a financially stable co-borrower, collateral or other income sources.
However, the same page also states that ITR is necessary when applying for an education loan and says co-applicant income proof is generally required.
Therefore, applicants looking for the best NBFC for education loan without income proof should not assume that missing documents automatically qualify for an exemption.
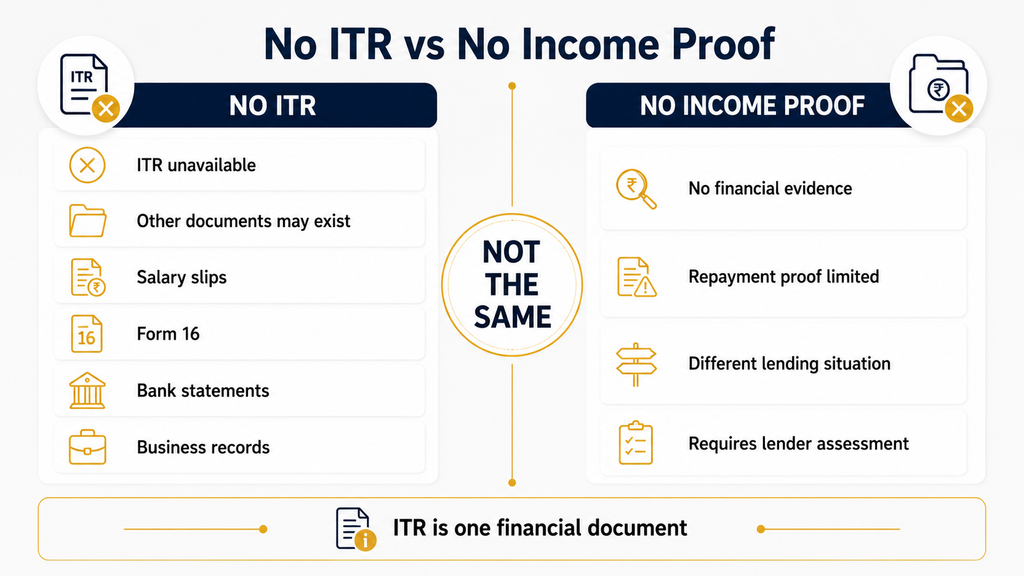
Is an NBFC Loan Without ITR the Same as No Income Proof?
No.
An NBFC loan without ITR and a loan without any financial evidence are different situations.
ITR is one form of financial documentation. Depending on the applicant’s employment type and the lender’s current requirements, other documents may also be relevant.
| Applicant Situation | Documents That May Be Relevant |
| Salaried co-applicant | Salary slips, Form 16, bank statements and ITR where required |
| Self-employed co-applicant | ITR, business statements and financial statements |
| Alternative income available | Supporting income records accepted by the lender |
| Secured application | Financial documents plus collateral documents where applicable |
Tata Capital’s education-loan page lists Form 16, bank statements and salary slips for salaried cases. For self-employed cases, it lists ITR, Profit and Loss Statement, Balance Sheet and bank statements.
So, when comparing the best NBFC for education loan without income proof, ask a more precise question:
Which financial documents will the lender accept for my particular profile?
Does Avanse Offer an Education Loan Without ITR?
Avanse considers both the student’s potential and the co-borrower’s financial profile.
According to Avanse’s official co-applicant guidance, its evaluation can consider academic scores, entrance scores and university pedigree while assessing a student’s employability potential.
However, Avanse also states that the co-borrower’s financial background is assessed.
Its education-loan information includes co-applicant income proof among the relevant documentation.
For salaried co-applicants, its guidance refers to salary slips as income proof. Self-employed co-applicants may need prescribed business and financial documents.
Therefore, Avanse should not be presented as a confirmed NBFC loan without ITR option for every applicant.
A strong student profile may support an application, but financial assessment can still remain part of the lender’s NBFC eligibility criteria.
Read out: What you must know about co-applicant before applying for an education loan
Can Auxilo Be Considered Without Strong Income Proof?
Auxilo’s requirements make the role of the co-borrower particularly important.
Its official study-abroad education-loan page states that an overseas education loan must be co-signed by an earning co-borrower in India.
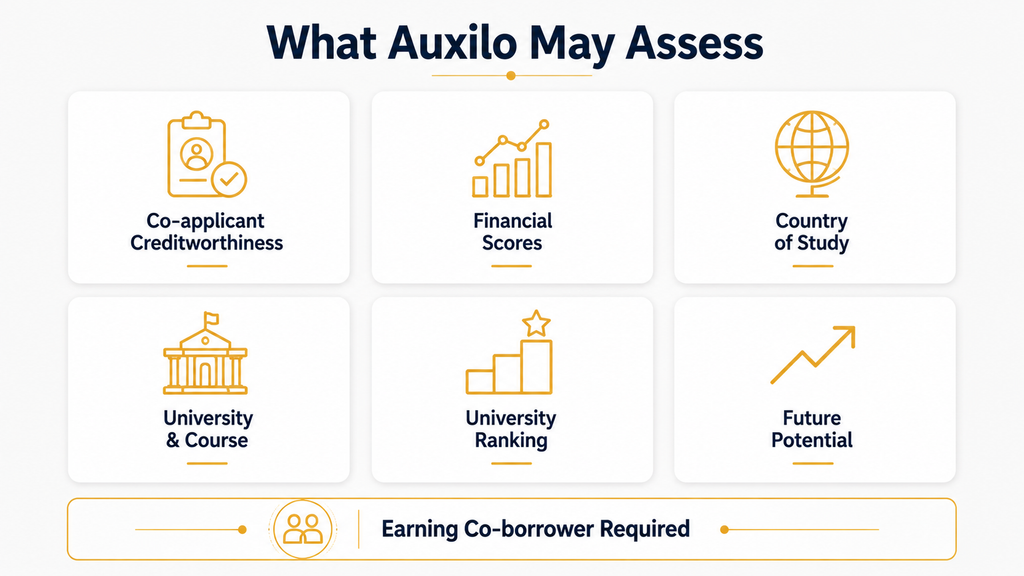
Auxilo also states that its assessment can consider:
- Co-applicant creditworthiness
- Financial scores
- Country of study
- University and course
- University ranking
- Future potential
If the primary co-applicant does not meet eligibility requirements, Auxilo says applicants can add additional co-applicants, including multi-city co-applicants.
Therefore, someone comparing the best NBFC for education loan without income proof should not classify Auxilo as a lender that ignores income.
Its current NBFC eligibility criteria explicitly involve an earning co-borrower and financial assessment.
What Does Tata Capital Say About Missing Income Proof?
Tata Capital provides more nuanced information about this situation.
Its 2026 education-loan document guide says an education loan may still be considered when income proof is unavailable if repayment capability can be demonstrated through another financially stable co-borrower, collateral or other sources of income.
However, the same official page also indicates that:
- Co-applicant income proof is generally required.
- Salaried cases may require salary and banking documents.
- Self-employed cases may require business and financial records.
- ITR is described as necessary when applying for an education loan.
Tata Capital’s main education-loan page also explains that students without a salary may need a financially stable co-applicant with verifiable income.
Therefore, Tata Capital should not simply be labelled the best NBFC for education loan without income proof.
Its official information suggests that alternative ways of demonstrating repayment capability may be considered in some circumstances, but underwriting and documentation requirements still apply.
What About InCred Education Loans?
InCred’s official education-loan page confirms that it offers education loans for overseas study.
It also currently advertises collateral-free education loans up to ₹1.5 crore, subject to terms and conditions.
However, the public official material reviewed for this article does not provide enough evidence to establish:
- A general no-ITR policy
- A no-income-proof education-loan policy
- When co-applicant income documents can be omitted
- Which alternative income documents can replace ITR
For this reason, InCred cannot currently be ranked as the best NBFC for education loan without income proof based on the evidence reviewed.
[UNCERTAIN: InCred’s public official material reviewed for this article does not establish a no-income-proof or no-ITR policy.]
Which Applicant Situation Matches Yours?
Before searching for an NBFC loan without ITR, identify why conventional income documents are unavailable.
| Your Situation | What to Check |
| Student has no salary | Check co-applicant requirements |
| Salaried parent has no ITR available | Ask which alternative documents the lender accepts |
| Self-employed parent has no ITR | Check business and financial-document requirements |
| Primary co-applicant has weak eligibility | Check whether an additional co-applicant is permitted |
| Family has acceptable collateral | Explore secured-loan eligibility |
| Student has a strong academic profile | Check how the lender evaluates academics and future potential |
| No income, collateral or suitable co-applicant | Do not assume an NBFC will approve the application |
Key takeaway: The best NBFC for education loan without income proof depends on what financial evidence is available, not simply on whether an ITR is missing.
Secured or Unsecured Education Loan: Which Should You Explore?
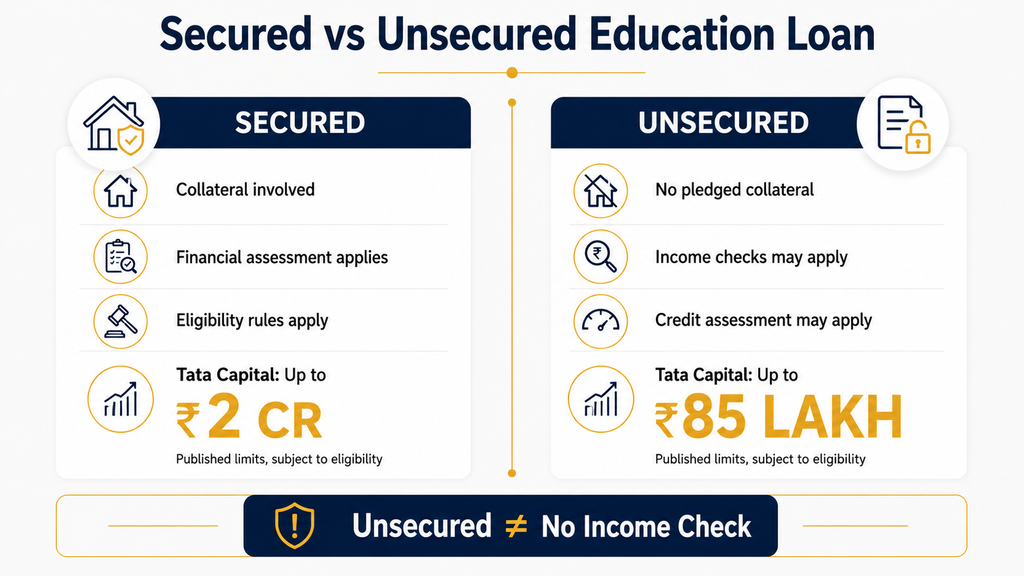
Students researching an education loan no income proof India option often confuse unsecured lending with lending without financial assessment.
They are different.
An unsecured education loan does not require pledged collateral, subject to lender eligibility. However, the lender can still assess income, creditworthiness and repayment capacity.
Tata Capital currently publishes unsecured education loans up to ₹85 lakh and secured education loans up to ₹2 crore, subject to eligibility, on its official education-loan page.
Avanse also offers unsecured education-loan options while continuing to assess co-applicant finances.
Auxilo states that it offers secured and unsecured education-loan structures while considering financial and applicant-specific factors.
Therefore, collateral-free availability alone should never determine the best NBFC for education loan without income proof.
Borrowing Rule
Students and parents should compare the complete repayment commitment, not only the sanctioned amount or advertised loan ceiling.
What Documents Should You Prepare?
When applying for an NBFC loan without ITR, prepare every available document that can help the lender understand the student and co-applicant profile.
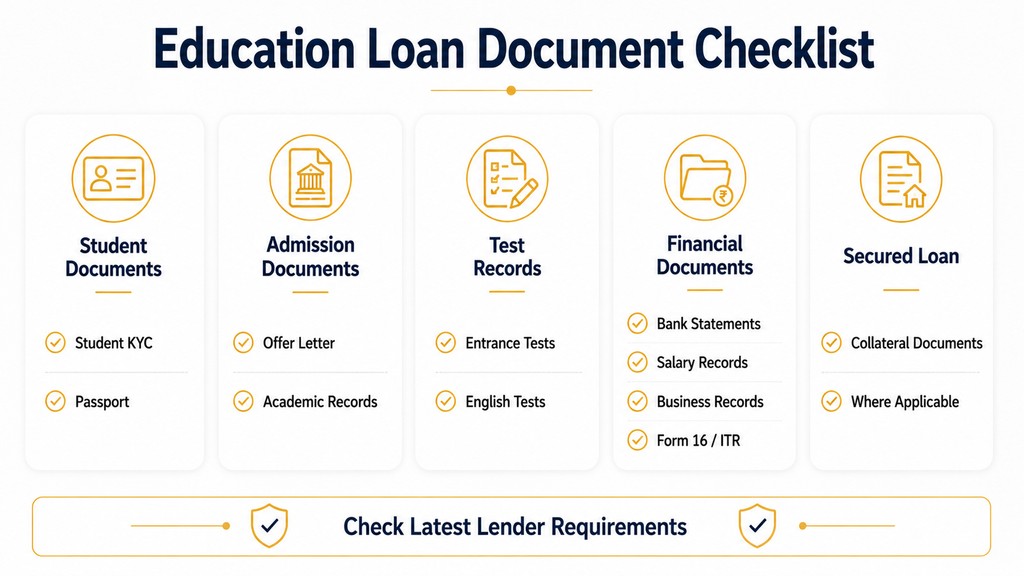
Commonly relevant documents include:
- Student KYC documents
- Passport
- University admission or offer letter
- Academic records
- Entrance or English-language test results, where applicable
- Co-applicant KYC
- Available salary or business documents
- Bank statements
- Form 16, ITR or financial statements where required
- Collateral documents for secured applications
Precise record keeping is conditional on the profile of the lenders and applicants. Do be sure to examine the most up-to-date official requirements prior to applying.
Mistakes to Avoid When You Do Not Have ITR
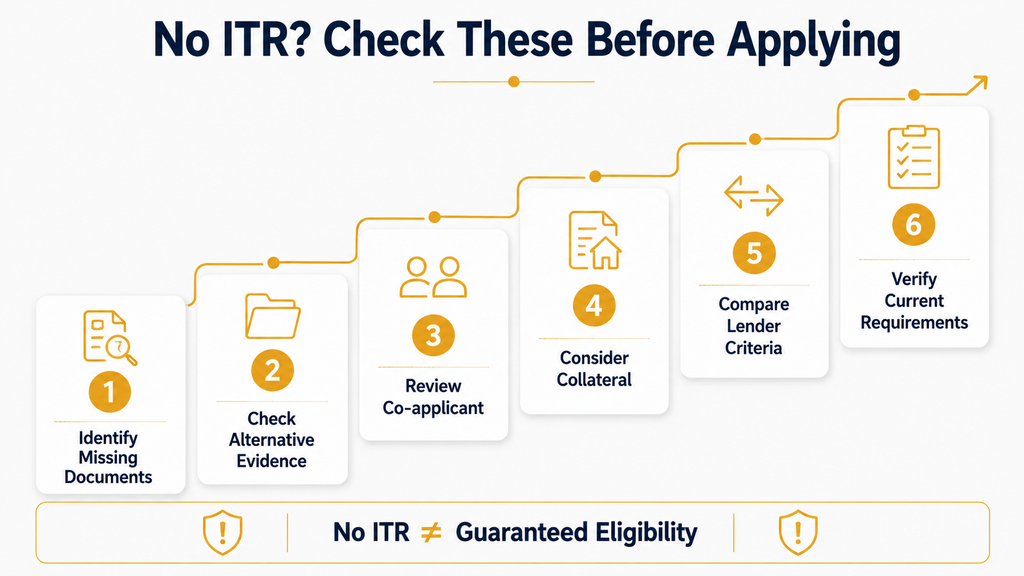
- Assuming an NBFC loan without ITR means no income assessment.
- Confusing an unsecured loan with an education loan no income proof India option.
- Hiding missing income or financial documents from the lender.
- Assuming a strong university or course guarantees loan approval.
- Choosing a lender only because it advertises a high maximum loan amount.
- Ignoring NBFC eligibility criteria and co-applicant repayment liability.
- Assuming collateral automatically removes income-document requirements.
- Applying without checking the lender’s latest documentation requirements.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education.
If you are searching for the best NBFC for education loan without income proof, Foreign Edu Loans can help you:
- Compare potentially suitable lenders.
- Understand NBFC eligibility criteria.
- Identify documentation gaps.
- Explore co-applicant options.
- Coordinate the loan application.
The approval and interest rates charged are final and subject to the lender and the profile of applicant, documents and existing policies.
FAQs
Which is the best NBFC for education loan without income proof?
There is no universal best NBFC for education loan without income proof. Eligibility depends on lender documentation, underwriting and the complete applicant profile.
Can a student get an education loan without a salary?
Yes. For an education loan no income proof India search, remember that students may have no salary, while lenders can still assess a co-applicant’s finances.
Does a good university improve education-loan eligibility?
It can be one factor. NBFC eligibility criteria may consider academics, university, course, future potential and the co-applicant’s financial profile.
Can collateral replace income proof?
Not automatically. Collateral may support a secured loan, but lenders can still assess repayment capacity and financial eligibility.
Can I get an unsecured education loan without ITR?
An unsecured NBFC loan without ITR may be considered depending on lender rules. Unsecured lending does not automatically remove income-document requirements.
Conclusion
Choosing the best NBFC for education loan without income proof requires looking beyond advertisements for collateral-free or high-value education loans. Current official information shows that lenders may consider academic strength, university profile, future potential, additional co-applicants, collateral and alternative financial evidence. However, repayment capacity and documentation remain important.
If an ITR is unavailable, identify what alternative financial evidence you can provide and compare current NBFC eligibility criteria carefully. Do not assume that no ITR means no financial verification.
Students and parents should also consider repayment responsibility and co-applicant liability before borrowing.