An MS in the USA tends to begin as an exciting step and to wind up as a spreadsheet of figures. The two questions every student and parent will ask us in the beginning are: total cost kitna hoga and, the second one: loan kitna lena padega.
This guide will de-aggregate the actual cost of MS in the USA, demonstrate to you how to compute the correct education loan for MS in USA and discuss the concept of secured and unsecured loans. We have over the years been through the education loan process with thousands of students, and the fear of the big number is a topic of conversation in nearly every initial meeting.
At the end, you will find out how much loan you will need to finance your MS in the US, and you will know more about how to check your monthly EMI prior to your application.
Why Getting the Loan Amount Right Matters?
Under-application of the loan amount to pursue a master’s in the US results in lapses during the course. Requesting excessively throws your interest load on. Calculating how to get your education loan in the USA at the beginning is less expensive and less stressful.
- An estimated cost of your education loan for MS in USA would enhance your financial resume and make you confident in responding to questions during the visa interview.
- Planning the correct education loan to study MS in USA will allow you to get rid of expensive last-minute bogofuel loans at high interest rates as you study overseas.
- Investing in the right education loan for MS in USA will enable your family to budget on manageable EMIs, without straining your household budget unnecessarily.
Most of the students had initially thought that they could not get a loan until we managed to make them comprehend their true eligibility. The Right Old Fashioned Wrong Number.
What Will an MS in the USA really cost in 2026?
You should have the costs of an MS in the USA clear before making such a decision on the amount of loan. The university costs vary in terms of tuition, living expenses, as well as one-time fees depending on the nature of the university.
The rate of public universities is usually cheaper compared to the private ones, yet non-residents are usually charged international rates. MS in USA daily costs can easily go beyond USD 100,000 over the course of two years between guarded and Ivy League tiers.
The initial step to an accurate calculation of the education loan for MS in USA is knowing the price of an MS in the USA.
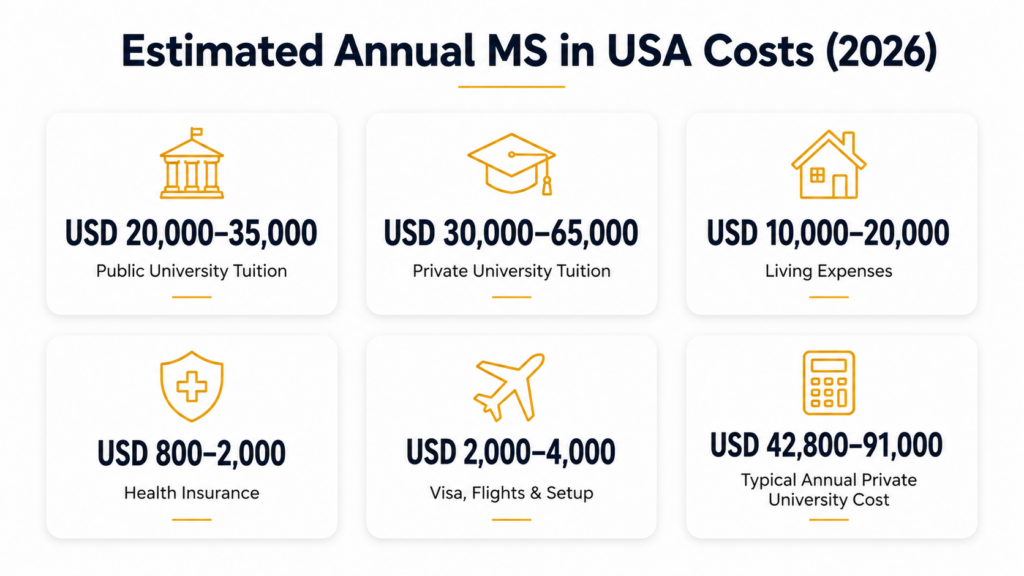
| Expense Category | Estimated cost | Key details |
| Public University Tuition | USD 20,000-35,000 annually | Tend to be less expensive than X University. |
| Private University Tuition | USD 30,000-65,000 annually | As STEM and business coursework are considered a premium, they are pricier per credit. |
| Living Costs | USD 10,000-20,000 annually | Includes housing, local transport and food. Students in cities such as New York and San Francisco ought to budget on the higher side. Part-time employment on campus can be applied to cover costs. |
| Visa & SEVIS Fees | A few hundred dollars | Includes the F-1 visa application fee and SEVIS fee. |
| Health Insurance | USD 800-2,000/year | It is compulsory for a majority of international students. |
| Travel & Preliminary Establishment | USD 2,000 4,000 | Covers computer, transportation, and textbooks. |
The following is a simplified derivation to help you get an idea of the MS in USA total costs for a two-year programme as the foundation for calculating your education loan for MS in USA.
| Cost Element (USD) | Annual Cost (USD) | Frequency | Annual Cost (INR)* |
| Tuition (private university) | 30,000 – 65,000 | Recurring, per year | 28.1L – 61L |
| Tuition (public university) | 20,000 – 35,000 | Recurring, per year | 18.7L – 32.8L |
| Health insurance | 800 – 2,000 | Recurring, per year | 0.75L – 1.9L |
| Visa, SEVIS fee, flights, and setup | 2,000 – 4,000 | One-time, first year only | 1.9L – 3.75L |
| Total (private university path) | 42,800 – 91,000 | Per year | 40.2L – 85.4L |
| Living expenses (housing, food, transport) | 10,000 – 20,000 | Recurring, per year | 9.4L – 18.7L |
| Total (public university path) | 32,800 – 61,000 | Per year | 30.8L – 57.3L |
The approximate values of INR are only indicative and vary with fluctuations in exchange rates; always make sure to check the current conversion rates and only then decide your loan amount for an MS in the US. The precise price of an MS in the USA at your particular university might vary, and therefore reconcile it with the official price of attendance page of your university.
How Much Education Loan Do You Need for MS in the USA?
The majority of students have no necessity to finance the whole amount out of savings. An education loan for MS in USA may, in most instances, finance nearly 100% of your qualifying expenses, including tuition and other living costs, travel and insurance, depending on the borrower and your account.
This is our most frequently asked question: how large a loan to invest in MS in the US should I, in reality, apply for? An honest answer involves your university and that of your co-applicant profile, and the need to turn to collateral or not.
The overall amount that MS students in the US usually request can be seen as follows according to the type of university:
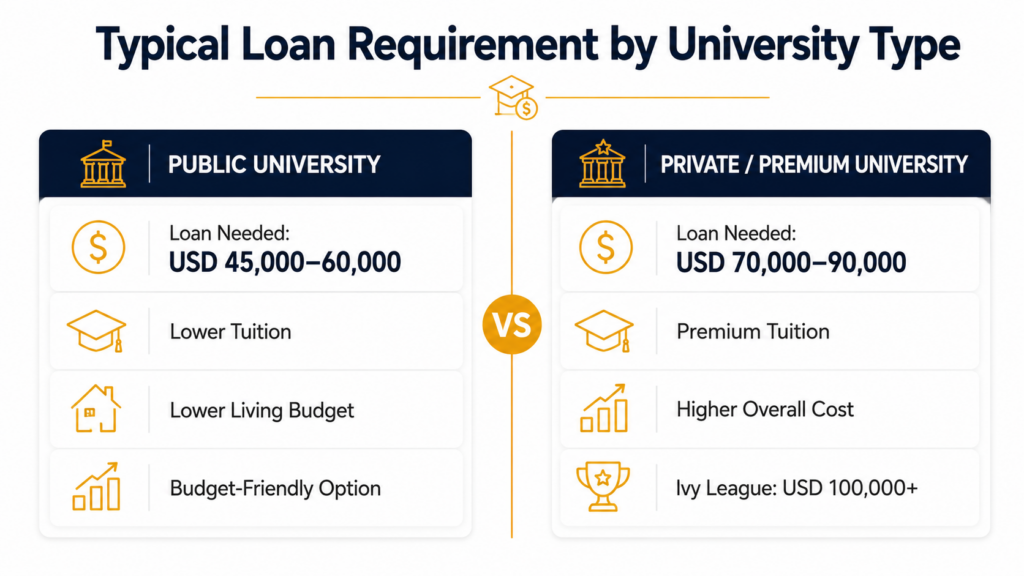
- The average tuition cost and living cost of USD 45,000-60,000 are usually necessary to facilitate the financing of an MS in the USA in public universities by the students.
- The total monetary costs of attending a private university are typically USD 70,000-90,000, which, in total, would need a loan for an MS in the USA to be taken out by the student.
- The high tuition and living expenses involved in an MS in the USA might mean that students seeking an education loan for MS in USA of USD 100,000 or more to undertake their studies in premium or Ivy League universities.
A student of ours got a loan recently funded by SBI, after using the services of our site to compare various lenders, and this saved him a lot of interest compared to the interest he would have paid to his bank of choice.
Tuition vs Living Vs Travel Vs Insurance: What really happens to the Loan
Knowing what your education loan for MS in USA will also prevent you from being under-borrowed. An education loan that is planned to pursue the MS in the USA must take into consideration all the categories as listed below rather than just tuition.
- The most considerable cost is tuition fees, which typically contribute 60 per cent- 75 per cent of an education loan for MS in USA.
- MS in the USA, at an average cost of living, makes up 20%30 percent of the total education loan, which includes accommodation, food, and transport charges.
- The remaining 5%10% of an education loan for MS in USA is usually covered by travel, insurance (health insurance) and other one-time costs.
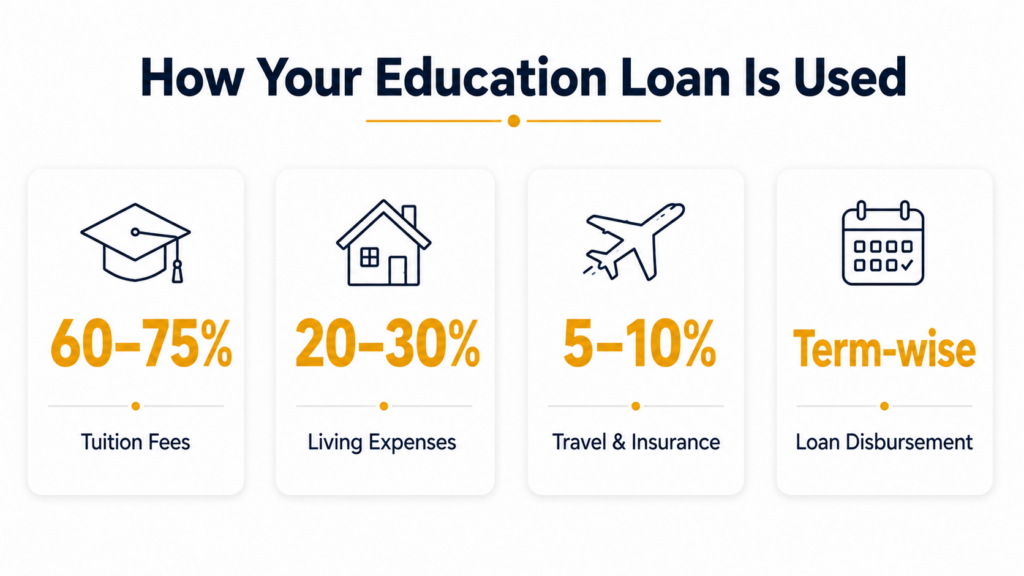
A large majority of Indian lenders such as SBI, HDFC Bank, Bank of Baroda, Axis Bank, InCred and IDBI Bank have their disbursement done in instalments based on each academic term, rather than a single lump sum.
Secured vs Unsecured education loan for MS in USA
The decision to use collateral will heavily depend on the amount of loan you need to complete your master’s in the US, and even how much loan you need to request without collateral changes your whole application plan.
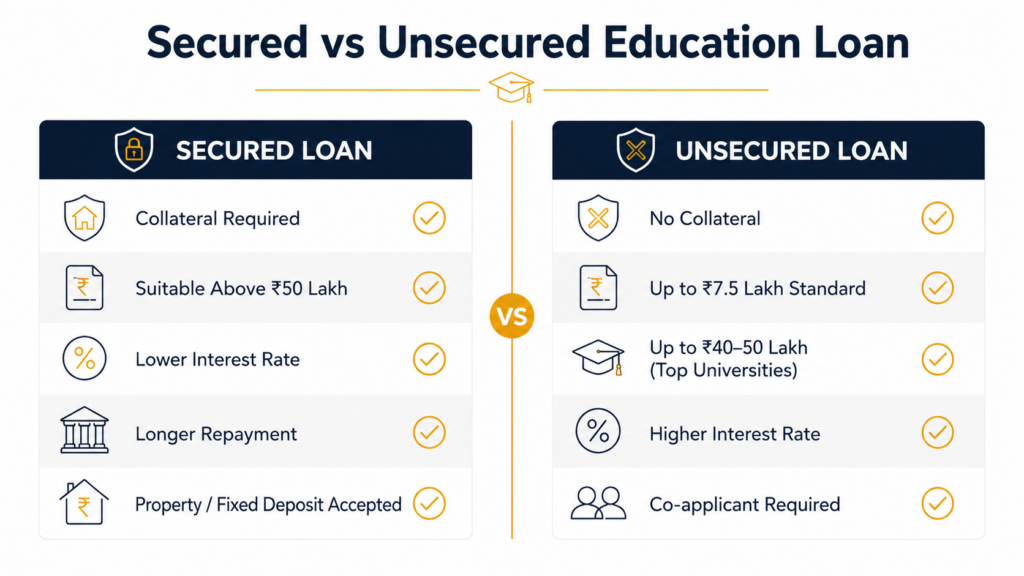
Without Collateral
- The MS in USA in the unsecured version of the education loan of around INR 7.5 lakh is usually offered at a co-applicant position without collateral.
- Collateral-free education loan for MS in USA of up to INR 40- 50 lakh are available with some lenders to students studying at the premier universities in the USA.
- Usually, though, unsecured education loan for MS in USA attract a slightly higher interest rate than secured loans.
With Collateral
- MS students in the USA acquiring education loans exceeding INR 50 lakh are typically collateralised, at the discretion of the lender.
- The accepted collateral can be residential property and fixed deposits, or any other approved asset.
- Education loan for MS in USA are generally at reduced interest rates with increased pay terms.
When making a decision on whether to take a secured or unsecured path, parents regularly inform us that when they talked to one of our experts, the process of making a decision on the loans became far less daunting.
Sample Loan Amount Scenarios
The following examples show the average education loan needed in various MS programme budgets.
| Scenario | University Type | Loan Requested (USD) | Total Cost (USD) | Rest Funded By | Collateral |
| A | Budget-friendly public university | ~55,000 | ~70,000 | Savings and part-time work | Not required |
| B | Mid-range private university | ~85,000 | ~95,000 | Personal savings | Not required (co-applicant only) |
| C | Premium or Ivy League-tier university | 100,000+ | ~120,000 | Family contribution, if any | Required (property or FD) |
“I thought acquiring an educational loan would be a hard task, and Gateway International helped me out by explaining all the available options and guiding me to select the right bank, and this is what we hear most of the time: once the students look at their actual numbers, laid out clearly before them.
Factors That Affect Your Loan Amount for Masters in the US
- The ranking of your university of choice and whether it is on the list of eligible institutions of the lender may affect your education loan for MS in USA.
- A co-applicant who has an outstanding credit profile and could be involved in a stable income would enhance your chances of getting an MS in USA education loan.
- Having access to and the worth of security can raise the approved amount and assist you in getting an MS in USA education loan with a lower interest rate.
- With scholarships and assistantships, you may not need to pay as much towards your education demand, which can thereby decrease your required education loan for an MS in the USA.
- Academic performance, test scores, and career opportunities of your preferred course are also influential in granting an education loan for MS in USA.
How Scholarships Reduce Your Loan Burden?
In the USA, your MS cost can be decreased by the use of scholarships and university assistantships. A partial tuition waiver still lessens the education loan for MS in USA you will be servicing in the future.
- Before finalising your education loan in the USA, apply to various merit- and need-based scholarships.
- Discover graduate and teaching assistantships at an early age, in order to lower your education loan for MS in USA.
- Remember to add confirmed scholarship to your MS in USA education loan application so that you do not have to borrow more than that.
Use the EMI Calculator Before You Decide
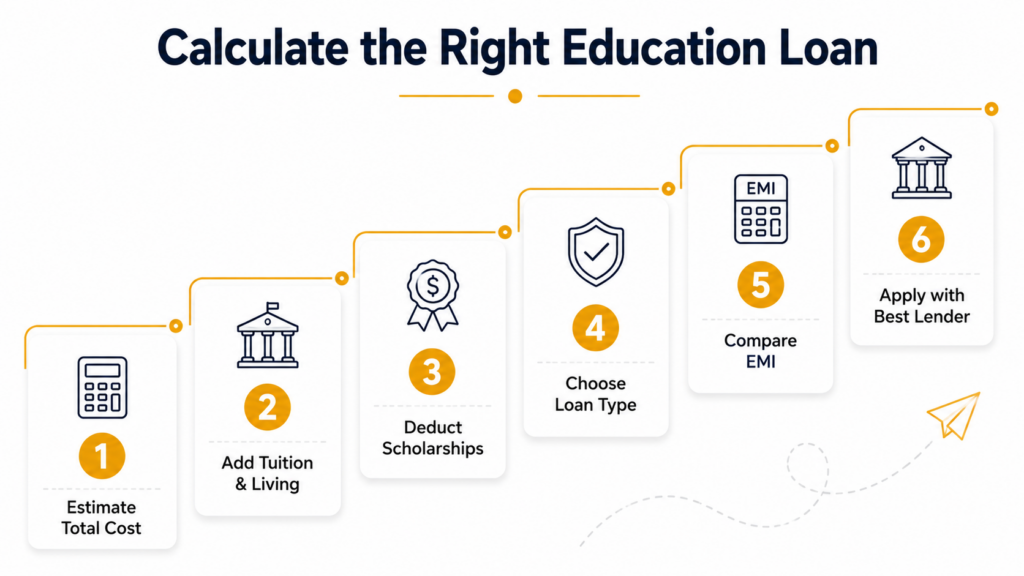
When you have some estimate of how much you will spend on your master’s in the USA, you need to know exactly what you will be spending each month. The EMI calculator will help transform your MS loan in the USA sum along with interest and tenure into a straight-out monthly balance.
- Your estimated education loan for MS in USA amount to determine your monthly EMI.
- Compare EMIs with a 10-15-year repayment period to get one that fits your budget.
- Compare the difference in EMI of secured and unsecured MS education loans in the USA.
- Divide the moratorium period to know the overall cost you will pay upon graduation.
Adjust your monthly outgo before applying to us using our free EMI calculator, and there are no surprises thereafter after disbursement.
How Gateway International Helps You Get the Right Loan Amount?
Having guided more than 23, 000 students in the USA alone and with a total of more than 15 years of experience, we are able to assist students and calculate the correct education loan for MS in USA to prevent over-borrowing and under-borrowing.
- The multiple education loan USA will allow you to compare options of advanced education loans in the United States with one application, and save time and energy.
- Get recommendations on lenders tailored to you according to your university, course, and financial backgrounds.
- Get professional advice to get the correct loan amount to pursue an MS in the USA without over-borrowing or underborrowing.
- Receive complimentary end-to-end support, lender liaison, and loan issuance.
Final Thoughts
The first step to selecting the right education loan for MS in USA is to know the overall cost of your attendance, which will include your tuition, living expenses, travel costs and any other necessary expenses. Budgeting how much you need to raise allows you to borrow the right amount or not have to get in unnecessary debt. Before applying, it can help you make a wise decision about your finances in terms of a loan, comparing various lenders and verifying your eligibility and EMI calculator. Regardless of whether you use a secured or unsecured loan, you can make your journey studying abroad a lot easier by ensuring that you make the right choice. At Gateway International, our professionals aid you in comparing lenders, finding the most advantageous loan terms and taking you through the entire process until you are certain of the appropriate education loan for MS in USA.
FAQs
Who can get an education loan for MS in USA?
Indian students who are offered a confirmed admission, have a co-applicant, and a moderate academic profile are typically eligible, although specific criteria differ depending on the lender.
Is it possible to take loans for a master’s in the US without securing them?
Yes, a number of lenders do support collateral-free loans of up to INR 7.5 lakh and beyond for students entering top schools.
What are the education loans available in the USA to get an MS?
Among the typical lenders that supply study-abroad education financing are SBI, HDFC Bank, Bank of Baroda, Axis Bank, InCred, and IDBI Bank.
Approval time for MS in USA total expenses funding: How long is the approval time?
The approval times are typically between two and four weeks, based on the complete documentation and collateral assessment procedure (where necessary).
Will scholarships decrease the amount of MS in the US I need?
Yes, any recognised scholarship or assistantship will reduce your funding need immediately and can be included in your loan application.
Which documents do you need to apply?
You usually need an admission letter, academic documents, KYC documents, co-applicant income documents, and collateral documents, where needed.