The education loan interest rates 2026 cannot be depicted using a single standard percentage for Indian students who finance overseas education. Banks, NBFCs and foreign education lenders are guided by varying pricing structures, and the final amount may be determined by the amount and profile of the applicant, co-applicant funds, university, course, collateral and credit evaluation.
Education loan interest rates in foreign countries may also vary on the basis of the loan being secured or unsecured and fixed or floating. Two applicants to the same lender can get different terms even when the applicants are approaching the same lender.
As such, rather than opting to use a lender based on the rate it displays, students ought to know how interest is determined, what goes into the price and how the overall cost of borrowing compares.
Accuracy Notice: Interest rates, limits of loans, eligibility and policies of lenders may vary. The lender rate shown online must be confirmed to an individual prior to application. The maximum pricing will be set by the respective lender itself after evaluating the applicant and loan requirement.
Read out: Education Loan for Abroad Studies: Complete 2026 Guide
Education Loan Interest rates 2026: What to compare?
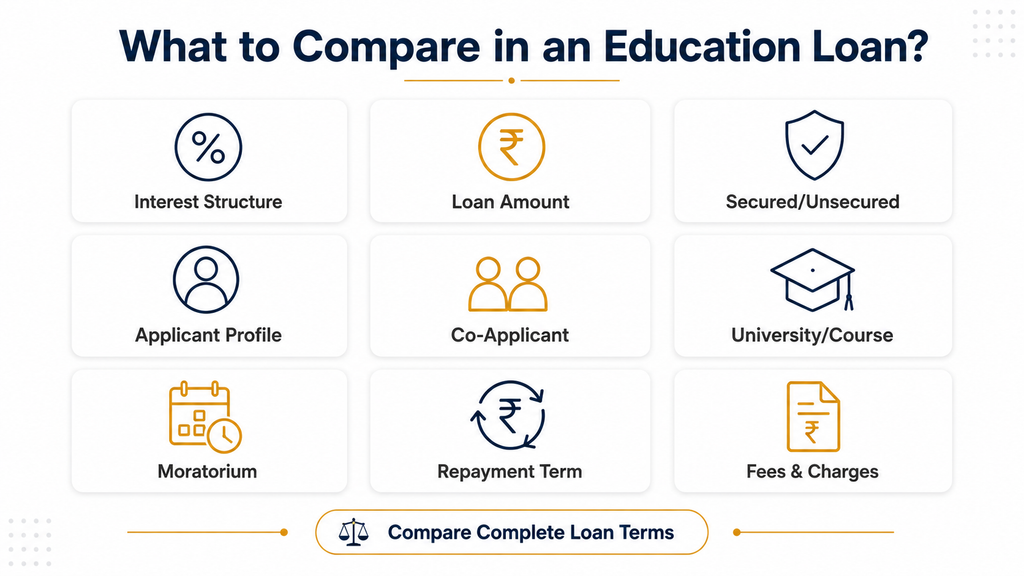
The interest paid to the lender is not the only aspect of financing. The entire structure of the loan should be well compared.
| Factor | Why It Matters. |
| Interest-rate structure | Determines the calculation of the cost of borrowing. |
| Loan amount | Can affect the eligibility of products and the level of risk. |
| Secured/unsecured | Changes security requirements and underwriting |
| Applicant profile | Academics and other profile factors can be an influence in assessment. |
| Co-applicant | Income, credit and liabilities may affect eligibility. |
| University/course | Lenders can consider the institution and programme. |
| Moratorium | Interest can keep on accruing throughout this time. |
| Repayment term | The longer the repayment, the higher the interest to be paid. |
| Fees | Processing and other charges hike the cost of borrowing. |
What it implies to you: The difference between bank and NBFC education loan rates is crucial, but students should compare full eligible offers as opposed to individual percentages.
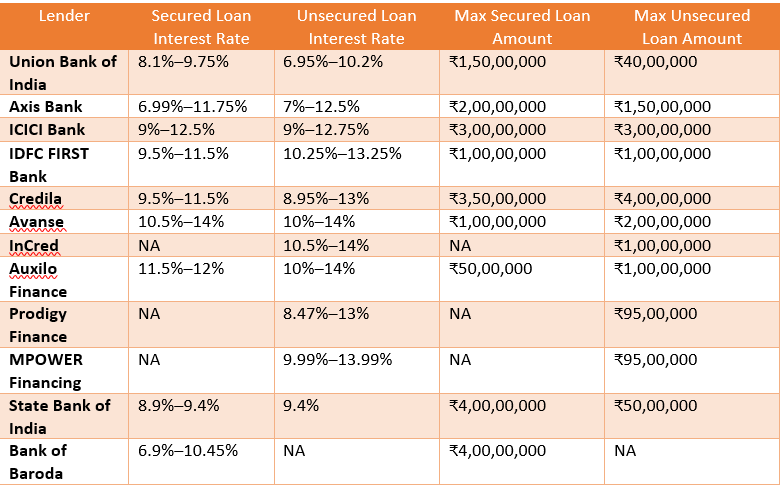
Compare Interest Rates of various Lenders.
When students are researching education loans, they may be faced with significantly different published rates. The comparison material provided in this article covers the banks in the public sector, the banks in the private sector, the NBFCs and international education-finance providers.
The lenders are:
- Axis Bank
- Union Bank of India
- ICICI Bank
- State Bank of India
- IDFC FIRST Bank
- InCred
- Credila
- Bank of Baroda
- Avanse
- MPOWER Financing
- Prodigy Finance
- Auxilo
These types of lenders cannot be taken as synonymous.
- The education loan interest rates 2026 and loan sums will vary between secured and unsecured loans.
- Certain lenders are able to offer both types of loans, whereas some will offer them according to eligibility of the product.
- Union Bank reveals that education loan interest rates to abroad may depend on credit profile, income, amount and tenure of loan.
- The July-September 2025 disclosure of Axis Bank revealed that there were variations in rates depending on factors such as size of loan and place of study.
- Thus, when comparing bank vs NBFC education loans, the rate should be based on the terms of the loan to the applicant, rather than the rates displayed.
Education Loan Interest Rates 2026 Comparison
How do Education Loan Interest Rates Work?
The beginning of understanding education loan interest rates 2026 is the beginning of understanding lender risk assessment.
Interest is simply the cost of borrowing or the cost that will be charged on the outstanding amount of money under the terms of the loan; mathematically, though not all students are charged equally by the lenders.
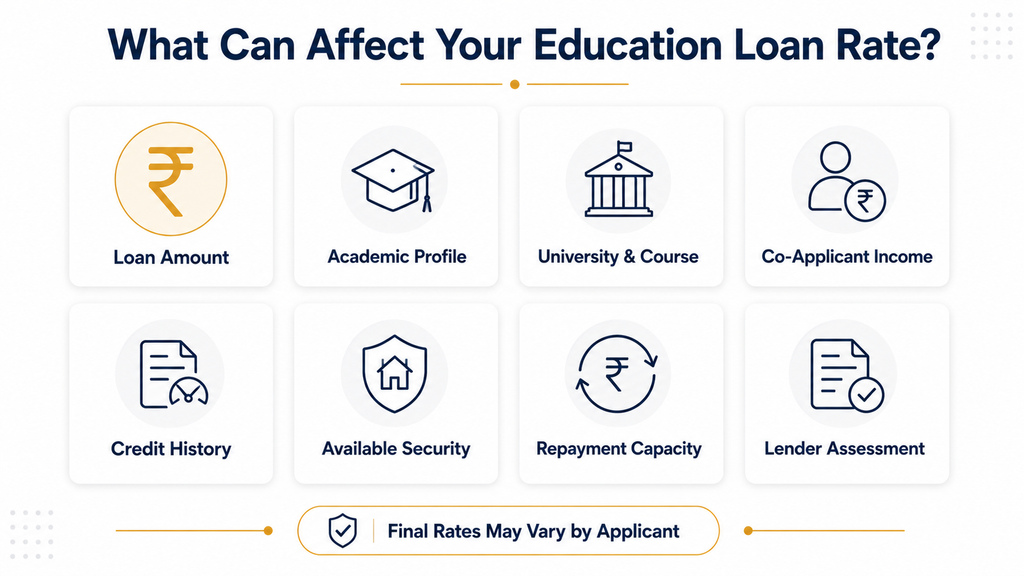
Among key considerations can be:
1. Applicant Profile
The profile of the applicant may impact assessment by the lenders.
Relevant factors may include: depending on the policies of lenders:
- The academic performance has the potential to affect the education loan interest rates 2026 and the general lender evaluation.
- The choice of university and course can have an impact on the rate of interest payable on the education loan in a foreign country.
- Past work experience has the potential to fortify the academic, professional and financial resume of the applicant.
A good academic profile is not a guarantee of a specific interest rate or approval.
2. Co-Applicant Profile
Co-applicant may play a vital role in Indian education-loan underwriting, contingent on the contractual terms of the lenders and products.
- Stability in terms of employment or business.
- Income.
- Repayment capacity.
- Existing loans.
- Credit history.
- Bank statements.
- Current EMIs.
The same may happen with a co-applicant who has substantial current financial obligations, as opposed to an individual who has a similar income but fewer liabilities.
The documentation requirements of Union Bank, such as the income information and bank statements of the appropriate borrowers, co-borrowers or guarantors, are some examples.
3. Loan Amount
The specified amount is especially crucial when addressing the education loan interest rates 2026.
The terms should not be the same for a ₹20 lakh application and a ₹70 lakh application.
The lender will be able to evaluate:
- Security available
- Total financial exposure
- Co-applicant repayment strength
- University and course
- Programme cost
- Product-level loan limits
- Applicant creditworthiness
Under the official education-loan information, Union Bank specifies that the amount of the loans is one of the factors that may affect the interest rate charged.
What that implies to you: Do not inquire, simply, what is the rate of this lender? Enquire, what rate and terms can my required loan amount and profile be?
Type of Loan: Secured vs Unsecured
The education loan interest rates 2026 in foreign countries can also be determined by the mode of financing chosen.
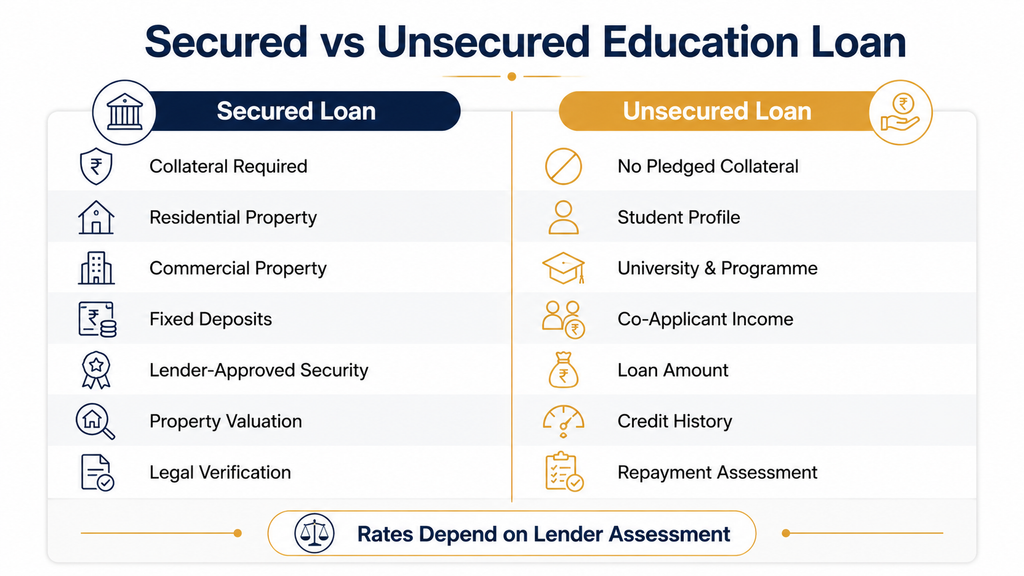
Secured Education Loan
A secured loan is one that has taken collateral that is accepted by the lender.
- Commercial property
- Residential property
- Other lender-approved security
- Fixed deposits
Security has the potential to mitigate some of the credit risk of the lender, which can affect the price and loan eligibility. It would be incorrect to say, however, that all secured loans always have a lower interest rate.
Pledging an asset also requires that students and parents put into consideration property valuation, legal verification, documentation and the implications of this.
Unsecured Education Loan
An unsecured education loan does not involve secured collateral.
The lender can, therefore, put more focus on:
- University and programme
- Student profile.
- Co-applicant income.
- Existing liabilities.
- Repayment assessment.
- Loan amount.
- Credit history.
On the same note, one cannot assume that all unsecured loans are bound to bear a certain higher rate.
Where feasible, in the quest to find the lowest interest rate in education loans, compare the secured products with the unsecured products and likewise the unsecured products with the other unsecured products.
Types of Education Loan Interest Rates
There are two types that students need to know in reviewing the education loan interest rates 2026: floating interest and fixed interest.
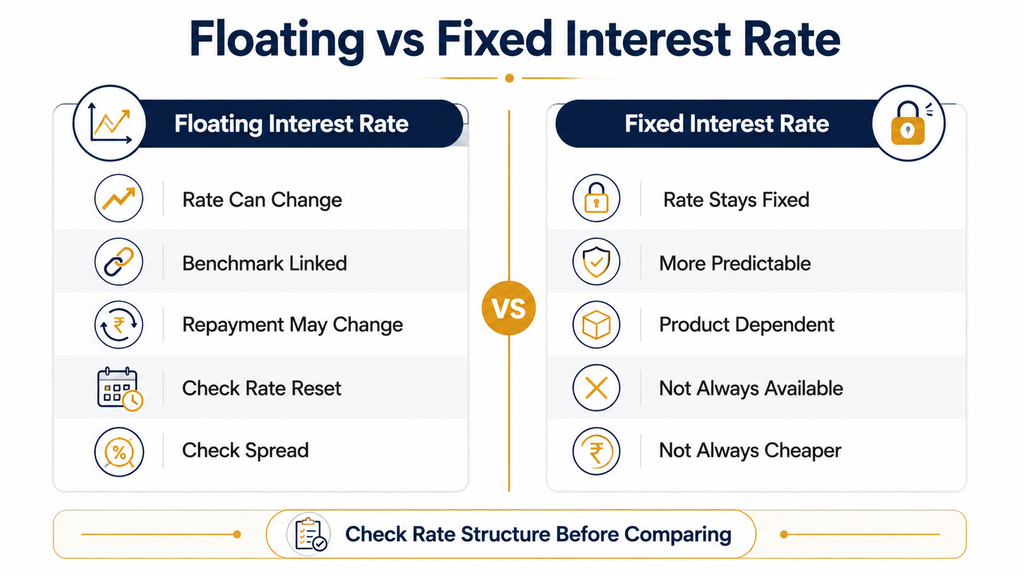
Floating Interest Rate
Depending on the benchmark or lender mechanism, a floating interest rate may rise or fall over the term of the loan.
Key characteristics include:
- The rate applied can vary if the underlying benchmark varies.
- The costs of repayments in future could vary with the original computation of the loans.
- Depending on the terms of lenders, EMI or repayment tenure can vary.
- Borrowers ought to look at benchmark, rate-reset and spread conditions.
Certain education-loan programs have floating rates based on a benchmark. In the case of Union Bank, education-loan products are published by the bank with floating structures based on EBLR.
Loan Tip: Review the relevant benchmark, rate resetting frequency and spread prior to borrowing.
Check out: EMI Calculator
Fixed Interest Rate
Fixed interest rate does not usually vary during the period that the contract is signed. This can help in planning repayments to be more predictable.
However:
- Not all lenders provide fixed-rate education loans.
- The conditions of products may differ among lenders.
- Fixed rates do not necessarily come at a lower price.
- Confirm whether the rate is held constant during the tenure.
The rate structure of the bank vs NBFC education loan comparison should then be considered, and then the offers can be compared.
Calculation of Education Loan Interest?
It helps to compare education loan interest rates 2026 because of understanding interest calculations.
Simple Interest
The simple equation is:
Simple Interest = (Principal x rate x time)/100.
Illustrative Example
Assuming that 5000 is utilised as a learning tool, having an annual simple interest rate of 5 per cent, over a period of a year.
Interest = ₹50,000 × 5 × 1 ÷ 100 = ₹2,500
That simplistic assumption would result in a value of ₹52,500.
It is not an education-loan quote, and does not reflect an up-to-date lender rate.
Real-life education loans might have floating rates, monthly calculations, interest on the moratorium period and other terms of the contract.
Compound Interest
The difference between compound interest and simple interest is that when taking interest on a loan, it may be effective to take interest on the accumulated interest in addition to the loan itself, depending on the terms of the loan.
In the case of education loans, students ought to enquire in particular:
- What is the calculation of interest?
- Is interest paid in the course?
- What becomes of unpaid interest during the moratorium?
- What is the commencement of normal EMI?
- What is the frequency of rate reset?
- What is the impact of the accrued interest on repayment?
It is more prudent to comprehend these details than merely to locate the lowest education loan interest rates 2026 on the internet.
Education Loan Rate Bank vs NBFC Education Loan: The Differences.
A comparison of a bank vs NBFC education loan rate should look at the functionality of the whole product.
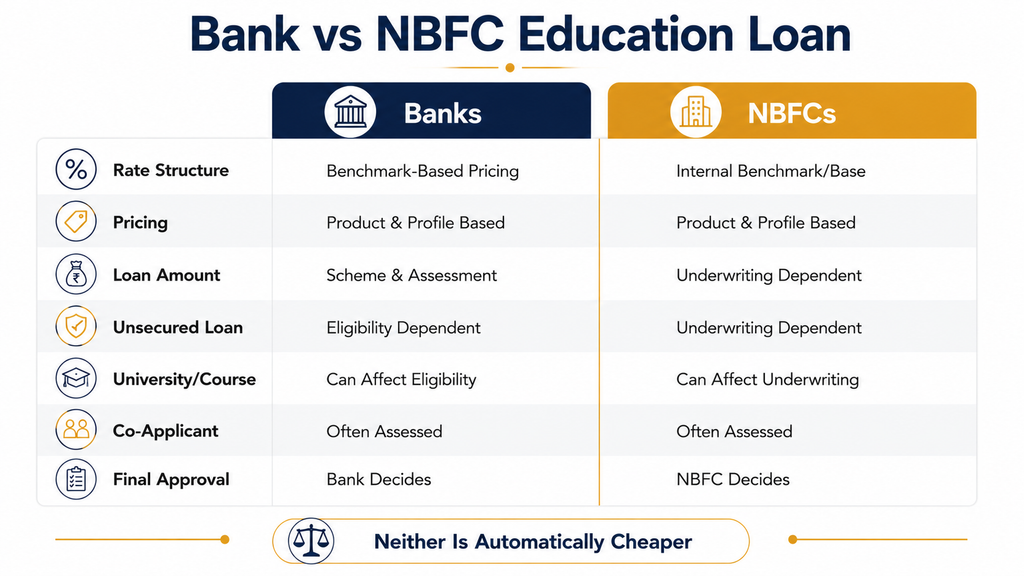
| Comparison Area | NBFCs | Banks |
| Pricing | Product and profile dependent | Product and profile dependent |
| Rate structure | May be internal benchmark/base structures. | May be benchmark-based pricing |
| Unsecured loan | Available to be underwritten. | Available to eligible profiles/products |
| Loan amount | Underwriting dependent. | Scheme and assessment dependent |
| Collateral | Scheme specific | Product/profile specific. |
| University/course | Can affect underwriting. | Can affect eligibility |
| Co-applicant | Often assessed | Often assessed |
| Final approval | NBFC decides. | Bank decides |
| Processing fee | Product specific | Product specific |
| Moratorium | Product specific. | Scheme specific |
The implications of this on you are as follows: Banks are not necessarily cheaper, and NBFCs are not necessarily expensive. Compare the terms that are available on your profile.
The best way to find the lowest education loan interest rate.
Locating the lowest education loan interest rates 2026 can be effective when the likes of loans are being considered.
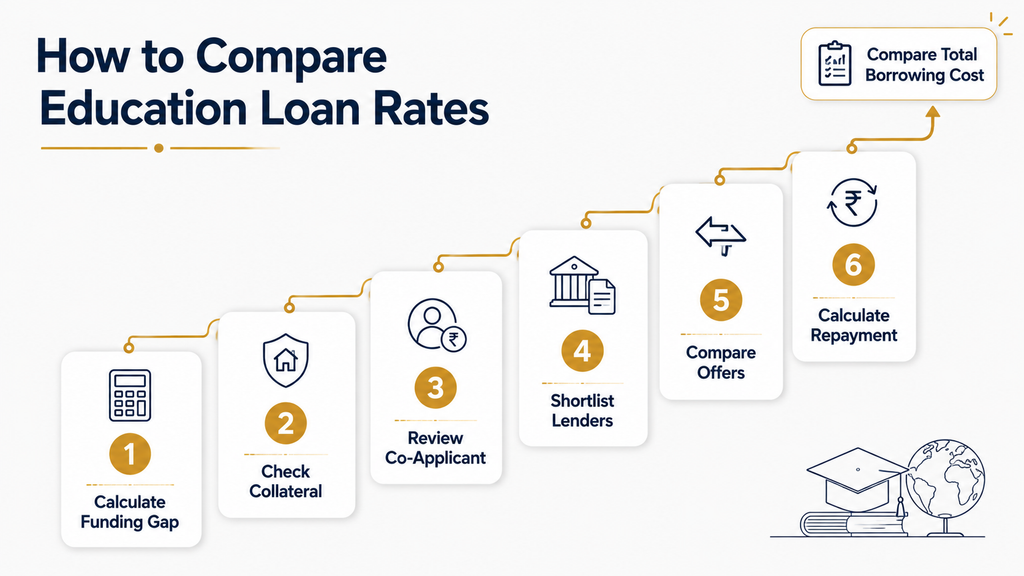
Follow this process:
- Compare education loan interest rates 2026 by calculating your funding difference by adding tuition, living, travel and other allowable expenses.
- Determine the collateral that is available to determine which financing option between secured and unsecured is most suitable to your borrowing needs.
- Examine the co-applicant by verifying the income, EMIs and credit history in assessing the interest rate of the education loan in a foreign country.
- When you apply, shortlist the eligible lenders which fund your university, course, destination and amount of loan required.
- Ask for similar offers to compare the bank’s NBFC education loan rate with similar amounts and terms of repayment.
- To get the lowest interest rate on an education loan, calculate the total repayment, taking into account the interest, fees and costs on the moratorium.
A lender with the lowest interest rate on an education loan is not always the one that will give you the lowest total cost of borrowing in your case.
Comparison of Interest Rate Should Not be limited to the interest rate.
Education-loan decision is not a one-shot affair as it is composed of the bank vs NBFC education loan rate.
| Check | Why It Matters |
| Applicant pricing | Displays applicant-specific pricing. |
| Benchmark/spread | Describes possible changes in floating rates. |
| Processing fee | Is added to the cost of borrowing. |
| Secures | Establishes security of action. |
| Margin | Establishes family contribution. |
| Moratorium | Can include accruing interest. |
| Tenure | EMI and overall repayment are affected. |
| Prepayment | Prevents the flexibility of early repayment. |
| Costs incurred | Establishes the real funds at hand. |
| Disbursement | Impacts the timing of approved money to be availed |
.
Repayment Tip: Shown percentage should not be more favourable than actually reasonably suitable repayment, security or disbursement terms.
Mistakes to avoid when comparing the rates of education loans.
Students need not make some of the most prevalent mistakes in the process of comparing lenders because these errors may affect the borrowing rates or make students take the wrong decisions with regard to the loans.
- Comparing the advertised education loan interest rates 2026 without referring to the final rate charged by the lender.
- Disregarding loan amount when checking the education loan interest rate abroad.
- Ignoring co-applicant income and credit report when comparing education loan interest rates 2026.
- Drawing a comparison between secured and unsecured loans without taking into account the various terms and requirements.
- A comparison of the bank and the NBFC education loan rate without any consideration of fees and repayment terms.
- The floating-rate changes, which are likely to impact the cost of borrowing at the time of repayment, will be ignored.
- Supposing that the moratorium period is an automatic interest-free one.
- Selecting the cheapest interest rate of the education loan without assessing its overall cost.
How Foreign Edu Loans Can Help
Students who compare the education loan interest rates 2026 might have to apply to banks, NBFCs and international education-finance providers instead of going to a single institution.
Foreign Edu Loans can assist students in finding appropriate education-loan options on the basis of:
- Study destination
- University and course
- Secured or unsecured requirement
- Required loan amount
- Co-applicant profile
- Available collateral
- Relevant lender eligibility
Lender comparison, coordination of documents and application can also be taken care of by Foreign Edu Loans. It is an education-loan facilitation and advisory platform and not the institution which ends up making the final credit decision.
The interest rate to be charged, the loan amount, approval, and final terms are all subject to current eligibility and underwriting policies of the respective lender.
Check Your Eligibility for an Education Loan.
FAQs
How much are the education loan interest rates 2026 to study abroad?
Education loan interest rates 2026 are offered at varying rates depending on the lender, loan amount, collateral, applicant profile, the university and course, among other lending requirements.
What is the interest rate of an education loan to study overseas?
The education loan interest rates 2026 in foreign countries depends on the lender and the applicant. Pricing can be affected by the amount of loan, collateral, finances and credit profile of the co-applicant, etc.
Are loans offered by banks cheaper than NBFC?
Not always. The interest, fees, collateral, moratorium and repayment conditions should be included in the comparison of a bank vs NBFC education loan rate.
Is there any impact of the amount of education loan on the interest rate?
It can. Security, credit profile, income, university, course and repayment capacity might be some of the factors that lenders may take into consideration when deciding on the amount of loan requested.
What is the lowest interest on education loans?
Compare best offers of various lenders. The interest rate of the lowest education loan needs to be evaluated with fees, term, moratorium and total repayment.
What does floating education-loan interest rate mean?
The floating rate may go up or down when its applicable benchmark or method of pricing by the lender varies over the loan tenure.
Conclusion
Learning about the education loan interest rates 2026 involves more than just comparing ads on lenders. The final rate that can be used depends on the value of the loan, the background of the applicant and co-applicant, collateral, college, course, type of loan, market-based rates and lender underwriting.
Students are to know both fixed and floating rates, the amount of their real funding need and similar offers that are available with equivalent conditions. There is no way the lowest interest rate of education loans can be viewed as disconnected from the fees, moratorium terms, repayment period, collateral liability and overall repayment.
Make sure that the existing rates are checked with the particular lender prior to making a choice since published rates and lending policies are subject to change.
Check Your Education Loan Eligibility to find out what could be a good financing option to meet your study-abroad profile and funding need.