The decision on whether to use a public bank vs private bank vs NBFC education loan is a critical financing option given to Indian students intending overseas studies. An advertised interest rate/maximum loan amount should not be the only basis of a public bank vs private bank vs NBFC education loan comparison. Every lender has their guidelines regarding eligibility, collateral, co-applicant evaluation, university and course, destination, processing and repayment.
The most suitable education loan lender is based upon your actual funding requirement profile. Similarly, an NBFC vs bank education loan comparison must look into the total borrowing structure. Only the lenders who are really appropriate to your university, course, the loan amount and financial situation should be compared by students who want to get an education loan abroad.
Note of Accuracy: Interest rates, loan limits, fees, collateral requirements and lending policies can vary. After evaluation, final approval and applicable terms are decided upon by the respective lender.
Read out: Education Loan for Abroad Studies: Complete 2026 Guide
Public Bank Vs Private Bank Vs NBFC Education Loan: Rapid Comparison.
Comparing education loans provided by public bank vs private bank vs NBFC education loan gets even more evident when all categories of lenders are judged on the same parameters.
| Factor | Bank Private-Sector | Public-Sector | NBFC |
| Eligibility | Product/profile specific | Scheme specific | Underwriting specific. |
| Examples | Axis Bank, ICICI Bank, IDFC FIRST Bank | BOB, PNB, SBI, Union Bank | InCred, Avanse, Credila, Auxilo |
| Collateral | Depends on product | Depends on scheme | Depends on product/profile. |
| Loans amount | Dependent on product and profile | Dependent on scheme and profile | Dependent on profile and product |
| Final approval | Bank decides | Bank decides | NBFC decides |
| Unsecured option | To be available. | To be available | To be available to be available. |
| University/course | Can influence eligibility | Can influence eligibility | Can impact underwriting |
| Co-applicant | Commonly assessed | Commonly assessed | Commonly assessed |
| Moratorium | Product specific | Scheme specific | Product-specific. |
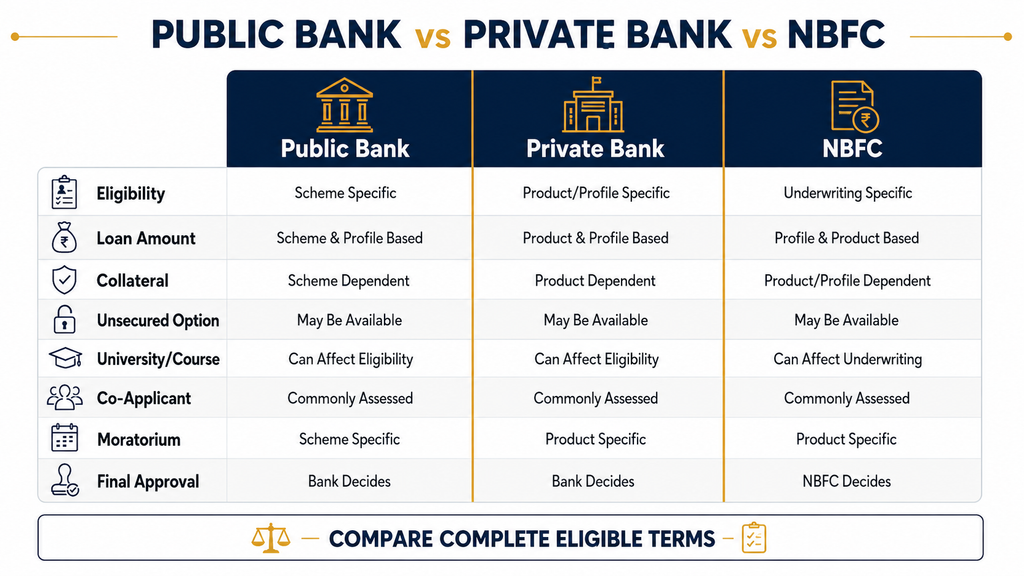
The above lender examples are in accordance with the given Foreign Edu Loans categorisation. Banks in the public sector are State Bank of India, Bank of Baroda, PNB and Union Bank, and ICICI Bank, Axis Bank and IDFC FIRST Bank are included in the category of private sector banks. Credila, Avanse, Auxilo and InCred are education finance NBFCs.
Its implication on your part: This does not necessarily imply that a public bank vs private bank vs NBFC education loan is the best lender. Compare eligibility, overall cost, collateral, charges, moratorium, terms of tenure and disbursement.
What Is a Public-Sector Bank Education Loan?
Banking institutions that are frequently utilised in financing overseas education and banks that are commonly regarded as being part of the public sector are SBI, Bank of Baroda, Punjab National Bank, Union Bank of India, Canara Bank and Bank of Maharashtra. The provided Foreign Edu Loans model suggests an evaluation of the availability of such lenders based on their rate, collateral, margin, repayment period and processing conditions.
In comparing a public bank vs private bank vs NBFC education loan, the public banks might well apply to students who qualify under a specific education loans program and to those who are comfortable with documentation and security provisions therein.
Public banks can be interesting in cases where:
- Your course and university are covered by the relevant education-loan scheme.
- The amount of your loan request meets the current product and eligibility requirements of the lender.
- Where the loan scheme chosen entails the security to be approved by the lender, acceptable collateral is available.
- Your co-applicant possesses appropriate income, credit profile and financial documentation criteria.
- The payment plan may suit your anticipated economic ability upon finishing your studies abroad.
The idea of public ownership is not that all banks that belong to the public sector will provide equal conditions. Students who enquire about which is the best bank to take an education loan in a foreign country must not just be told that this or that particular scheme is considered by everybody.
What is a Private Bank Education Loan?
ICICI Bank, Axis Bank and IDFC FIRST Bank are some of the private-sector banks within the provided lender framework. Their education-loan products can vary in the size of the loan, collateral needs, unsecured lending, processing, university eligibility, and evaluation of the applicant.
The decision on the public bank vs private bank vs NBFC education loan should thus consider a separate category of the private banks and not presume that their products resemble products of the schemes in the public sector.
- They may be compared in the case of private banks when:
- The lender has eligibility requirements for an education loan that your university and programme meet.
- You require funded or guaranteed collateral-free financing to fund your foreign education costs.
- In the view of the lender, your profiles of applicant and co-applicant fit the intake necessary for the required underwriting rules.
- The method of processing by the lender fits the admission, payment of fees or visa-implicated financial schedule.
- Its loan limit is as much as your full tuition and study-abroad scholarship.
A more digital or faster process does not necessarily result in a better private bank. Total cost of borrowing and appropriate terms should, still, serve as a determinant in the final decision.
What is an NBFC Education Loan?
An NBFC is any non-banking financial institution that is involved in financial operations like lending. As explained in RBI materials, an NBFC refers to a company that conducts financial business (lending or financing) as opposed to a traditional bank.
NBFCs providing education finance that are based on the provided company framework are: Creditsila, Auxilo, Avanse and inCred. These lenders can evaluate the student, university, course, co-applicant, loan amount and credit profile and security provisions based on their underwriting policy.
To decide between an NBFC and bank education loan, students need to compare:
- Education-loan amount and product availability required.
- Insured or uninsured funding to eligible applicants.
- University, programme and study-destination qualification.
- Co-applicants’ income and current financial obligations.
- Past history and general repayment ability.
- Calculation of fees and other charges that lenders impose.
- Moratorium and post-study repayment terms.
An NBFC can not necessarily be characterised as hassle-free, quicker or more costly. Such results will be based on the artist, borrower and product.
Comparison of public bank vs private bank vs NBFC education loan
An education loan full-time comparison in terms of a meaningful comparison between a public bank vs private bank vs NBFC education loan should go beyond the naming of lenders.
| Comparison Area | Private Bank | Public Bank | NBFC |
| Benchmark structure | Product dependent | Can be benchmark linked | Lender/product dependent. |
| Pricing | Product/profile specific | Scheme/profile specific | Product/profile specific |
| Loan amount | Eligibility dependent | Scheme dependent | Underwriting dependent. |
| Unsecured finance | Dependence on eligibility | Eligibility dependent | Dependence on underwriting. |
| Co-applicant | Commonly relevant | Commonly relevant | Commonly relevant |
| Collateral | Product dependent | Scheme dependent | Product/profile dependent |
| Processing fee | Product specific | scheme specific | Product specific. |
| Prepayment | Check current terms | Check current terms | Check current terms |
| Moratorium | Product specific | Scheme specific | Product specific |
| Pay out | Bank procedure | Bank procedure | NBFC procedure |
What it entails to you: The category of the lender cannot (alone) determine the most convenient choice. The most appropriate lender for securing an education loan is one whose requirements are eligible and able to pay well within your financial means.
The Impact of Interest Rates and the amount of the loan on the decision.
Interest rates are very much to be considered in a public bank vs private bank vs NBFC education loan however, there is no single common interest rate as applied to any type of lender.
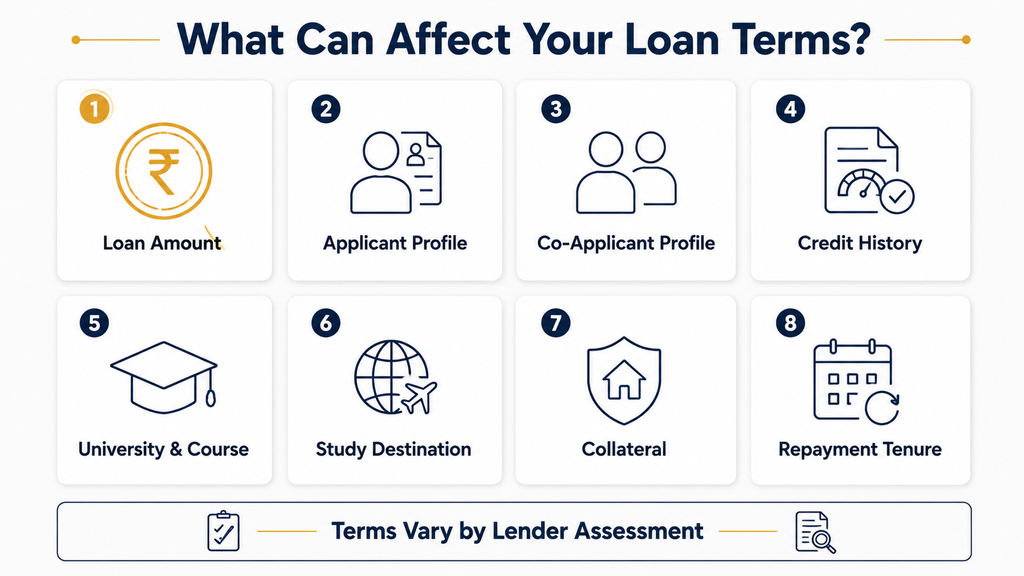
The applicable pricing can vary according to:
- Requested loan and the product.
- Collateralised or non-collateralised education loan.
- Co-applicants and applicants’ financial profile.
- Past credit history and current financial obligations.
- College, course and study location.
- Tenure and policy of present lenders.
- Relevant benchmark or internal pricing structure.
The amount of a loan demanded is of great significance. An Indian student who wants a loan of 20 lakh and a fellow student who needs a loan of 70 lakh might be offered varying products, security structures or terms with the same bank.
This is the reason why an NBFC vs bank education loan comparison should be in terms of approximately the same loan amount and secured or unsecured structure.
Rate Disclaimer: Depending on loan amount, the profile of the applicant, collateral, product structure and existing lender policies, interest rates might change.
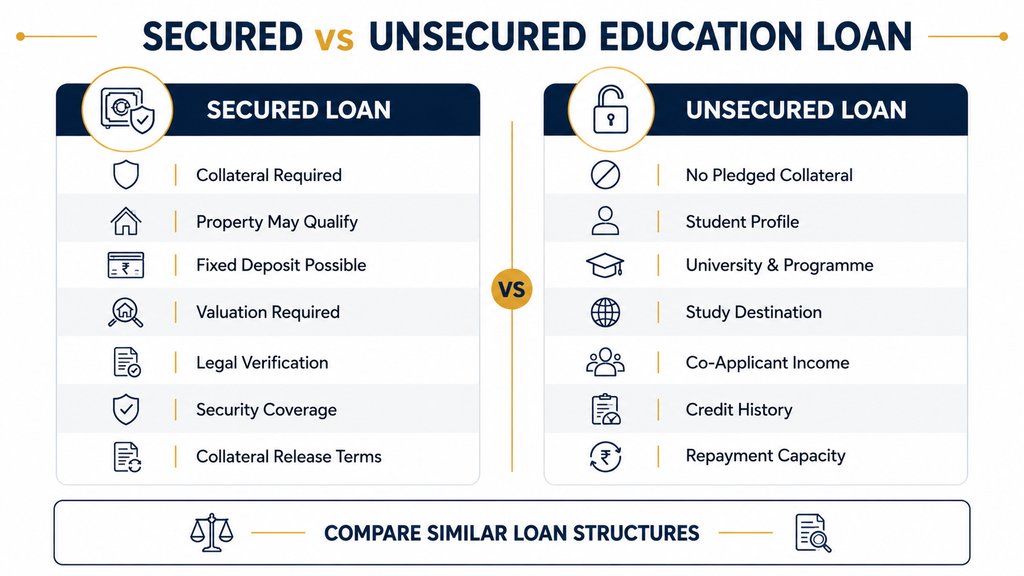
Secured vs Unsecured Financing
Public bank vs private bank vs NBFC education loan decision also hinges on whether or not you require secured financing or unsecured financing.
Secured Education Loan
An education loan that is secured mandates collateral approved by the lenders. Depending on the lender’s policies, this can be residential or commercial property, which is secured or eligible to be secured by a fixed deposit or other acceptable security.
Borrowers should check:
- Lender valuation requirements.
- Title deeds and ownership of property.
- Legal verification requirements.
- Existing mortgage/charges.
- Security coverage conditions.
- Collateral release requirements.
Security can affect eligibility and pricing, and a secured loan cannot necessarily be said to be cheaper.
Unsecured Education Loan
An unsecured education loan does not entail pledged collateral. The lender can place more stress on:
- University and programme
- Student profile and academic
- Study destination.
- Co-applicant income
- Required loan amount.
- Credit history.
- Repayment capacity.
- Existing liabilities.
In making a comparison between an NBFC vs bank education loan, students must, where feasible, compare secured offers with other secured offers and unsecured products with other unsecured products.
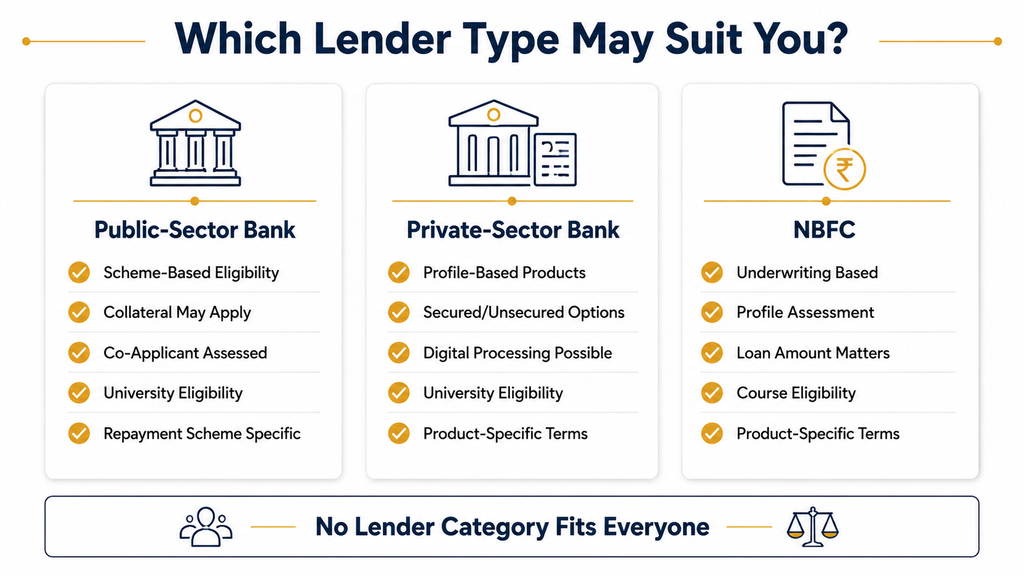
Lender Type May Suit Different Student Profiles: Public bank vs private bank vs NBFC education loan
No single answer exists to the question of what bank is best when taking an education loan to go abroad, as the various profiles can fit in various products.
| Student Situation | Worth exploring the category of Lenders. |
| Appropriate public-bank scheme present | Public sector banks. |
| Strong eligibility for private-bank product | Private-sector banks |
| Profile-based education financing needed | NBFCs and eligible banks |
| Secured products | Compare security products. |
| No collateral found | Compare eligible unsecured products. |
| Higher loan requirement | Compare limit and terms with lenders. |
| Good co-applicant profile | Compare all qualified lender types. |
| University/course limits | Only the lenders who cover the programme are listed on the shortlist. |
This table does not mean that a certain category will grant the application. It merely assists students in making decisions on where to start complying.
How to Select a good Education-Loan Lender?
The decision of a public bank vs private bank vs NBFC education loan is simplified when students do the same process for all lenders.
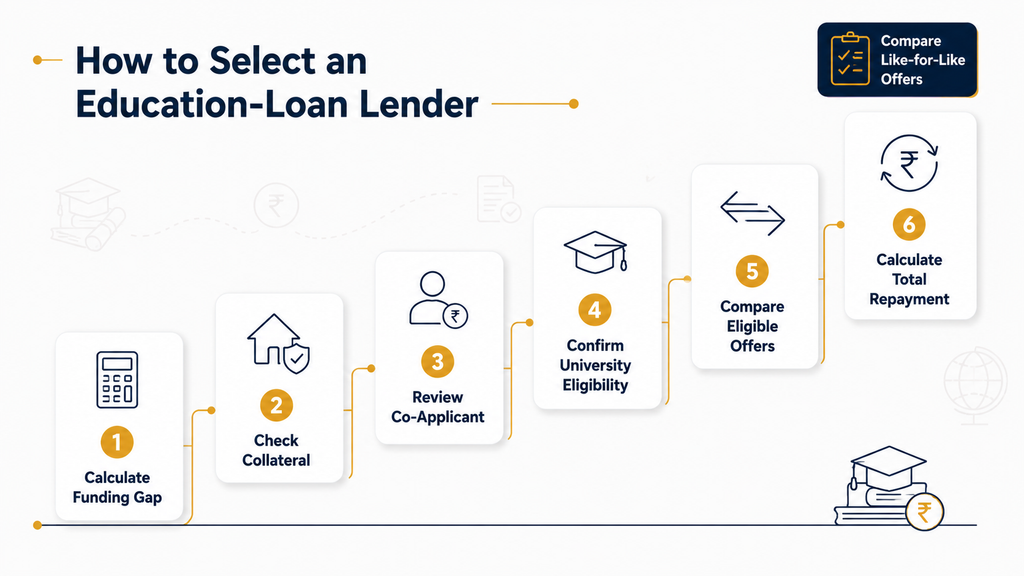
- Make up your funding gap by adding your tuition, living, travel and other allowable education costs.
- The availability of check collateral prior to making the decision of either secured or non-secured financing makes it more practical.
- Check the co-applicant by scrutinising the income, current EMIs, credit history and financial records.
- Check university eligibility as lender coverage may be based on university, course and location.
- Compare best offers to determine the best lender to your actual profile in terms of education loans.
- Divide the total repayment taking into account the interest, fees, moratorium implications and repayment tenure.
- Check disbursement regulations to make sure that the cash can be released on the basis of university payment regulations.
- Do not choose the maximum authorised sum just because it exists. Take a loan in line with your actual need to finance and ability to repay.
The public bank vs private bank vs NBFC education loan comparison information provided also suggests verifying the rate structure, amount of loan, secured or unsecured availability of facilities, collateral, margin, processing costs, instalment, repayment duration, co-applying, university qualification, prepayment and disbursement.
What Are the Additional Costs to Compare?
This decision regarding a public bank vs private bank vs NBFC education loan should feature the entire cost structure.
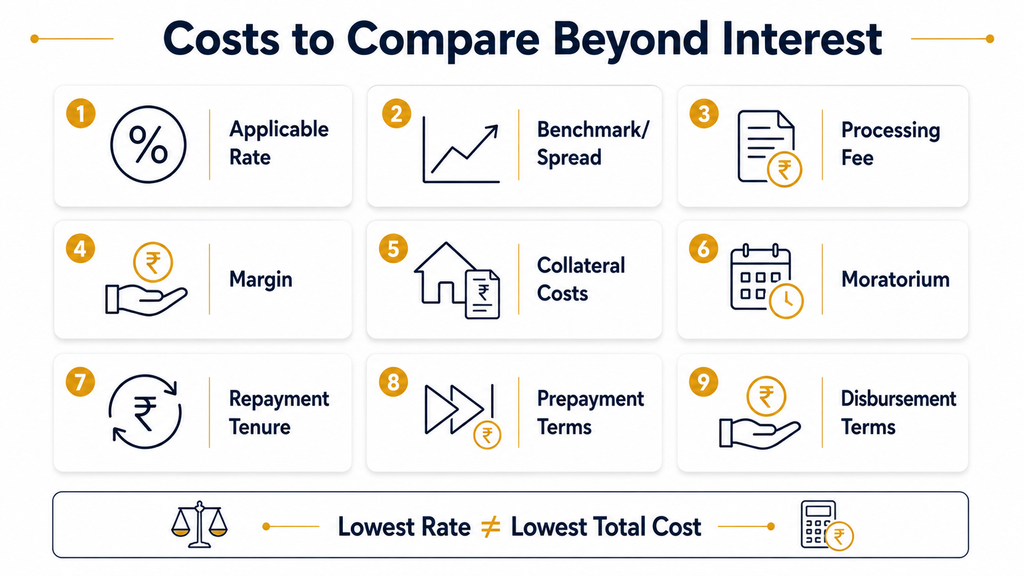
| Cost or Term | Check what. |
| Relevant rate | Real offered rate and structure. |
| Benchmark/spread | Impact floating pricing can have. |
| Processing fee | Membership fee set by the current lender. |
| Margin | Review family contribution requirement. |
| Collateral expenses | Valuation/legal expenses (where required). |
| Moratorium | Would interest accrue or not? |
| Tenure | EMI and overall repayment effect. |
| Prepayment | Relevant charges or restrictions. |
| Disbursement | Terms of advancement of the funds. |
The lowest total cost of borrowing may not necessarily be the lowest rate being advertised by a lender. It is due to this that all of the public bank vs private bank vs NBFC education loan offers should be matched more on a like-for-like basis.
Check out: EMI Calculator
Major Mistakes When Comparing Lenders.
Lending students comparing a public bank vs private bank vs NBFC education loan are not to make the following errors:
- Making comparisons of advertised rates even when the end lender-offered terms are not checked.
- Not considering the loan amount when comparing product qualification and cost of borrowing.
- Contrasting secured and unsecured products as if their structure is the same.
- Deciding on NBFC vs bank education loan without verifying the fee and conditions of loan repayment.
- Overlooking co-applicant income, credit history and existing financial liabilities.
- Has all lenders funded all universities, courses, countries or the amount of loans necessary?
- Considering the moratorium as automatically zero-interest without evaluating conditions lender-specifically.
- Selecting a lender without checking relevant prepayment and disbursement requirements.
How Can Foreign Edu Loans Help?
When comparing a public bank vs private bank vs NBFC education loan, students can make comparisons; they may have to consider multiple categories of lenders before identifying something that fits their profile.
Foreign Edu Loans: Students are able to explore relevant education-loan options based on:
- Study destination.
- University and course.
- Safe or taking risk requirement.
- Required loan amount.
- Available collateral.
- Relevant lender eligibility.
- Co-applicant profile.
According to the company documents, Foreign Edu Loans operates in public bank vs private bank vs NBFC education loan/international education lenders to assist competent students in exploring funding opportunities based on their profiles. This does not imply that all the lenders will make offers to all students.
An educational-loan facilitation and advice platform, it is not the outfit that provides the final credit approval. Approval, pricing, authorised amount and final terms are all under the discretion of both the respective lender’s underwriting policies.
Determine Your Eligibility for Education Loans.
FAQs
Who should be the best lender (public bank vs private bank vs NBFC education loan) when borrowing an abroad education loan?
The question of which bank is the best to fund an education loan abroad has no universal answer. Compare qualified lenders based on loan amount, university, collateral, co-applicant profile, fees and repayment terms.
Are NBFCs more advantageous than banks for education loans?
Not automatically. Before deciding on a lending institution, compare the eligibility, total cost of borrowing, security, moratorium, tenure and disbursement terms.
Is it possible to get an education loan without any collateral?
There are lenders that provide unsecured products that are eligible. The lender, the profile of the student, the university, the course and co-applicants determine whether one can get a loan and the loan amount lent.
Does the amount of the loan have an impact on the choice of the lender?
Yes. The amount requested may impact the product eligibility and security requirements, pricing evaluation and lenders who fit your profile.
What type of lender tends to be quicker in processing loans?
The lender, product, documentation, credit evaluation and collateral requirements also vary in terms of processing time. The same category may not necessarily handle applications at a better speed.
What are the comparison points of a lender in education loans?
Compare rate structure, loan amount, collateral, fees, margin, moratorium, tenure, prepayment, university eligibility and total repayment.
Conclusion
When it comes to an public bank vs private bank vs NBFC education loan, there is no automatic winner. The appropriateness of all three types of public bank vs private bank vs NBFC education loan might depend on the amount of required loan, university, course, collateral, the strength of co-applicant and his or her ability to repay the loan.
Actual eligible offers as opposed to generic rankings are what students who seek to know which bank to visit in case they are seeking to get an education loan abroad need to use. Interest structure, fees, security, moratorium, tenure and disbursement should be looked at in conjunction during a bank-and-NBFC examination.
The most suitable lender of an education loan is the one whose terms are able to provide you with the required facilities in financing the project as well as repaying the loan. Before applying to any lender, ensure that you have verified their lender policies and do not assume any of the advertised rates, amount or time taken to be guaranteed.
Pingback: The Real Cost of Studying MBBS Abroad — And How to Fund It with an Education Loan for Medical Studies