For Indian students and parents deciding whether loan-linked insurance is useful protection or an unnecessary addition to an overseas education loan.
Education loan insurance can be useful when a large outstanding loan could otherwise fall on a family or co-borrower after a covered event. But it should not be purchased automatically. First check whether your lender’s exact scheme requires life cover. Then check whether the protection justifies the premium.
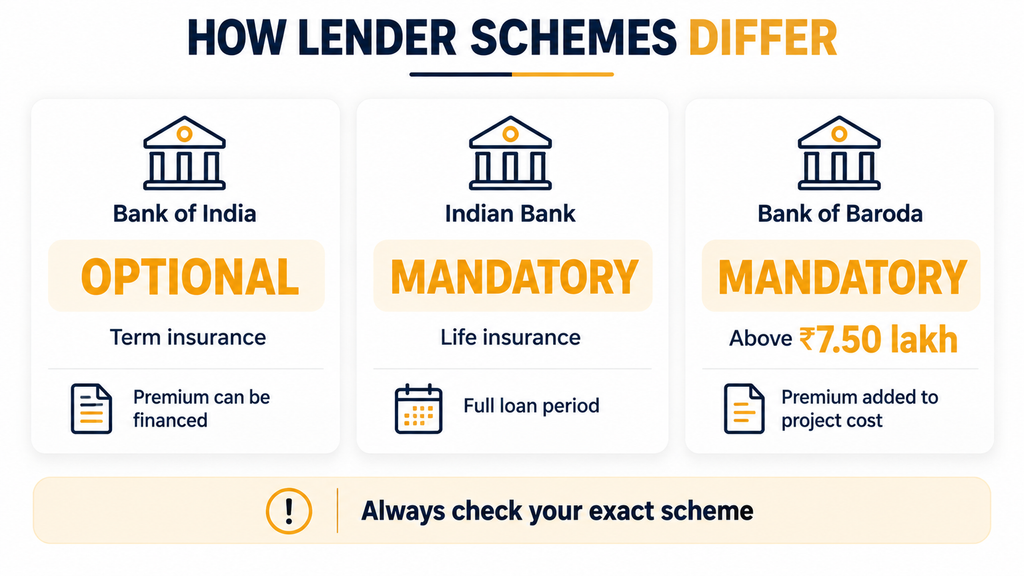
Official lender pages show why there is no universal answer. Bank of India describes term cover under its overseas education loan as optional, while Indian Bank and Bank of Baroda impose life-cover requirements under specified schemes or conditions. The decision depends on the lender, policy and existing cover.
Education Loan Insurance at a Glance
| Question | What official sources show |
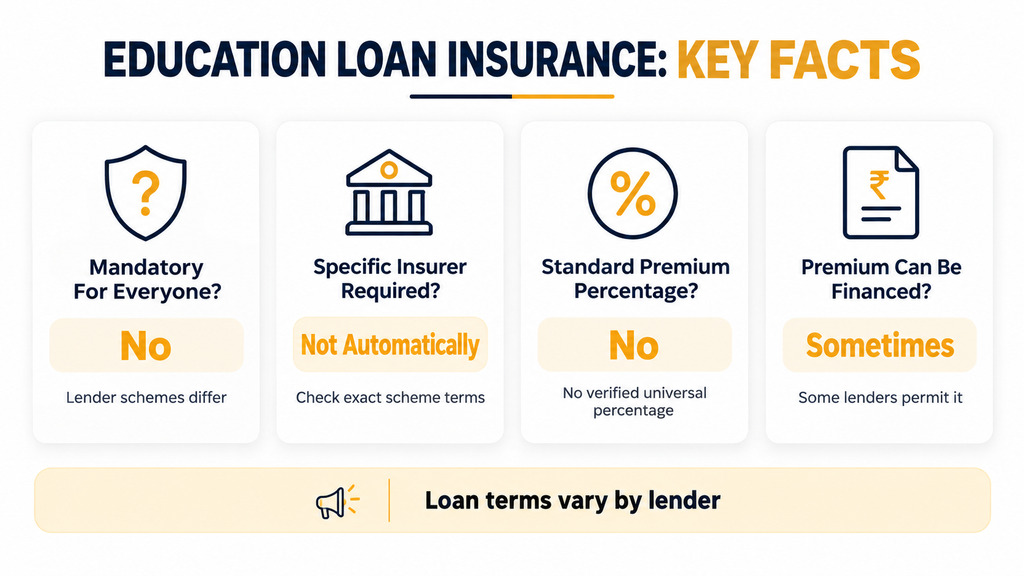
| Is it mandatory for every borrower? | No. Lender schemes differ. |
| Can a bank force one insurer’s product? | RBI restricts banks from forcing customers to choose a specific insurer or linking the insurance sale to a banking product. |
| Is there one standard premium percentage? | No verified universal percentage was found in the official products checked. |
| Can the premium be financed? | Some lenders expressly permit this. |
| Does every plan cover disability or critical illness? | No. Benefits depend on the policy and option selected. |
| Does early closure guarantee a full refund? | No. Treatment is policy-specific. |
What Is Education Loan Insurance?
For this guide, education loan insurance means credit-life or loan-protection cover linked to an education-loan liability. It is different from student health insurance or travel insurance.
LIC’s Group Credit Life Insurance expressly includes education-loan borrowers and provides death cover. Its structure can be level, decreasing or designed around a moratorium.
PNB MetLife’s Complete Loan Protection Plan offers multiple benefit options. Depending on the option, benefits can include death, terminal illness, accidental events, specified critical illness or accidental total permanent disability. It also provides level and reducing cover choices.
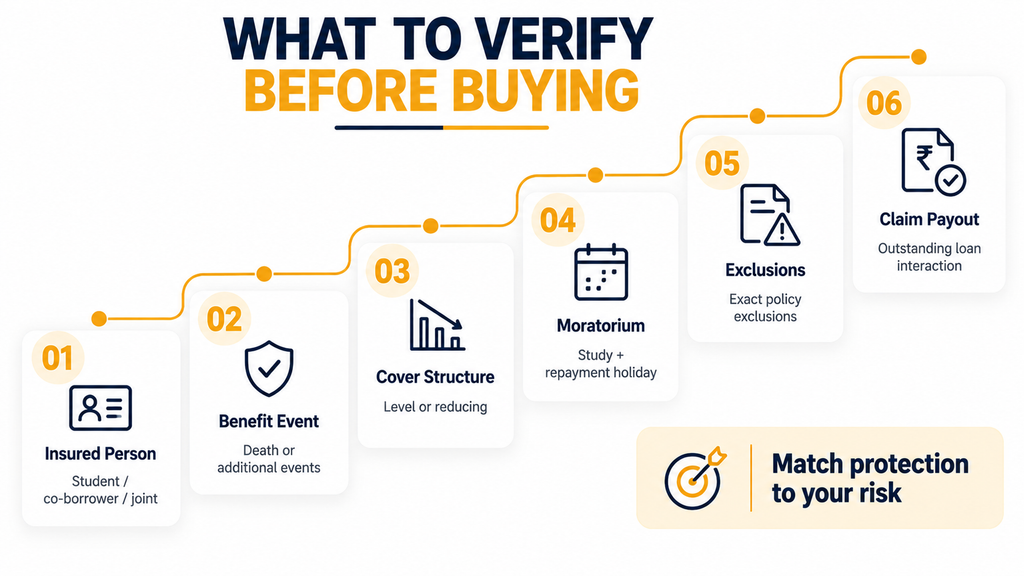
Before buying, check:
- Who is insured: Student, co-borrower or joint lives.
- What triggers a claim: Death only or additional specified events.
- How cover changes: Level or reducing.
- What is excluded: Read the actual policy wording.
- How long cover lasts: Include the moratorium where applicable.
The product name alone does not tell you whether the policy is suitable.
Check out: Co-Applicant in an Education Loan — Who Can Be One & Why It Matters
Is Education Loan Insurance Mandatory in India?
If you are asking “is loan insurance mandatory?”, the accurate answer is: it depends on the lender and scheme.
The Education Loan Insurance FAQ says the IBA Model Education Loan Scheme 2022 provides broad guidelines to Scheduled Commercial Banks and implementing banks have discretion to make changes. Current lender pages confirm this.
How Current Lender Schemes Differ
| Lender and scheme | Insurance position | Premium financing |
| Bank of India Star Education Loan for Studies Abroad | Term insurance is described as optional | Premium can be included as an item of finance. |
| Indian Bank IB Education Loan (IBA) | Life insurance is mandatory for the sanctioned loan limit for the full loan period | Premium may be eligible for finance. |
| Bank of Baroda Baroda Scholar | Group credit life cover is mandatory when the loan exceeds ₹7.50 lakh | Premium may be added to project cost. |
So, is loan insurance mandatory? Never answer without naming the lender and product.
Indian Bank says another policy may be used as desired by the student borrower. Bank of Baroda also allows a term-insurance plan from an IRDAI-approved insurer as an alternative. Mandatory life cover does not always mean buying one particular policy.
Can a Bank Force You to Buy a Particular Insurance Policy?
The current RBI Commercial Banks Undertaking of Financial Services Directions, 2025 say banks undertaking insurance corporate agency business must not use restrictive practices to force customers to choose products from a specific insurance company or link the sale of that insurance product to a banking product.
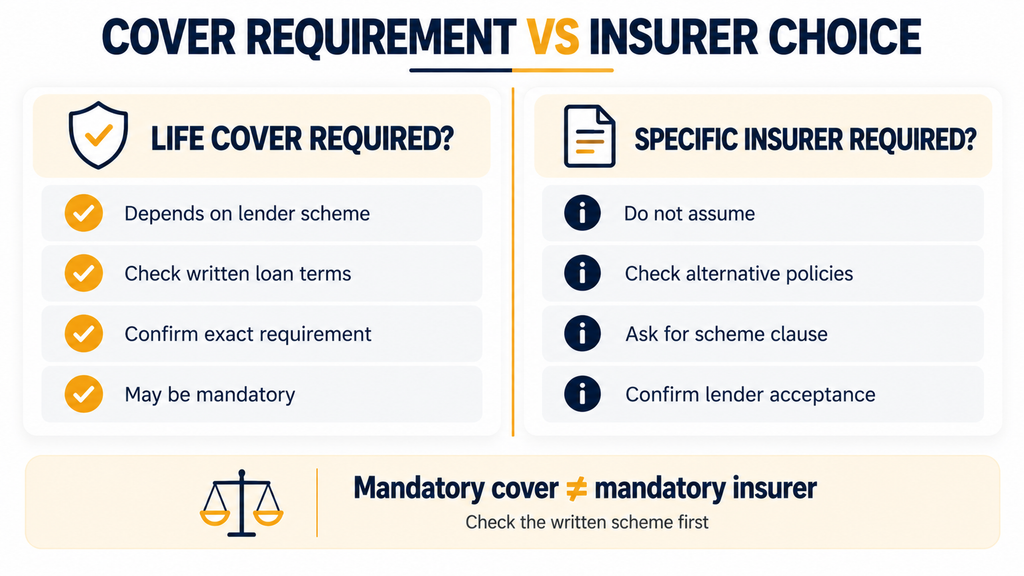
If a branch says one policy is compulsory, ask three questions:
- Where is the insurance requirement written in the education-loan scheme?
- Is life cover required, or is this exact insurer’s product required?
- Can an eligible alternative term policy satisfy the requirement?
Do not rely only on a verbal statement when a significant premium is involved.
What Does Education Loan Insurance Cover?
Coverage is product-specific. Loan protection insurance India products should not be treated as identical.
LIC’s cited Group Credit Life product provides death cover. PNB MetLife offers options that can include terminal illness, accidental total permanent disability or specified critical illness.
What to Verify Before Buying
| Feature | What to check | Why it matters |
| Insured person | Student, co-borrower or joint lives | Identifies whose covered event can trigger a benefit |
| Benefit event | Death only or additional events | Prevents assuming protection that is not included |
| Cover structure | Level or reducing | Shows whether the insured amount changes |
| Moratorium | Cover during study and repayment holiday | Matters while the loan remains outstanding |
| Exclusions | Exact policy exclusions | Shows when a claim may not be payable |
| Claim payout | How benefits interact with the outstanding loan | Shows how the liability is protected |
Value comes from matching the policy to the risk.
How Much Does Education Loan Insurance Cost?
There is no verified universal percentage that can responsibly be presented as the standard education loan insurance cost.
The product information of LIC indicates that the premium structure may require factors based on the loan amount, interest rate, moratorium period and cover structure. According to PNB MetLife, the amount of premium depends on the preferred sum assured, and differs based on the choice of option.
Rather than general percentage, request a written quote for the amount:
- Total premium payable
- Applicable taxes
- Sum assured
- Policy term
- Premium-payment structure
- Level or reducing cover
- Insured person or persons
- Major exclusions
- Early-closure treatment
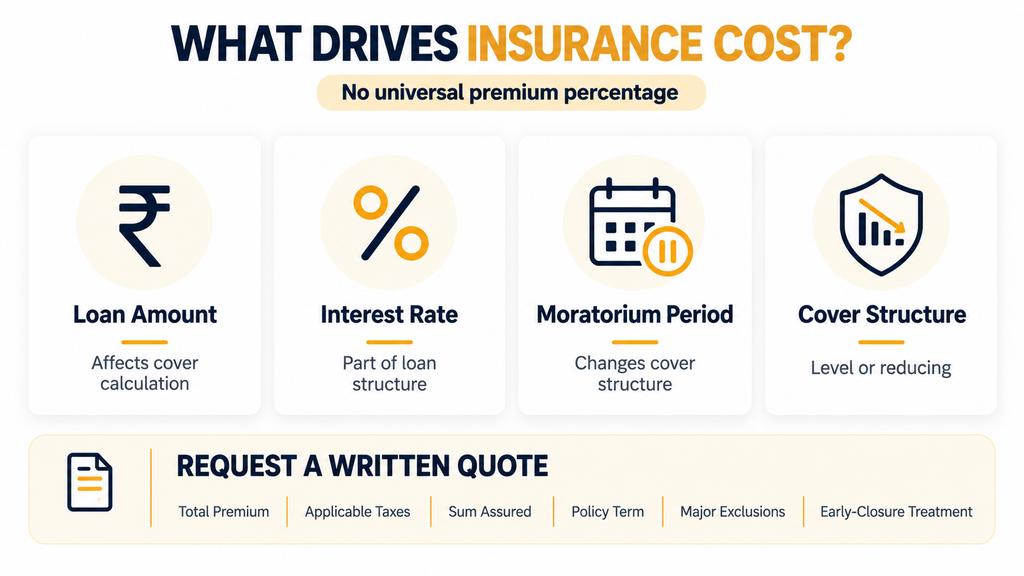
That is the correct way to compare education loan insurance cost.
When it comes to comparing loan protection insurance India, don’t just compare the price, compare the benefits. Reduced premium does not necessarily imply value when the level of insurance, the government-covered events or time limits may vary.
Read out: Co-Applicant in an Education Loan — Who Can Be One & Why It Matters
Is it possible to add the Insurance Premium to the Education Loan?
Yes, some lenders permit it.
Bank of India says the premium for its optional term cover can be included as an item of finance. Indian Bank says the life-insurance premium may be considered eligible for finance. Bank of Baroda says the premium may be added to project cost and recovered along with EMIs.
If the education loan insurance premium is financed, check:
- How much is added to your borrowing
- How it affects your repayment commitment
- Whether the charge appears in lender disclosures
- Whether paying the premium separately changes your total cost
RBI’s current Responsible Business Conduct Directions state that applicable third-party charges such as insurance charges recovered through a bank form part of APR disclosure and should be disclosed separately.
What Happens If You Repay the Loan Early?
Do not assume early repayment guarantees a full premium refund.
LIC’s Group Credit Life policy wording can allow continuation of cover after early loan repayment in stated circumstances and provides an Unexpired Risk Premium Value where applicable.
PNB MetLife also provides an unexpired premium benefit for certain premium structures on voluntary termination.
Before buying education loan insurance, ask what happens if you:
- Prepay a large portion of the loan
- Close the loan early
- Refinance with another lender
- Transfer the education loan
Early-closure terms can materially affect the policy’s real value.
Can Existing Term Insurance Be an Alternative?
Sometimes, but lender acceptance must be confirmed.
Bank of Baroda permits a term-insurance plan from an IRDAI-approved insurer as an alternative under Baroda Scholar. Indian Bank also allows another policy desired by the student borrower.
If you already have term cover, check whether:
- The lender accepts it
- The sum assured is sufficient
- The correct person is insured
- The benefit structure meets the lender’s requirement
- Enough cover remains for your family’s other financial needs
Existing term insurance and credit-life insurance are not automatically interchangeable.
For loan protection insurance India, compare the actual protection first and price second.
Check out: Education Loan Eligibility: Are You Eligible? (Self-Check Guide)
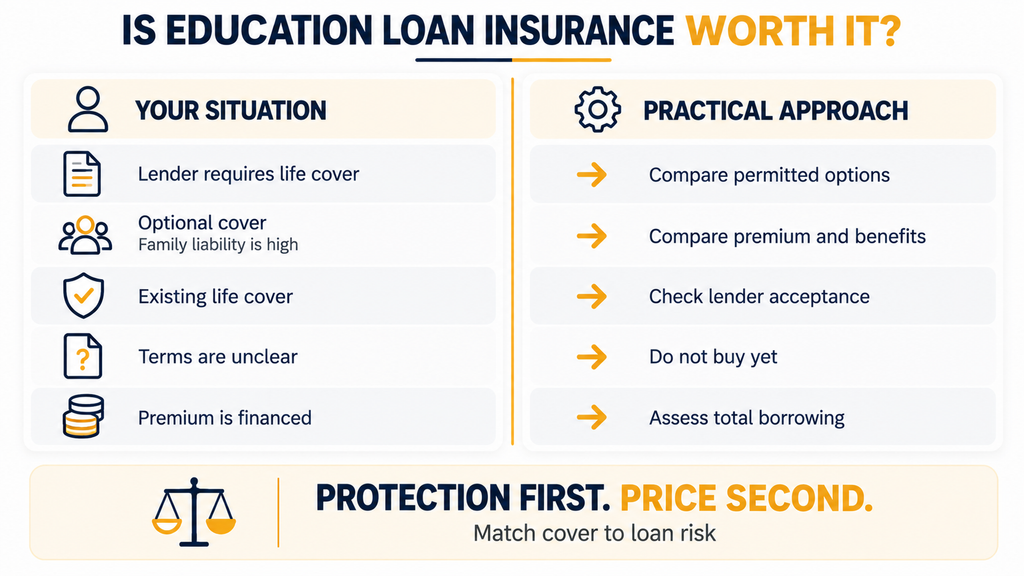
Is Education Loan Insurance Worth It?
| Situation | Practical approach |
| Lender’s written scheme requires life cover | Confirm minimum acceptable cover and compare permitted options |
| Cover is optional and the loan could create serious family liability | Compare premium, benefits and existing protection |
| You already have substantial acceptable life cover | Check lender acceptance before buying duplicate cover |
| Exclusions or early-closure terms are unclear | Do not buy until the terms are understood |
| Premium is being financed | Include it in the total borrowing assessment |
Education loan insurance may offer value when a covered event could otherwise leave a large unpaid liability with the family or co-borrower. Do not judge it only by whether the premium looks small.
7 Mistakes to Avoid Before Buying
- Assuming every lender follows the same insurance rule.
- Believing mandatory cover always means one insurer’s product is mandatory.
- Using an unsupported standard percentage for education loan insurance cost.
- Assuming every policy includes disability or critical illness.
- Ignoring exclusions and the benefit schedule.
- Assuming early loan closure guarantees a full premium refund.
- Financing the premium without considering the complete repayment commitment.
These mistakes can make loan protection insurance India look much simpler than it actually is.
Responsible Borrowing Check
Insurance does not make a larger loan automatically affordable.
Before finalising your borrowing, compare:
- Your actual funding gap after family contribution
- The amount you genuinely need to borrow
- Insurance premium and other financed charges
- Interest treatment during the moratorium
- Repayment tenure and EMI structure
- Co-applicant responsibility
If you want to understand how interest can behave before regular EMI repayment begins, read the Foreign Edu Loans guide to the education loan moratorium period and EMI.
Borrowing Rule: Students and parents should compare the complete repayment commitment, not only the sanctioned amount or advertised interest rate.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education. Its public policy states that it is not a bank or NBFC and does not itself provide, sanction, underwrite or disburse education loans.
Students can use Foreign Edu Loans to explore suitable education-loan options and compare different funding routes. The Foreign Edu Loans loan products page covers secured, unsecured and international-lender structures. Final approval and lending terms remain with the respective lender.
When comparing education loan insurance, treat the insurance requirement as part of the complete borrowing structure rather than as a last-minute add-on.
FAQs
Is education loan insurance compulsory for every education loan?
No. Current lender pages show different rules. Bank of India describes its cited overseas-study term cover as optional, while Indian Bank and Bank of Baroda have mandatory life-cover requirements under specified schemes or conditions.
What is the normal education loan insurance cost?
There is no verified universal percentage. The premium can depend on the sum assured, loan structure, moratorium and benefit option. Ask for an actual written quotation rather than relying on a general market estimate.
Does education loan insurance cover critical illness?
Not always. Some loan-protection products include specified critical-illness or disability options, while another credit-life policy may primarily provide death cover.
Can I use my existing term insurance instead?
Possibly. Some lenders expressly allow an alternative term policy, but acceptance depends on the exact education-loan scheme. Confirm this before relying on existing cover.
Will I get the premium back if I close the education loan early?
Not necessarily. The policies checked contain specific rules for continuation, termination or an unexpired premium value. A full premium refund should not be assumed.
Conclusion
Education loan insurance can be worthwhile when it protects a significant outstanding loan against a defined risk that could otherwise fall on the student’s family or co-borrower. But it should not be treated as an automatic add-on.
First confirm whether your lender’s exact scheme requires life cover. Then compare the actual premium, covered events, exclusions, cover structure, early-repayment terms and any acceptable alternative policy. If the premium is financed, include it in the complete borrowing assessment.
The best education loan insurance decision is the option that meets any genuine lender requirement while providing protection that makes financial sense for your loan and family circumstances.