An education loan for low-income families studying abroad may be possible, but low household income neither guarantees approval nor automatically disqualifies a student. The official sources reviewed here do not establish one universal minimum family-income threshold across all overseas education-loan products. It is eligible on the basis of the lender or a scheme requested, applicant profile, course, institution and security wherever necessary.
Add the total cost of the study, lessen the money assured by the scholarships and a realistic family contribution and compare finance to determine the difference.
Overview: Education Loan for Low-Income Families Studying Abroad
| Funding route | When it may help | First check |
| Scholarship or grant | You meet academic/category rules | How much debt it removes |
| Secured loan | Acceptable collateral is available | Asset risk and total repayment |
| Unsecured loan | No asset is pledged | Co-applicant and profile requirements |
| Credit-guaranteed loan | Loan fits CGFEL conditions | Scheme and lender eligibility |
| Category-specific finance | You meet community/income rules | Course scope and application route |
| Overseas interest subsidy | Scheme explicitly covers study abroad | Which interest is supported |
The right education loan for low-income families studying abroad is not automatically the largest sanction. It is the funding mix that closes the genuine shortfall without creating an unrealistic repayment burden.
Loan, Interest Subsidy or Scholarship: What Is the Difference?
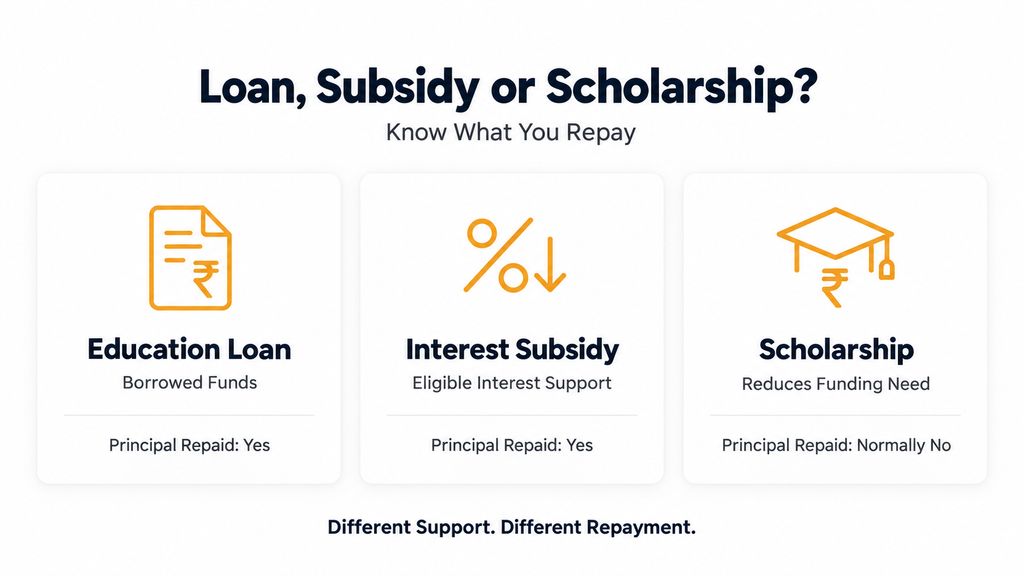
These three forms of support solve different problems.
| Support | What it does | Principal repaid? |
| Education loan | Provides borrowed funds for eligible costs | Yes |
| Interest subsidy | Pays eligible interest under scheme rules | Yes |
| Scholarship | Reduces the amount that needs financing | Normally no |
For an education loan for low-income families studying abroad, this distinction matters. A scholarship can reduce the principal before borrowing. An interest subsidy may reduce eligible interest, but the loan principal remains repayable.
Does Low Family Income Mean Rejection?
Not automatically, but income can matter.
A search for a low income education loan India option often produces generic minimum-income numbers. The official sources reviewed here do not support one market-wide figure. Government programmes publish their own income ceilings, while commercial lenders may assess income, liabilities, credit history, course, university, security and repayment capacity.
For an education loan for low-income families studying abroad, ask which structure fits your profile and actual funding gap.
Families with acceptable collateral can compare secured education loans. Those without assets to pledge can review education loans without collateral.
Co-applicant income, existing liabilities and credit history may also form part of lender assessment. Foreign Edu Loans explains these considerations in its co-applicant education loan guide.
Which Funding Route Should You Check First?
| Your situation | Start with |
| Eligible SC applicant | National Overseas Scholarship and NSFDC |
| Eligible OBC/EBC postgraduate applicant | Dr. Ambedkar interest-subsidy scheme |
| Eligible minority-community applicant | NMDFC Education Loan |
| Eligible Backward Classes applicant | NBCFDC Education Loan |
| No category-specific route, collateral available | Secured education loan |
| No collateral | Unsecured or eligible credit-guaranteed route |
| Scholarship confirmed | Recalculate the smaller loan gap first |
This is a screening framework, not an approval map. Every scheme and lender has separate conditions.
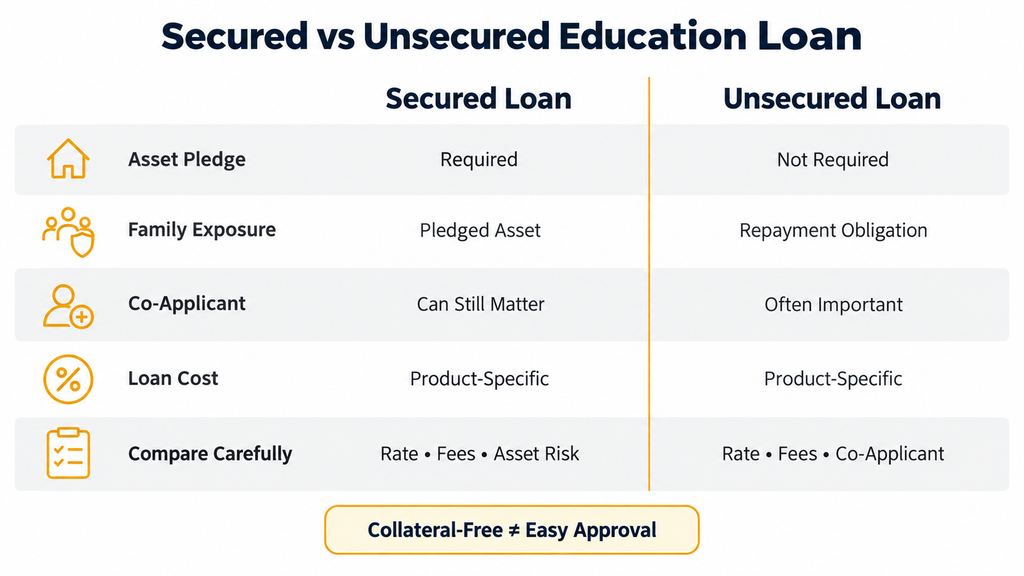
Secured vs Unsecured: What Changes?
| Factor | Secured loan | Unsecured loan |
| Asset pledge | Required | Not required |
| Main family exposure | Pledged asset | Repayment obligation without pledged asset |
| Co-applicant | Can still matter | Often important in profile-based underwriting |
| Cost | Product-specific | Product-specific |
| Compare | Rate, fees, asset risk, repayment | Rate, fees, co-applicant burden, repayment |
Foreign Edu Loans has separate guides to secured and unsecured loans. For an education loan for low-income families studying abroad, “collateral-free” does not mean “easy approval”, and collateral should not be pledged without understanding the risk.
Can Credit Guarantee Help Without Collateral?
Potentially.
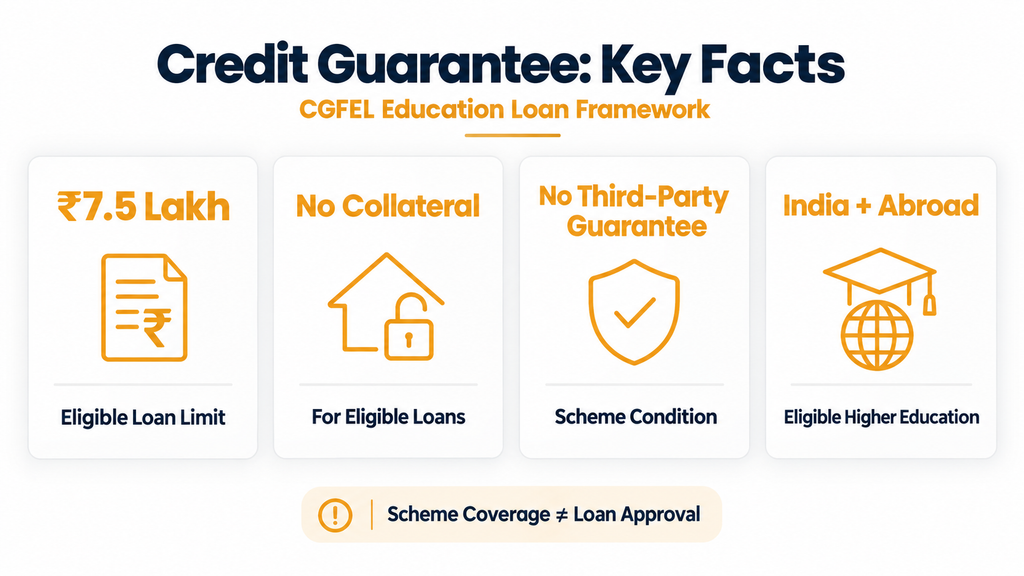
The National Credit Guarantee Trustee Company states that the Credit Guarantee Fund Scheme for Education Loans covers eligible education loans by IBA-member banks up to ₹7.5 lakh without collateral security or third-party guarantee. Its official FAQ says eligible borrowers include Indian nationals meeting the IBA Model Educational Loan Scheme for higher education in India and abroad.
That can support an education loan for low-income families studying abroad where the borrower and loan qualify. It does not mean the Government approves the student’s loan.
Which Government-Supported Options Apply to Overseas Study?
The term government subsidy education loan is often used too broadly. Some programmes are concessional loans, some subsidise interest, and some are scholarships.
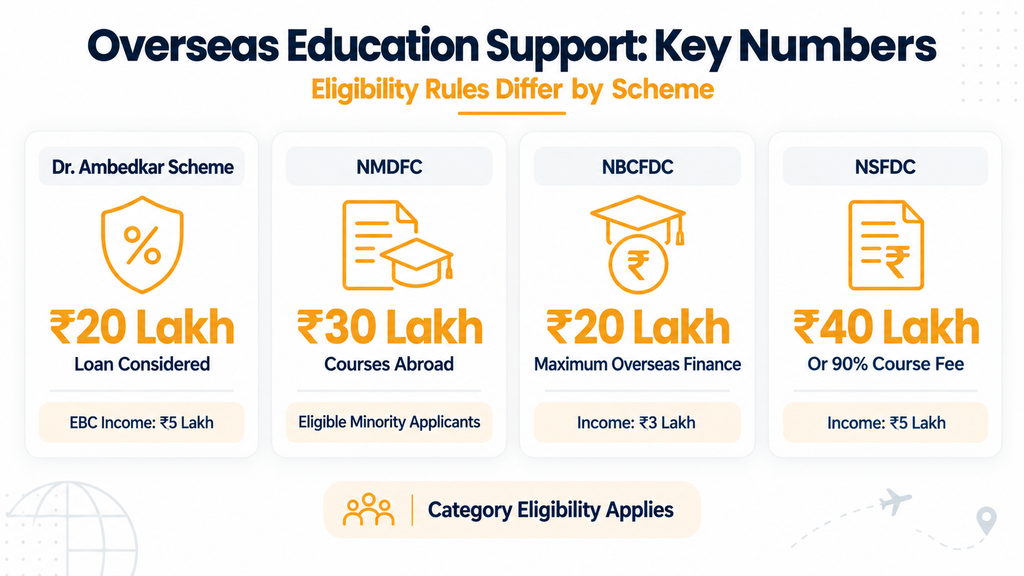
| Scheme | Target group | Verified overseas feature | Checked |
| Dr. Ambedkar Interest Subsidy | Eligible OBC/EBC | Master’s, M.Phil., PhD; EBC income ceiling ₹5 lakh; loan considered up to ₹20 lakh | 18 Sep 2026 |
| NMDFC Education Loan | Eligible minority communities | Up to ₹30 lakh for courses abroad under applicable credit lines | 18 Sep 2026 |
| NBCFDC Education Loan | Eligible Backward Classes | Income ceiling ₹3 lakh; up to 85% of overseas course expenditure, max ₹20 lakh | 18 Sep 2026 |
| NSFDC Educational Loan | Eligible Scheduled Castes | Up to ₹40 lakh or 90% of course fee, whichever is less | 18 Sep 2026 |
| National Overseas Scholarship 2026-27 | Specified eligible categories | Master’s/PhD; income ceiling ₹8 lakh; 125 fresh awards subject to rules | 18 Sep 2026 |
Dr. Ambedkar Interest Subsidy
The Department of Social Justice and Empowerment’s 2025-26 Annual Report states that eligible OBC/EBC students can receive support for approved Master’s, M.Phil. and PhD study abroad. For EBC applicants, the income ceiling is ₹5 lakh a year.
The Government bears 100% of eligible interest during the prescribed moratorium, while principal and post-moratorium interest remain the borrower’s responsibility. The maximum loan considered is ₹20 lakh.
Students should verify the latest conditions through the official Dr. Ambedkar overseas interest-subsidy page.
This is an interest subsidy scheme for abroad studies, not a scholarship and not automatic approval.
NMDFC, NBCFDC and NSFDC
The NMDFC Education Loan Scheme states that eligible minority-community beneficiaries can access up to ₹30 lakh for courses abroad. Rates are 3% p.a. under Credit Line 1 and 8% for male / 5% for women beneficiaries under Credit Line 2, with separate income criteria.
The NBCFDC Education Loan Scheme states a ₹3 lakh annual family-income ceiling and financing up to 85% of overseas course expenditure, subject to ₹20 lakh, for eligible applicants. Its current page states 4% p.a. for boys and 3.5% for girls.
The NSFDC Educational Loan Scheme information states a ₹5 lakh family-income ceiling, effective 7 January 2026, and education loans up to ₹40 lakh or 90% of course fee, whichever is less for eligible courses in India or abroad. The current FAQ lists 6.5% p.a. for the Educational Loan Scheme.
These can be relevant to an education loan for low-income families studying abroad, but each is category-specific rather than a universal low income education loan India programme.
Check Scholarships Before Increasing the Loan
The National Overseas Scholarship 2026-27 supports eligible specified categories for Master’s and PhD study abroad.
Its official guidelines set a ₹8 lakh family-income ceiling and 125 fresh awards, subject to availability of funds and selection rules. Bachelor’s courses are not covered.
For an education loan for low-income families studying abroad, scholarship screening should happen before loan maximisation. A confirmed scholarship reduces the principal that needs financing.
Which Popular Schemes Are India-Only?
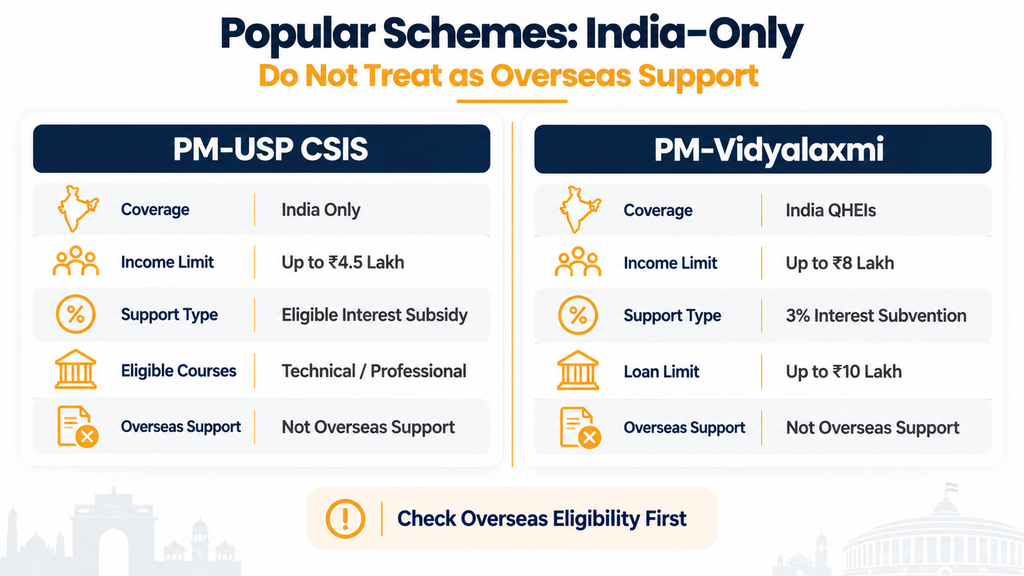
Two widely searched programmes should not be treated as overseas support.
PM-USP Central Sector Interest Subsidy
The Ministry of Education states that PM-USP CSIS provides full eligible interest subsidy during the moratorium on qualifying education loans for specified technical/professional courses in India, with annual parental/family income up to ₹4.5 lakh.
It is therefore not an overseas government subsidy education loan.
PM-Vidyalaxmi
The Ministry of Education’s PM-Vidyalaxmi guidelines state that the special collateral-free and guarantor-free loan product applies to merit-based admissions to designated Quality Higher Education Institutions in India.
Eligible students with family income up to ₹8 lakh can receive 3% interest subvention on eligible loans up to ₹10 lakh, subject to the scheme conditions.
Neither PM-USP CSIS nor PM-Vidyalaxmi should be presented as an overseas interest subsidy scheme for studies abroad. Mixing India-only and overseas programmes can distort a family’s funding plan.
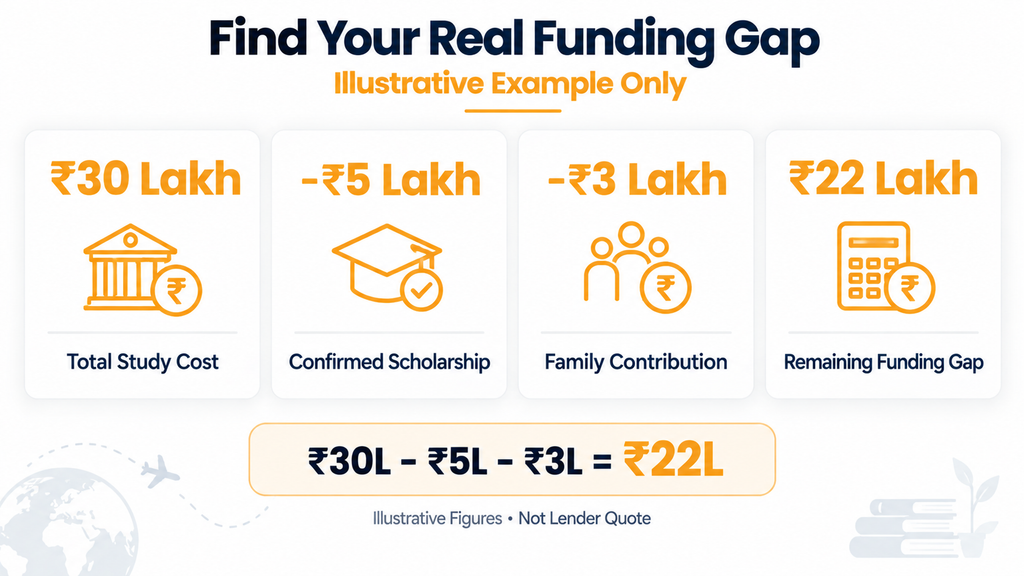
Illustrative Example: Find the Real Funding Gap
| Funding item | Illustrative amount |
| Tuition and essential study/living costs | ₹30 lakh |
| Confirmed scholarship | -₹5 lakh |
| Remaining funding gap | ₹22 lakh |
| Safe family contribution | -₹3 lakh |
Calculation: ₹30 lakh – ₹5 lakh – ₹3 lakh = ₹22 lakh.
This is an Illustrative Example, not a lender quote. No rate or fee is assumed.
An education loan for low-income families studying abroad should be sized around the ₹22 lakh shortfall, not automatically the ₹30 lakh headline cost.
Before choosing a loan amount, students can also use the Foreign Edu Loans education loan EMI calculator guide to test repayment scenarios. Calculator outputs are estimates, not lender sanctions.
Eight Steps Before You Apply
- Calculate the complete cost. Include tuition and essential study and living expenses.
- Subtract non-debt funding. Count confirmed scholarships, grants and a safe family contribution.
- Check targeted schemes first. Do this before relying entirely on commercial credit.
- Assess collateral risk. Decide whether pledging an asset is financially acceptable.
- Review the co-applicant. Check income, liabilities, credit profile and repayment responsibility.
- Compare complete terms. Look beyond the advertised interest rate.
- Model repayment. Include realistic treatment of study-period and moratorium interest.
- Borrow only the remaining gap.
That makes an education loan for low-income families studying abroad a budgeting decision first and a borrowing decision second.
Mistakes That Can Make a Tight Budget Worse
- Treating a scheme income ceiling as guaranteed loan approval.
- Assuming collateral-free means no underwriting.
- Confusing an interest subsidy with a scholarship.
- Using PM-USP CSIS or PM-Vidyalaxmi as overseas subsidies.
- Borrowing the maximum available amount instead of the real shortfall.
- Ignoring interest that may accrue during a moratorium.
- Assuming one lender’s co-applicant rule applies everywhere.
- Pledging a family asset without understanding the downside.
- Depending on a guaranteed foreign salary to make repayment work.
A moratorium is not automatically an interest-free period. Foreign Edu Loans explains the distinction in its education loan moratorium and EMI guide.
Responsible Borrowing
An education loan for low-income families studying abroad should improve access to education without creating an unreasonable household obligation.
Compare the amount needed, interest structure, margin, collateral exposure, expenses, moratorium interest, the repayment period, liability and currency risk of co-borrowers. Prudence of the test as opposed to a slow than anticipated initiation of post-study gains over presumed immediate increased revenues.
Borrowing Rule: Compare the complete repayment commitment, not only the sanctioned amount or advertised rate.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education. It can help students compare eligible lenders, understand documentation and co-applicant requirements, and coordinate applications.
Foreign Edu Loans is not the lender. Its website states that final lending decisions rest with the bank or NBFC.
For an education loan for low-income families studying abroad, the useful role is comparison after scholarships, family contribution and targeted support have been checked.
FAQs
Can limited parental income still qualify for an overseas education loan?
Possibly. There is no universal market-wide minimum family-income figure in the official sources reviewed here. The lender or scheme applies its own eligibility conditions.
Is there one low income education loan India scheme for everyone?
No. NMDFC, NBCFDC, NSFDC, Dr. Ambedkar and the National Overseas Scholarship target different applicant groups and apply different rules.
Is every government subsidy education loan available abroad?
No. PM-USP CSIS and PM-Vidyalaxmi are India-focused. Use only schemes that explicitly cover overseas education.
Can a loan be collateral-free?
Potentially. CGFEL covers eligible education loans up to ₹7.5 lakh without collateral security or third-party guarantee, and individual lenders can have unsecured products. Approval remains applicant-specific.
Is a moratorium interest-free?
Not automatically. Check the lender or applicable scheme to determine whether interest accrues, is serviced, subsidised or added to the balance.
Conclusion
An education loan for low-income families studying abroad can be part of a workable funding plan, but income alone does not determine the outcome. Start with scholarships and targeted support, calculate the genuine shortfall, then compare secured, unsecured or eligible guarantee-backed borrowing for what remains. Keep India-only subsidies separate from overseas programmes, and never treat a scheme income ceiling as guaranteed approval.
The strongest plan is not the largest sanction. It is the smallest realistic borrowing requirement that covers essential study costs while leaving the student and family with a repayment commitment they can understand and manage.
Check Your Education Loan Eligibility