Are you thinking of studying abroad, but don’t know how to apply for education loan for abroad? This is the question that most Indian students pose: how to apply for education loan for abroad without wasting weeks of my life with the paperwork and getting refused numerous times? We have been in the process of guiding thousands of students on education loans, and the same questions have been posed over the years, including eligibility, collateral, interest rates, and documentation. A lot of them thought they would not qualify till we took them through their line of real options. Reading this guide will explain specifically how to apply for education loan for abroad, the types of expenses it includes, the lender differences, eligibility and the entire Education loan application process in 2026, so you can how to apply for education loan for abroad without having to guess.
Check out: Education Loan for Abroad Studies: Complete 2026 Guide
The importance of an education loan to study abroad.
Education abroad is a costly business and not many families can afford tuition, costs of living and travelling at the same time.
- Use your family savings as savings rather than consumption.
- Access government schemes, subsidies and a tax benefit under Section 80E.
- Establish a clean record of repayment that underpins future financial objectives.
- Being admitted to one of the top 500 QS-ranked universities can enhance your interest rate.
There are several students who at first thought they would not be eligible to receive a loan until we explained to them that they can get one. It is important to start by learning how to apply for education loan for abroad.
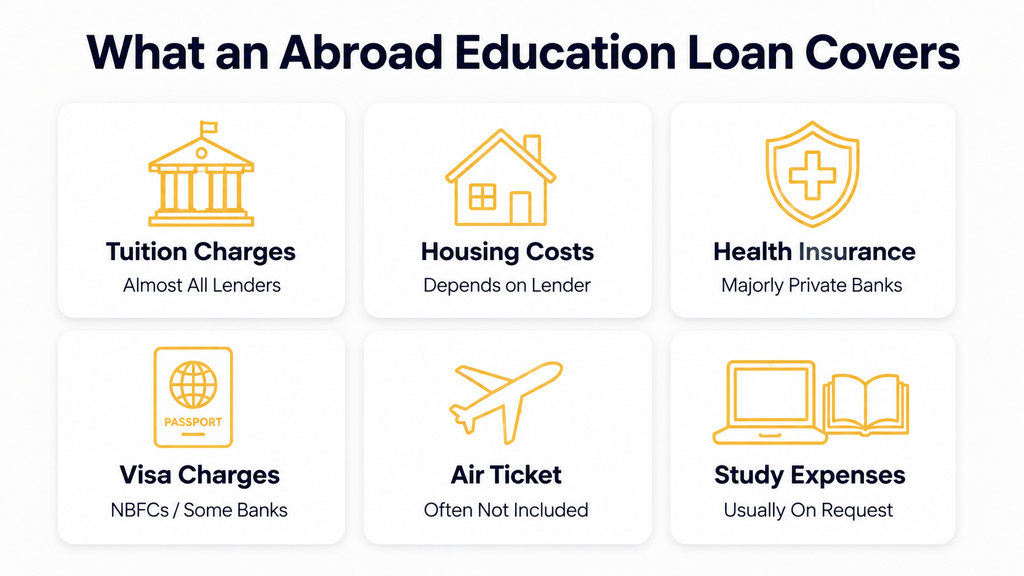
What an Abroad Education Loan Covers?
Every lending entity possesses a list of covered expenses, and therefore, one should always check with the lender.
| Expense | What It Covers | Normal Covers. |
| Tuition charges | Paid to the university directly, not to you | Paid by almost all lenders. |
| Housing costs | Rent, electricity, food, and domestic travel | Fully taken care of, but depending on the lender. |
| Health insurance | Compulsory medical cover abroad | Majorly privately covered by the banks. |
| Visa charges | Covers Visa application and processing costs | Visa charges are charged by NBFCs, and not by all banks. |
| Air ticket | Cost of a one-way or return flight | Not often included; may need to be requested separately. |
| Miscellaneous study | Laptop, books, project work, study tours | Most lenders will cover it on request. |
Secured and Unsecured types of Education Loans.
Your choice of the type of loan that best suits you should be made before you know how to apply for education loan for abroad.
| Characteristic | Secured Loan | Unsecured Loan |
| Collateral needed | Yes -property, FD or Insurance policy | No collateral needed. |
| Interest rate | Usually lower than average | Generally 1.5%to 4% higher. |
| Loan amount | Greater, depending on the value of collateral | Limited, depending on the lender. |
| Parental income | Not always required | Almost always required |
| During study repayment | Typically none | Repayment may be partial. |
| Approval opportunities | Relatively greater | Could be heavily reliant on co-applicant profile. |
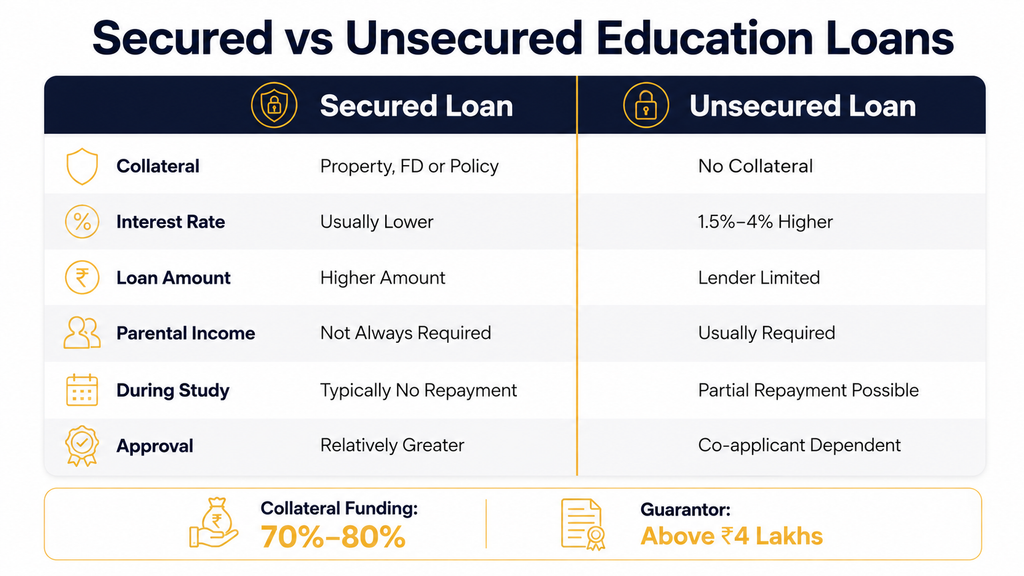
- The security against the loan is any movable or immovable property that is pledged as collateral to the loan.
- The lenders usually finance between 70% and 80% of the assessed value of the collateral.
- The loan amount above INR 4 lakhs typically requires a guarantor.
- In case of default on the part of your co-applicant, you are obliged to repay on the part of the one guaranteeing.
Check out: Loan Products
Comparison of lender and Education Loan interest rates.
The greatest relief for most families is to compare various banks without visiting each of the banks separately. This table combines loan amount, interest rate, tenure, and moratorium information of the most utilised lenders.
| Lender | Max Loan Amount | Type | Tenure | Interest Rate | Collateral | Moratorium |
| SBI (Global Ed-Vantage) | ₹1.5 cr with collateral, ₹50L without | Public bank | 15 years | 9.65% (women), 10.15% (men) | Optional | Course + 12 months |
| PNB (Udaan) | ₹2 cr with collateral | Public bank | 15 years | 9.25%–10.50% by university list | Required above limit | Course + 12 months |
| UBI | Up to ₹40L unsecured | Public bank | 15 years | Repo Rate + 2%, from ~9.8% | Optional | Course + 12 months |
| ICICI Bank | ₹1.5 cr secured, ₹20L–40L unsecured | Private bank | 8–12 years | 9.85%–15.5% by category | Optional | Course + 6 months |
| Axis Bank | ₹40L–75L without collateral | Private bank | 15 years | 11%–11.5% by category | Optional | Course + 6–12 months |
| IDFC First Bank | ₹1 cr secured, ₹75L unsecured | Private bank | 12 years | 11.50%–12.25% | Optional | Course + 12 months |
| HDFC Credila | Up to ₹75L without collateral | NBFC | 10–15 years | 11.25%–13% | Optional | Course + 6–12 months |
| Avanse | ₹20L–75L without collateral | NBFC | 15 years | 12.25%–14% | Optional | Course + 12 months |
| Auxilo | ₹20L–75L without collateral | NBFC | 12–15 years | 12%–13.25% | Optional | Course + 12 months |
| InCred | ₹20L–80L without collateral | NBFC | 12–15 years | 11.65%–13.5% | Optional | Course + 12 months |
| MPOWER Financing | Up to USD 100,000, no collateral | International | 10 years | 9.99% p.a. | Not required | Course + 6 months |
| Prodigy Finance | Up to ₹50L without collateral | International | 10 years | 10.5%–14% | Not required | Course + 6 months |
Eligibility to have an Abroad Education Loan.
The second thing students ask about loan amounts is eligibility.
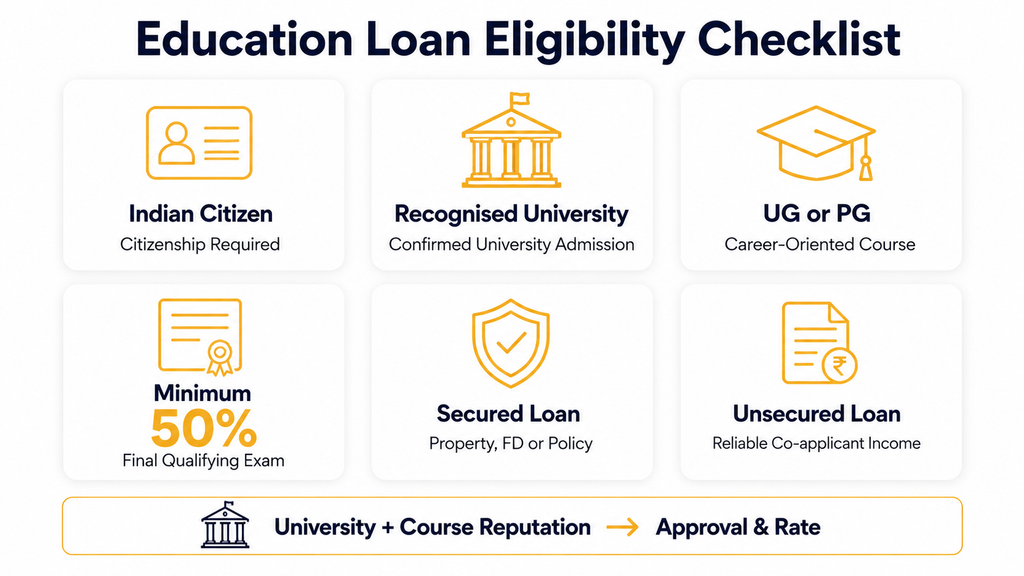
- You must be an Indian citizen and graduated in a recognised university
- It must be a postgraduate or undergraduate career oriented course
- Your final qualifying exam has a minimum of 50% marks required
- Property, FD or an insurance policy can be used to secure the secured loans.
- The unsecured loans will generally require a co-applicant who has a reliable source of income.
- The reputation of universities and courses has a direct impact on the probability of approval as well as the rate of interest.
Recently, one of our students has obtained a loan from SBI after one of them analysed several banks on our platform, and this was due to their profile of co-applicant, as the bank could approve their income requirements. These eligibility guidelines are fundamental learning in the acquisition of knowledge on how to apply for education loan for abroad because at this point, the majority of rejections occur.
Documents needed for an education loan to study abroad.
You have documentation requirements depending on the lender and type of loan, but this is virtually everything that nearly all banks require.
| Category | Important Documents |
| Address proof | Utility bill, Aadhaar, lease agreement, voter ID |
| KYC evidence | Aadhaar card, PAN card, driving licence, valid passport, |
| Score of the entrance exams | GRE, GMAT, IELTS, TOEFL |
| Your academic details | Your 10th as well as 12th class mark sheets, admission proof, and semester results |
| Co-applicant financials | Form 16, ITR, Salary slips, 6 months’ bank statements |
| Collateral — legal | Khata certificate, Sale/gift deed, tax receipt, encumbrance certificate |
| Collateral — technical | NOC, Layout plan, prior sale deeds, possession certificate |
I believed it to be hard to how to apply for education loan for abroad, after which we got to know, along with an explanation on every possible avenue, all the possible options and assistance on which bank to get the loan, overheard with many first-time borrowers, one of the easiest methods of enhancing the speed at which to get education loan for study abroad approvals is to have this checklist ready beforehand.
Key Features to Check Before You Apply
It is easy to guess that after a conversation with our specialists, parents say that the process of making a loan was much more comfortable, primarily due to the fact that it is such features that are simple to ignore.
- Loan coverage: Find out precisely what is covered: tuition, living expenses, or insurance.
- Interest rate: Co-applicant profile is strong, and therefore, it would have a considerable reduction in the rate offered to you.
- Moratorium period: Typically course duration plus 6-12 months to EMIs commence.
- Repayment period: Lenders will have a maximum of 12 to 15 years to repay.
- Exchange rate protection: A few lenders provide protection against currency volatility.
- Special schemes: Government schemes and university schemes could lead to a reduction in the processing fees or interest.
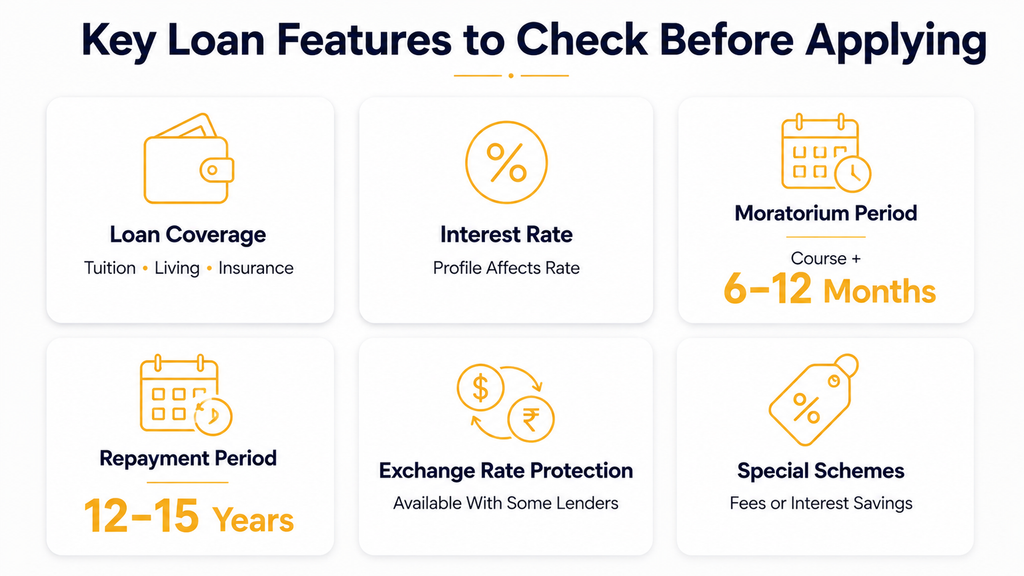
An inspection of these features is a sensible aspect of the education loan procedure that most students overlook.
Step-by-Step Guide: How to Apply for Education Loan for Abroad
This is the very important to understand how to apply for education loan for abroad, and all stages count should you wish to have a smooth sailing through. The sequencing in order of application of the education loan prevents the majority of delays.
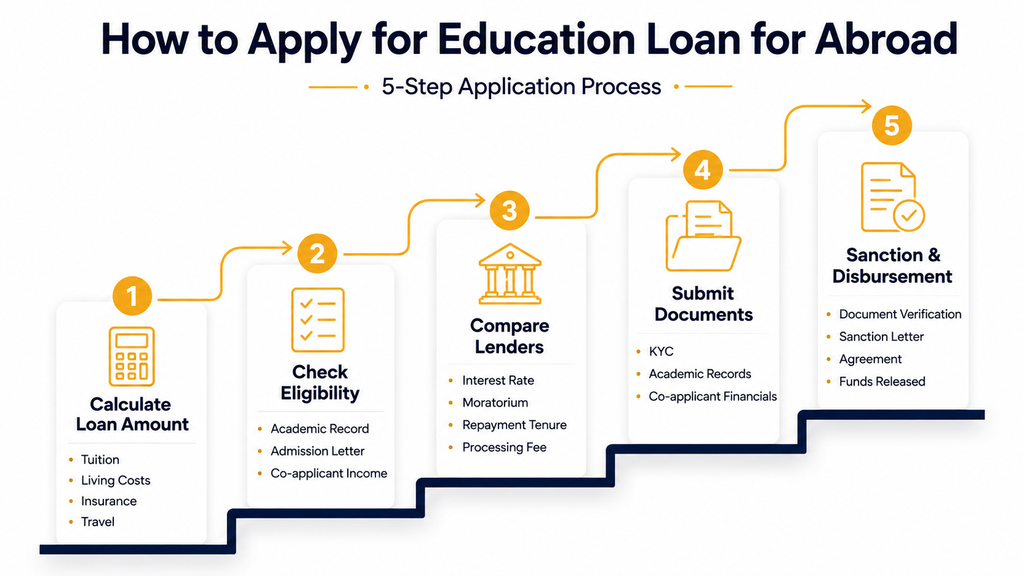
Step 1: Calculate Your Loan Amount.
Add the list of tuition, living costs, insurance and travel costs and go out and approach any lender. The first step in the process of applying for an education loan abroad is really knowing the exact figure.
Step 2: Check Your Eligibility
Compare your academic record, letter of admission and co-applicant income with lender requirements. This is sufficient to eliminate the majority of unnecessary rejections that the education loan process would have.
Step 3: Compare Multiple Lenders
Shortlist two or three options based on the rate of interest, lender and your budget; use the interest rate and lender comparison table above. Being able to compare several banks without having to travel to each of them separately is the most viable relief to the majority of households, and it is the key to education on how to apply for education loan for abroad.
- Compare interest rates in government banks, commercial banks and NBFCs.
- Determine the moratorium and overall repayment tenure.
- Processing fee and prepayment or foreclosure.
- Check that you confirm the amount that each lender actually pays in the approved amount.
Step 4: You need to prepare and Submit Documents
Provide your KYC documents, education history and co-applicant financials according to the lender checklist. This is usually the slowest step in how to apply for education loan for abroad.
Step 5: Disbursement and Loan Sanction
Upon document verification, you get a sanction letter giving details about the amount and terms of the loan. Funds are immediately paid to your university and, in most cases, to your account after the agreement has been signed.
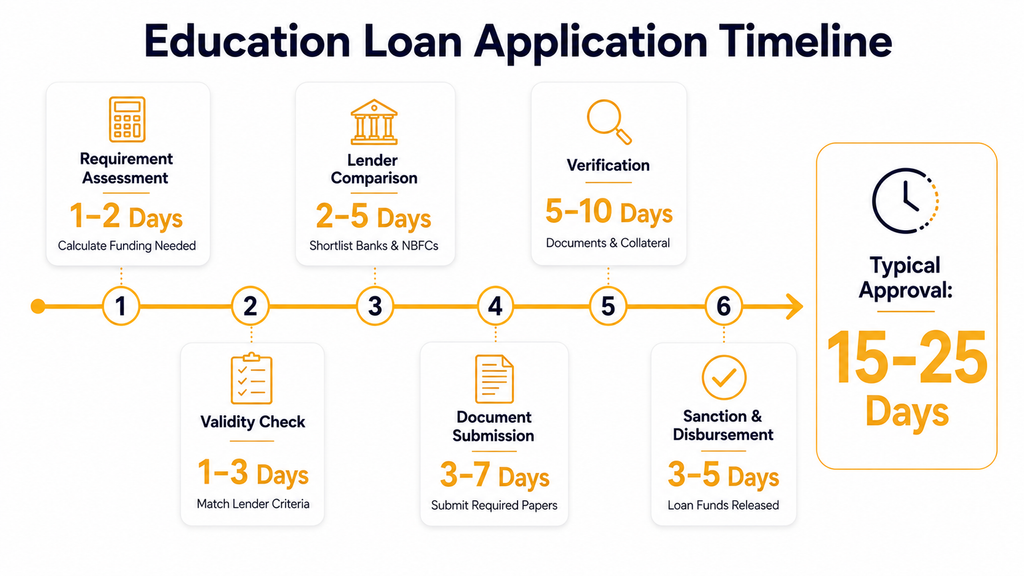
Overview of Education Loan Application.
| Stage | What Happens | Time Timeline. |
| Requirement assessment | Calculate total funding needed | 1 to 2 days |
| Validity check | Profile matches lender criteria. | 1 to 3 days |
| Comparison of lenders | Shortlist banks and NBFCs | 2 to 5 days |
| Submission of documents | Deliver or mail the needed papers. | 3 to 7 days |
| Verification | Lender authenticates documents and collateral. | 5 to 10 days |
| Disbursement and Sanction | The amount of loan to be released to the university. | 3 to 5 days |
These are the process you can use while understanding how to apply for education loan for abroad. Also that are used in all types of banks extending credit through public banks, private banks and NBFCs.
How to Improve Your Loan Approval Chances?
- Include a co-applicant with a consistent and verifiable income source.
- Make applications to universities that belong to a category of the most preferred or listed institutions by a lender.
- Maintain your grades and entrance examination grades as high as possible.
- Ensure that you and your co-applicant have a good credit history.
- Do not have several loan applications with conflicting information with different lenders.
Common Mistakes to Avoid: How to Apply for Education Loan for Abroad
- Applying without estimating the amount of loan that you require.
- Planning your budget later in the month without paying attention to the moratorium period.
- Filing incomplete co-applicant financial forms, which delays processing.
- Selecting a lender based solely on interest rate and not examining expense coverage.
- Doing without a contrast between a secured and an unsecured loan.
Loans and Scholarships: A Smart Combination
Scholarships have the capacity to greatly lessen your loan debt, and they must be a consideration before determining the size of your loan.
- Both use university-specific scholarships and your loan application.
- Check funding options using government portals; one is the Vidya Lakshmi Portal.
- Increase or decrease the requested amount of the loan after receiving assurance of scholarships.
Such a question is often posed by students who need to know how to apply for education loan for abroad but have a scholarship in their hands – just tell your lender beforehand.
Repayment Planning Before You Take Off.
The question of how to apply for education loan for abroad is just half the battle; do not stop financial planning when your loan is disbursed. Premake: Students must:
- Know the start and end of your moratorium period and the start of EMIs.
- Allow a margin in foreign exchange which could influence the repayment values.
- See whether your lender provides exchange rate protection on the loan.
- Research overseas part-time employment opportunities to lessen the strain of EMI in the future.
Being familiar with the entire procedure of the education loan in advance will not place you in any unpleasant financial surprises when you make it to the ground in a foreign country.
Reasons to Select Gateway International Services for Foreign Edu Loans
Gateway International for Foreign Edu Loans has been assisting students in applying to the USA, UK, Canada, Australia, Germany, France, Italy, Ireland, Dubai, New Zealand and Europe, with more than 23,000 students guided over 15+ years of experience. We are here to help you how to apply for education loan for abroad:
- Apply and compare various education loans on one platform.
- Get in-service support from eligibility assessment to loan disbursement.
- Get customised lender suggestions, tailored to your financial and academic profile.
- Get total loan services without any extra service fees.
- Collaboration with banking partners such as SBI, HDFC Bank, Bank of Baroda, Axis Bank, InCred and IDBI Bank.
Trust Gateway International with their open and student-centred loan servicing, either when you are getting started with the process of applying for an education loan to study in foreign countries or when you are ready to file your application. [Check Your Eligibility]
FAQs
Who may qualify to get a study abroad education loan?
Generally, eligible are Indian citizens who are confirmed into a university with career-oriented courses and have not less than 50% in the last qualifying examination.
Is it possible to get a loan not using collateral?
There are actually unsecured education loans, but they typically require a solid co-applicant and have a slightly higher interest rate.
How do you know which lenders to compare in the shortest period?
The easiest method of learning how to apply for education loan for abroad is to use a platform that displays more than one offer.
What is the time taken for loan approval?
The lender takes 15 to 25 days to complete the education loan process, depending on the availability of documentation and checks on collateral.
Would scholarships decrease my education loan?
Yes, confirmed scholarships can reduce the amount you request a loan for and decrease your total interest payments by a significant margin.
What are the documents needed?
They usually require KYC evidence, school documents, application religious marks, collateral in case of secured loans, and collateral paperwork.
Conclusion
It would get much easier to know how to apply for education loan for abroad once you know the costs to be covered, eligibility, the highest documentation, and the entire process of applying for an education loan. By shopping around for lenders and learning the education loan procedure- the interest rates, moratorium and collateral needed- you also save yourself weeks of paperwork waiting, not knowing what to prepare. Because of your profile and the financial strength of your co-applicant, you can place yourself in an advantageous position to either take a secured loan at a lower rate or an unsecured loan at a faster pace; the question of how to apply for education loan for abroad is determined. It is the exact decision that Gateway International has assisted more than 15 years in helping the students make with confidence. And when you are ready, talk to our specialists and take the second step in a foreign country.
Pingback: What Most Students Don't Know About an Education Loan for PhD
Pingback: Not Everyone Needs a Full Degree — Get an Education Loan for Diploma Courses Abroad
Pingback: Know the Rules for an Education Loan for Online Courses