A foreign doctorate may take years of financial planning; this is due to the costs that are not solely in the form of university fees. An education loan for PhD abroad India will enable deserving students to pay the tuition fees, lodging expenses, living allowances, travel, research gadgets and other educational-related costs approved by the lender. Nonetheless, the value of the corresponding loan should be based on the necessary amount of funding that the individual requires, taking into account the scholarships, the research stipends, the assistantships and the efforts of the family members. Funding for PhD abroad students must also keep a comparison of securities, non-secures, collateral, co-applicant, moratorium, repayment, and other obligations. Lender policies and interest rates of the loans depend on the amount of loan and the profile of the applicant; where education loan for PhD abroad India is concerned, it will be necessary to compare the education loans. This guideline describes the possible funding sources, criteria, costs, paperwork and plan to repay on time, responsibly.
Read out: How to Apply for Education Loan for Abroad: Step-by-Step (2026)
Education loan for PhD abroad India: Overview.
| Factor | What PhD Applicants Should Know |
| Maximum funding | The number of limits differs greatly based on the lender, the institution, the programme, and the profile of the applicants. |
| Loan availability | Banks and other lenders can fund eligible programs abroad in doctoral programs. |
| Collateral | The requirements vary depending on the size of the loan, the product and the class of lender institutions. |
| Expenses | Tuition, living, travel, books, equipment and approved research expenses may be eligible. |
| Co-applicant | Broken credit history and current liabilities might affect assessment. |
| Moratorium | Lenders have significant differences in course and grace-period structures. |
| Alternative funding | Scholarships, stipends, and assistantships will significantly decrease the amount of borrowing. |
| Repayment | Borrowers need to take into consideration accrued interest and after-study repayment ability. |
What it does not imply to you: An education loan for PhD abroad India should finance you. The actual funding gap, and not necessarily the maximum, should be financed by an education loan.
Why PhD Financing Needs Different Planning?
Uncertainty of a doctorate is a possibility that less intensive programmes might lack. Fieldwork, specialised software, conferences, lab bills or extra semesters may be required in research.
In case of education loan for PhD abroad India, develop a multi-year budget instead of focusing on tuition in the first year.
- Include tuition fees per year of study funded.
- Determine accommodation and living costs during the doctorate.
- Budget individually laboratory equipment, software and academic material.
- Includes travel needed to conduct research or sanctioned academic functions.
- Have an emergency buffer of additional expenditure in approaching the programme.
- Multiply a currency movement where the expense to be paid is not the case within India.
- Verified scholarships and assistantships and then compute borrowing requirements.
It is possible that an education loan for PhD abroad India can be used to supplement, rather than to displace, institutional funding.
Read out: Education Loan Eligibility
What is the maximum amount of Education Loan PhD students can get?
No universal limit can be used for all doctoral students.
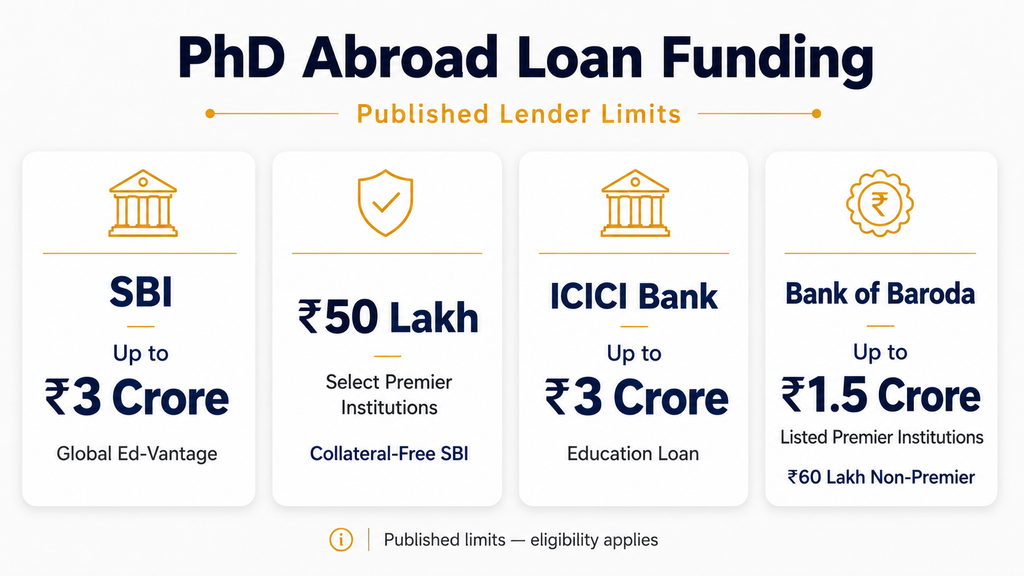
The current Global Ed-Vantage page of SBI mentions that overseas-study loans (qualifiable) can be up to ₹7.50 lakh to ₹3 crores. It also promotes collateral-free lending of up to ₹50 lakh to select premier institutions and up to 15 years of repayment.
ICICI Bank, at present, mentions that its education-loan product can reach as high as 3 crore in both international and local studies. Its organisation-related information specifically affirms that it contributes to the availability of education loan for PhD abroad India.
The Baroda Scholar scheme of Bank of Baroda now says that a maximum of ₹1.5 crore is per institution in the premier list and ₹60 lakh in non-premier institutions.
| Lender | Relevant information published | Relevant important qualification. |
| SBI Global Ed-Vantage | Up to ₹3 crore | Product, institution and security conditions apply. |
| ICICI Bank | Up to 3 crore | Final amount is subject to eligibility and evaluation. |
| Bank of Baroda Scholar | Up to ₹1.5 crore for listed premier institutions | Less than ₹1.5 crore for non-premier institutions |
These are published limits which are not assured sanctions. Upon underwriting, you may have your education loan for PhD abroad India application approved in a lesser amount.
Secured or Unsecured Loans to a PhD Abroad.
An education loan for PhD abroad India can be arranged in different ways on the basis of the loan originator and amount required.
| Factor | Secured Loan | Unsecured Loan. |
| Security | Collateral approved by lenders is given | No tangible collateral is given. |
| Assessment | Student / co-applicant and collateral matter | Student and co-applicant profiles are critical. |
| Loan size | Greater requirements are more easily accommodated | Heavy contingencies on lender underwriting. |
| Processing | Legal and valuation checks can be performed | Property verification is not usually required. |
| Borrowing cost | Can be relatively low cost | Can be relatively high cost. |
| Appropriate to | Bigger funding requirements with reasonable security | Appropriate for profiles that lack appropriate collateral. |
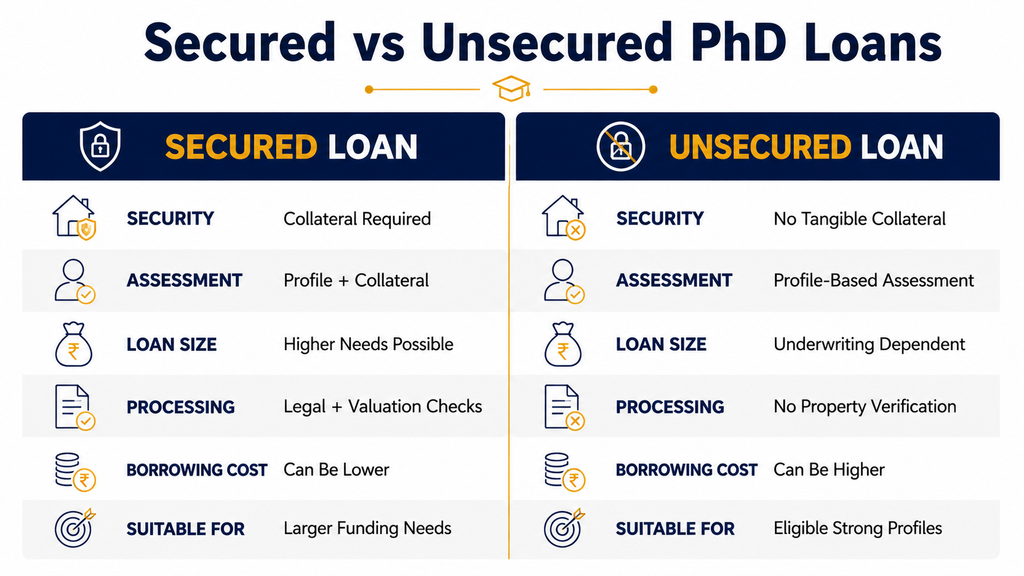
The residential or commercial property, fixed deposits or other security permitted by the lender may serve as possible collateral.
The existing Baroda Scholar terms used by Bank of Baroda, such as tangible collateral requirements in case of higher slabs of loans. SBI Global Ed-Vantage also recognises tangible collateral in addition to offering an individual collateral-free facility to selected superior institutions.
Consequently, no research scholar loan India candidate is supposed to assume the similarity of certain security guidelines for amounts above a specific limit.
Read out: Documents Required for Education Loan (2026 Checklist)
What Expenses Can a PhD Education Loan Cover?
A doctorate will establish the cost of research in addition to university tuition.
An education loan for PhD abroad India may also be helpful in financing:
- Tuition fee and other institutional fees accepted by the university.
- Hotel, house or authorised living costs.
- Study, library and lab fees at the university.
- Necessary books, tools and teaching material.
- Computers necessary to fulfil the doctoral programme.
- Authorised study tours and university project spending.
- Lender cost-related to the thesis found in lender rules.
- Allowable cost of travelling abroad to study.
- Insurance costs as allowed under the loan product.
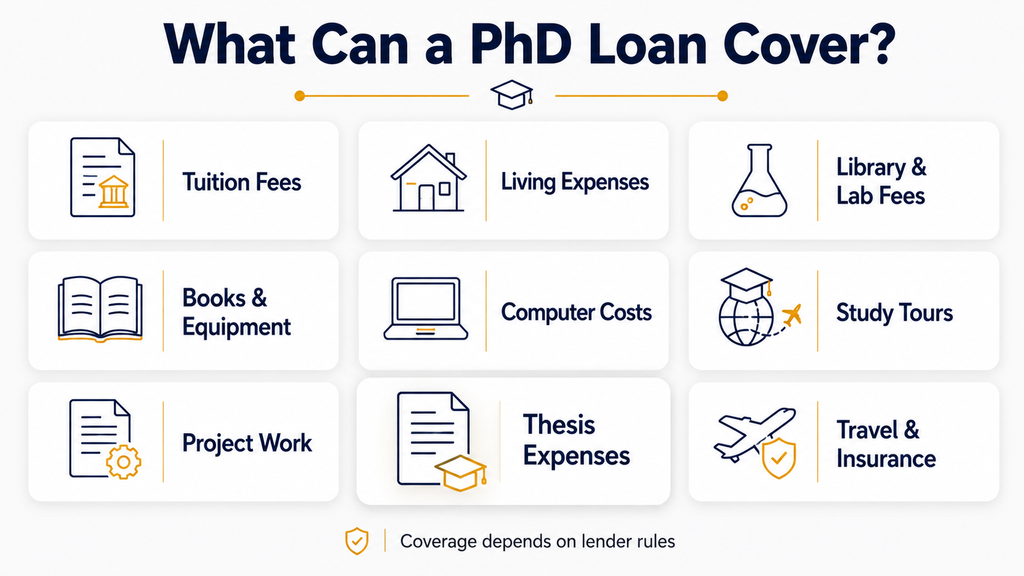
Bank of Baroda covers books, equipment, computers, study tours, project work and project theses-related expenses clearly as part of any eligible expenditure under Baroda Scholar.
Whenever possible, students researching funding for a PhD abroad ought to prepare a university-supported cost sheet.
Scholarships and Assistantships Should Come Before Borrowing
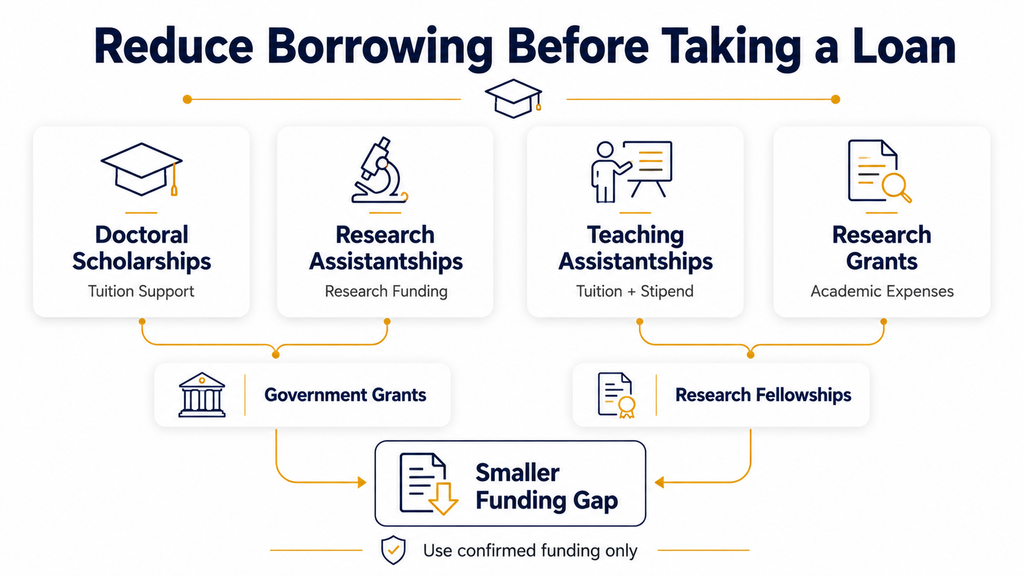
The remaining difference between convenient non-debt funding and a loan should be commonly financed.
To most researchers, a PhD abroad can be financed and include:
- Doctoral scholarships to universities (pay tuition fees).
- Research assistantships related to supported scholarly initiatives.
- Tuition support or stipend teacher assistantships.
- Departmental research grants to expend to allowable academic spending.
- Government grants to promote specific groups of students.
- Fellowships overseas or overseas research fellowships abroad.
SBI particularly makes it clear that one may count amounts of scholarship or assistantship in addition to computing margin requirements under Global Ed-Vantage.
The 2026-27 National Overseas Scholarship financially assists eligible Master and PhD studies abroad in specific categories. The existing government guidelines give a family-income ceiling of ₹8 lakh annually and support in terms of tuition and maintenance allowances.
Co-Applicant Assessment Matters
The co-applicant is the one who can be evaluated by a lender since doctoral students have the potential of staying in school over a few years.
In a research scholarship loan India evaluation, it can take note of:
- Co-applicant’s relationship with the student.
- Constant and reliable business or employment income.
- Current loan and EMI payments.
- Past behaviour and credit history.
- Income-tax records and bank statements.
- General ability to cover financial commitments.
ICICI Bank now enumerates various types of co-borrower interactions that are allowed, such as parents, siblings, spouse, grandparents and designated relatives. Definitions of lenders are, however, different.
Never think there is a single income or credit-score requirement that is necessary to be approved.
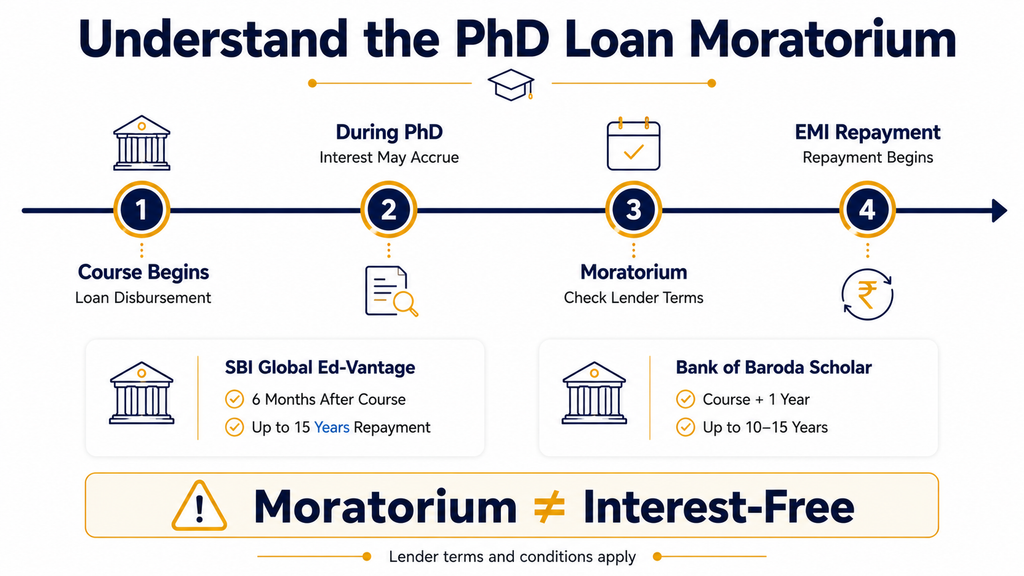
Moratorium Does Not Immediately imply interest-free.
This is mainly essential in case of an education loan for PhD abroad India since doctoral programmes may be very long.
According to SBI Global Ed-Vantage, simple interest is paid in the course and moratorium. The principal is subject to accrued interest, and repayment is commenced 6 months after taking a course and lasts as long as 15 years.
Bank of Baroda Scholar now mentions a repayment holiday of the course period and one year, and repayment up to 10-15 years, respectively, based on the conditions.
Repayment Hack: The longer the doctoral programme, the greater the fixed cumulative interest that accrues before regular EMIs set in.
The decision of proceeding with the education loan for PhD abroad India should hence not be based on monthly EMI, but the total repayment responsibility.
Documents PhD Applicants Should Prepare
| Listing | In general, documents need to be provided on a regular basis. |
| Identity | Passport, PAN, address proof, and lender-requested KYC. |
| School work | Marksheets, certificates, transcripts and test scores, etc. |
| Admission | Programme details and admission confirmation, offer letter. |
| Costs | Documentation of official tuition and estimated programme expenses. |
| Research | Research/course information where requested. |
| Co-applicant | Identity, income, work and bank records. |
| Financial | Salary slips, ITRs, Form 16 or business records where applicable |
| Guarantee | Title and property papers for secured loans. |
Both SBI and Bank of Baroda have documentation requirements which include KYC, academic, admission evidence and financial information.
An actual list of a research scholar loan application in India varies according to the circumstances of the lenders and the applicants.
How to Apply for an education loan for PhD abroad India?
1. Divide the Overall Cost of the Programme.
Add the tuition, living expenses, cost of research, travel and emergency costs and calculate your total PhD budget.
2. Deduct Confirmed Non-Loan Funding.
Deduct scholarships, stipends, assistantships and family gifts to come up with the real amount of external funding you require.
3. Compute the Actual Funding Gap.
Divide the rest of the funding gap and only borrow to meet your actual education costs.
4. Secured vs Unsecured Options.
Compare secured or unsecured loans in terms of collateral and the total cost of borrowing, co-applicant requirements and flexibility of repayment.
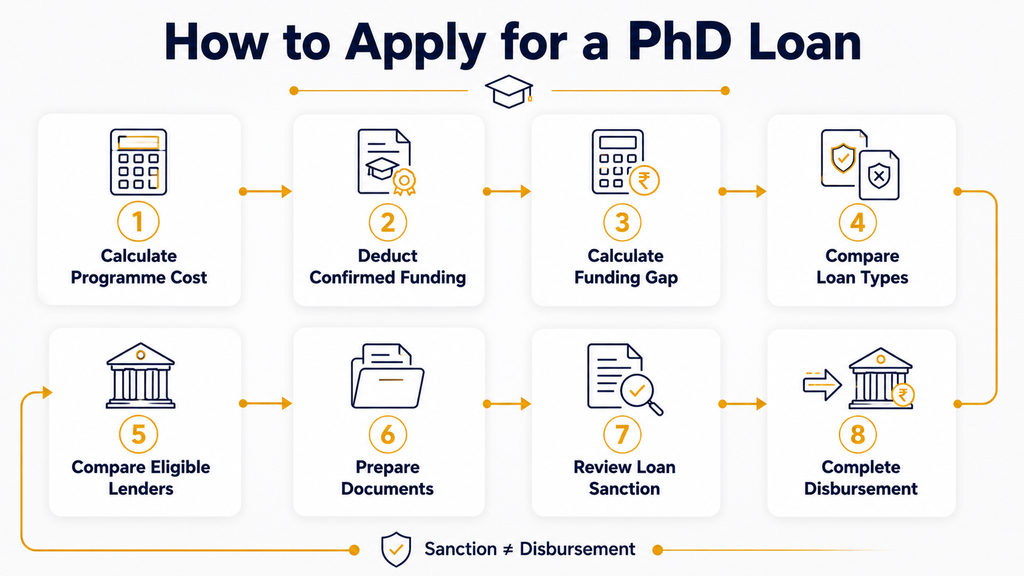
5. Compare Eligible Lenders
Compare lenders to provide an education loan for PhD abroad India according to your university, programme, funding requirement and profile.
6. Get the necessary documentation ready.
Prepare your academic information, admission, financial statements, co-applicant papers and collateral documents before submitting your application.
7. See the Loan Sanction Ready.
Sanctioned sum, applicable rate structure, margin requirement, moratorium, supplementary charges and repayment terms must be reviewed and accepted.
8. Fill in the Disbursement Requirements.
Finalise all lender requirements once approved to secure funds to get disbursed when there are agreed terms.
Common PhD Funding Mistakes
- Eligibility Deadlines: First confirm scholarships and then calculate your education loan for PhD abroad India funding requirement.
- When estimating the overall cost of financing a PhD in a foreign country, include the living and research costs.
- Do not expect all universities to offer secure financial aid throughout an international doctoral programme.
- Consider checking collateral before choosing education loan for PhD abroad India to fund higher studies.
- Take into account moratorium interest since the accumulation of interest can make a major difference in terms of the ultimate amount paid minus the loan.
- Use fully disclosed terms to select an Indian research scholar loan instead of adopting advertised rates.
- Take into account currency fluctuations since they may tend to drive up your education loan for PhD abroad India.
- Borrow the necessary amount of money since you are not supposed to get an additional loan simply because it will enable you to get a higher loan.
Assistance through Foreign Edu Loans.
Foreign Edu loans may enable qualified students to comprehend their education loan for PhD abroad India and compare structures based on profiles.
Support may include:
- Determining whether the student is eligible to take loans to get an education.
- Comparison of similar banks, NBFCs, and international lenders.
- Learning the methods of secured and unsecured financing.
- Considering co-applicants and collateral.
- Arranging documentation that was necessary to get lender assessment.
- Knowing about sanctions and subsequent disbursement.
Foreign Edu Loans helps in comparison of the loans and advising on loan application; the lender of interest arrives at the ultimate credit decision. This placement is as required in the editorial supplied, that Foreign Edu Loans must not be positioned as an independent institution granting loans.
Verify Your Education Loan. Know what choices can be available to your university, programme, in need of funds and co-applicant details.
FAQs
Is it possible to have an education loan for PhD abroad India without collateral?
Yes. An education loan for PhD abroad India need not be secured, depending on the lender, university, loan amount and profile of the applicant.
What is the amount of funding of the PhD loan India?
The value of an education loan for PhD abroad India depends on the lender, university, programme, amount of funds required, security and the overall profile of the applicant.
Does it allow funding a thesis and research using a loan?
Yes, funding of PhD abroad programmes does include approved thesis, equipment, project and research costs by a lender.
Is there any requirement of a co-applicant when applying for a research scholar loan in India?
Depending on the eligibility of the lender and underwriting conditions, a research scholar loan India might have a co-applicant.
Would scholarships help to lower my loan amount?
Yes. Your education loan for PhD abroad India requirement can be decreased substantially by scholarships, stipends and assistantships.
Is the interest-free PhD loan?
Not necessarily. In the case of education loan for PhD abroad India, the interest can be charged in accordance with the moratorium, as stipulated by the lender.
Conclusion
An education loan for PhD abroad India has the potential to cover the gap between the promised academic scholarships and the full price of an overseas PhD. Borrowing, however, must start after tuition, the cost of living, research needs, scholarship and assistantships and contributions by the family have been calculated.
Compare the lenders for more than the interest rate advertised. Think about the amount of loan the borrower is eligible to obtain, collateral, margin, co-applicant, moratorium, charges, conditions of disbursement and overall repayment.
A research scholar loan India applicant may also find it especially important to plan the repayment since the duration of the programme is longer. Compare policies of lenders in the present day and borrow as much as is necessary for the research programme.
Check Your Education Loan Eligibility to find out your financing options based on the best fit for your programme and financial profile.