Education loan for New Zealand study India should have a budget over and above tuition fees. A New Zealand education loan has the potential to cover the essential costs of tuition, residential charges, living expenses, transportation, insurance and school supplies, depending on the lender’s policies. But loan amounts, interest rates, security needs, and other conditions of repayment differ depending on the lender, borrowed sum, course and university, and profile of the applicant. New Zealand is very diverse in studying costs based on programme, institution and lifestyle. Thus, the first step that students must take is to figure out their funding need and the amount that their family can contribute. This guide outlines how to get secured and unsecured loans, conditions of the loans offered by the university in New Zealand, visa financing expectations, sub-documents, comparison with other lenders, and repayment considerations to help students and parents make good decisions to finance their education before they apply for funding their school education.
Check out: Study in New Zealand
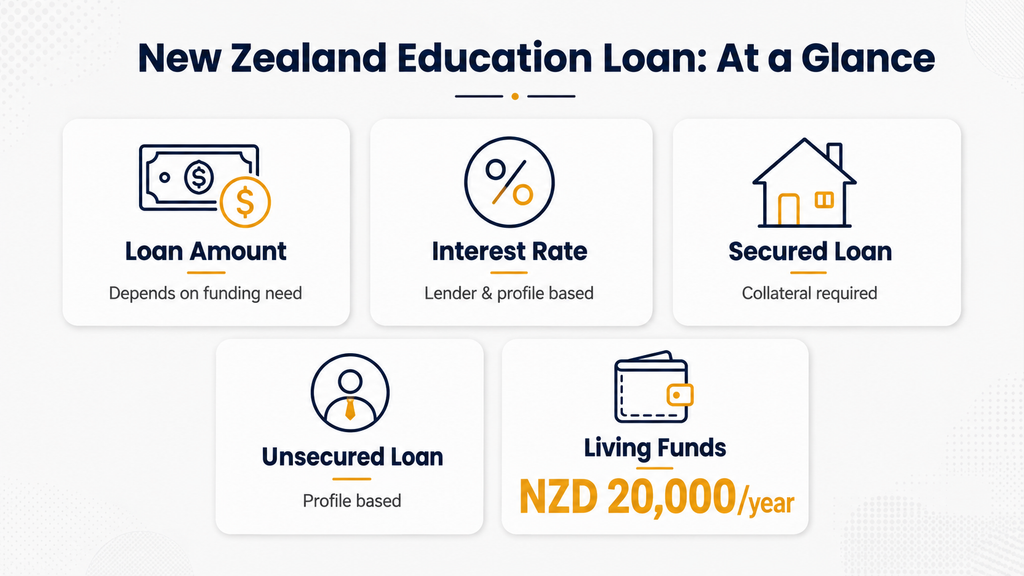
Education loan for New Zealand study India: At a Glance
| Factor | What to Know |
| Loan value | Depends on the funding need and evaluation by the lender. |
| Interest rate | Depends on the lender, amount and profile of the applicants. |
| Secured loan | Needs collateral approved by the lender. |
| Unsecured loan | The loan is mainly evaluated based on student and co-applicant profiles. |
| Living funds | INZ is now in need of NZD 20,000 annually to cover tertiary students. |
| Factor | What to Know |
Approach to Education loan for New Zealand study India application: It should then start with your actual funding shortfall and not with the maximum advertised amount by a lender.
Determine the cost of studying in New Zealand.
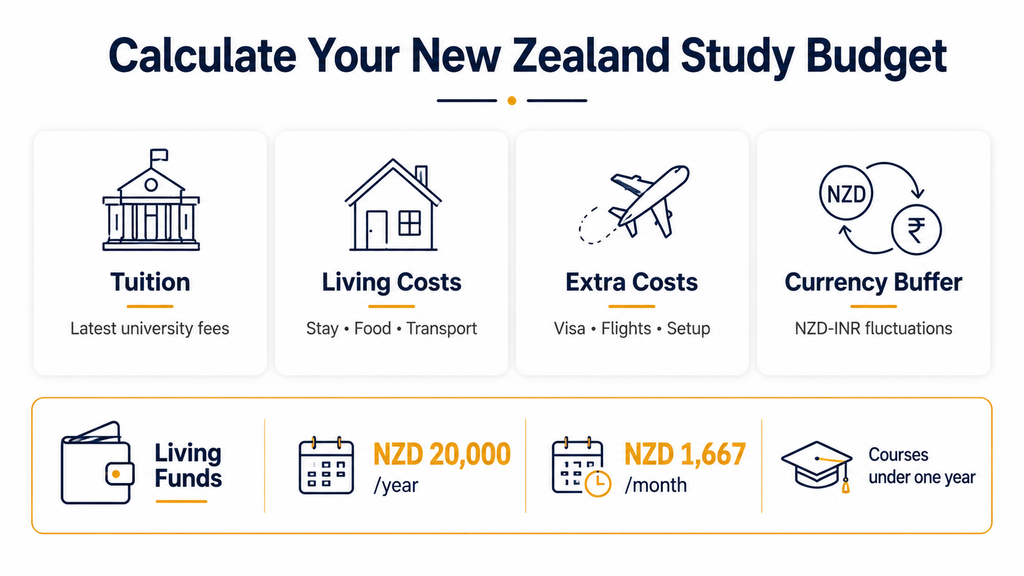
The tuition fee of studying in New Zealand includes much more than tuition.
Budget entails:
- Divide tuition by the most recent published fee schedule of your university.
- Add accommodation, food, transport, insurance, book costs, and equipment costs.
- Blacken flight, visa and first settlement.
- Keep a currency reserve against any fluctuation in NZD-INR exchange rate.
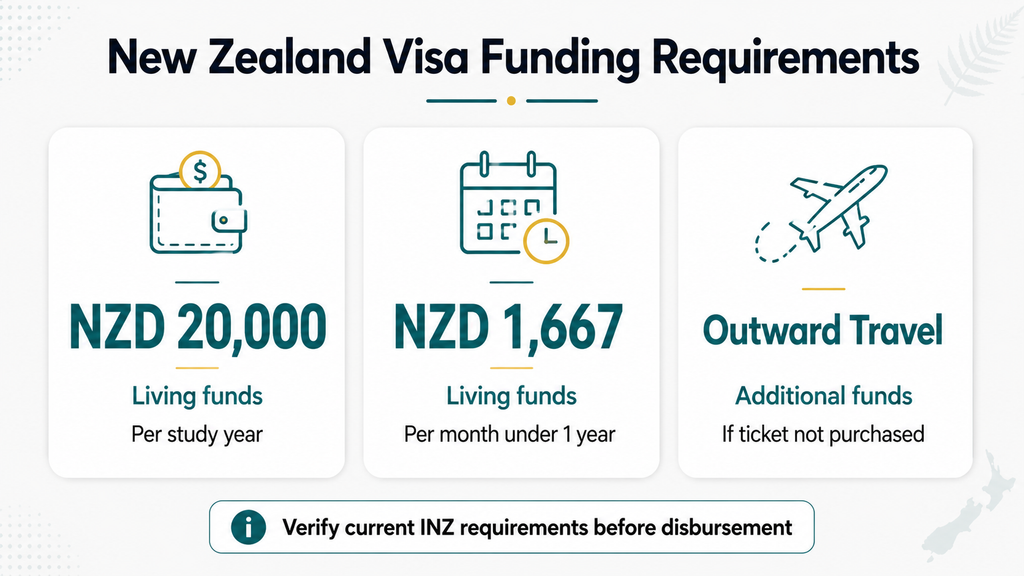
Immigration New Zealand now demands that tertiary students demonstrate NZD 20,000/year or NZD 1,667/month in case of courses less than one year and outward travel expenses, where necessary.
Thus, the Education loan for New Zealand study India must be the computed cost of a real university fee and affordable cost of living.
Budgeting Rule: To budget your whole programme, count up all the costs, not just the tuition in the first year.
Read out: Study Abroad Budget Guide 2026: Total Costs, Scholarships & Loan Guide
Calculate How Much Education Loan You Actually Need
Now that you have an idea of the cost of studying in New Zealand, establish your funding shortfall:
Total programme cost – scholarships – affordable family contribution = estimated loan requirement.
Students must not borrow without necessity, just because an expedited sanction might be possible.
- Determine an achievable family contribution without influencing the basic family funds.
- Subtract confirmed scholarships and then compute the amount of loan that you need.
- Keep an emergency fund rather than having to spend on all available family savings.
The Education loan for New Zealand study India you need must, in turn, represent actual educational costs and repayment ability.
Secured vs Unsecured Education Loans.
A student loan that is applied to the Education loan for New Zealand study India can be secured or unsecured.
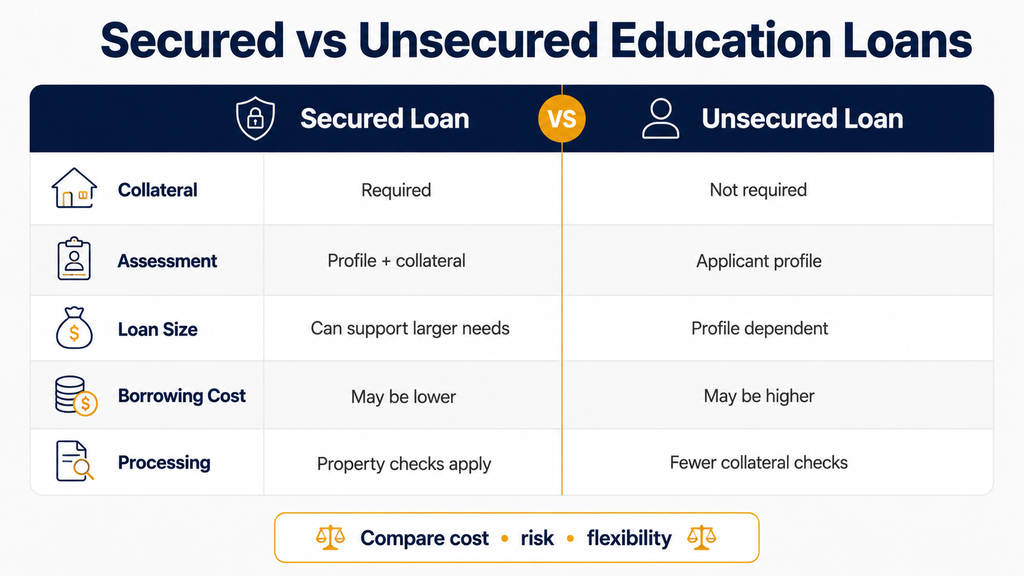
| Factor | Secured loan | Unsecured loan |
| Collateral | Required | Not required |
| Assessment | Profile and collateral along with applicants | Mainly, applicant profiles. |
| Loan size | Have the ability to sustain bigger needs | Strongly profile-dependent |
| Little cost of borrowing money | Can be relatively cheaper | Can be relatively more expensive. |
| Processing | Checks on property can be simplified | Less collateral formalities |
Secured Loans
The collateral will be in the form of residential or commercial property, fixed deposits, or any other collateral which is allowed by the lender’s policy.
Lenders may conduct:
- Checking of documents and property ownership legally.
- Valuation of property to establish reasonable value of security.
- Checks on mortgages or ownership in existence.
Unsecured Loans
The general dependence of an unsecured Education loan for New Zealand study India is based on academics, university, course, finances of a co-applicant, credit history, and loan amount.
Comparison of the two is based on borrowing cost, security risk, as well as repayment flexibility.
Check out: Education loan with collateral: How it works, what you can pledge, and how to apply
Know NZ University Loan Eligibility.
No universal NZ university loan eligibility rule is applicable to all the Indian lenders.
Student Factors
- The lender can be judged by academic performance and qualifications.
- The eligibility to take the loan may be influenced by the University, course, study level, and admission status.
- Career opportunities can affect evaluation, particularly for bigger unsecured loans.
Co-Applicant Factors
- Stability in income might affect assessment of repayment to be made by the co-applicant.
- There is a possibility that existing loans and repayment history will impact the overall financial eligibility.
- The credit history is important, but there is no CIBIL score that assures a loan.
Loan Factors
NZ university loan eligibility might be affected by the amount required, collateral, loan structure and repayment capabilities.
An Education loan for New Zealand study India must hence be assessed on the basis of the entire student and financial report.
Banks vs NBFCs: What to Compare?
Interest rates are not a sufficient criterion to select lenders when students look for Education loan for New Zealand study India solution.
Interest rates could vary based on the lender and could be based on:
- The amount of loan requested may influence the pricing of the lenders, security and credit ratings.
- In the case of unsecured education loans, university and course choice may make a difference in eligibility.
- The quality of collateral may have an impact on secured-loan eligibility and on the terms of borrowing.
- Lenders may consider Co-applicant income, credit history and liabilities.
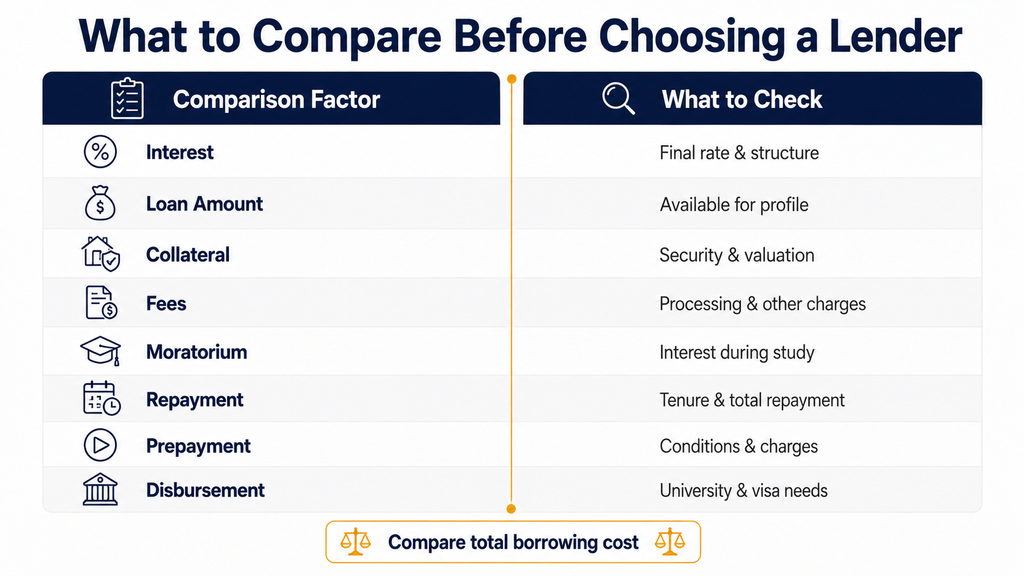
| Comparison Factor | What to Check. |
| Interest | Final structure and rate. |
| Loan amount | Available on your profile. |
| Collateral | Security and valuation terms. |
| Fees | You are being charged processing fees as well as other charges. |
| Moratorium | Treatment of interest as a part of study. |
| Repayment | Repayment term and approximate total repayment. |
| Pré-payment | Conditions/charges. |
| Disbursement | University and visa requirements. |
Checking on Interest rates: The advertised rate is not necessarily the rate given to all applicants.
In the case of the Education loan for New Zealand study India, consider the final applicable interest rate and total cost of borrowing as opposed to the general interest rate in the market.
Read out: Education loan without collateral: Eligibility, lenders, costs, and application steps
Understand New Zealand Visa Funding Requirements
Visa financing is also important in making an Education loan for New Zealand study India decision.
Tertiary students normally have to demonstrate, under the present Immigration New Zealand requirements.
- Sufficient available living funds, NZD 20,000 during each year of study.
- NZD 1,667 each month in programmes that take less than one year.
- Extra money to travel abroad in case a satisfactory ticket is not already bought.
Depending on the source of funding and the situation of the application, INZ will take some evidence of education loans as financial evidence.
Indian students ought to confirm the new financial evidence requirements by INZ before organising loan payment.
This renders visa compatibility with the selection of an Education loan for New Zealand study India.
What Is the Funds Transfer Scheme?
Immigration New Zealand supplies the Funds Transfer Scheme, or FTS, operated by ANZ Bank New Zealand.
INZ decides when applicants should apply the scheme.
| FTS Factor | Standings. |
| Maintenance value per person in a year | NZD 20,000 for tertiary study. |
| Tuition included | No |
| Bank | ANZ Bank New Zealand. |
| Visa guarantee | No |
Through FTS, students send their own necessities back home, and their living expenses. Money is later to be discharged periodically on living costs as per the scheme.
Studying in New Zealand in India could therefore need a well-thought-out disbursement plan when finances are to be spent on tuition and visa applications.
Documents needed for education loans.
The processing and eligibility for NZ university loans can be affected by documentation.
Student Documents
- Passport and other relevant identity documents.
- Academic marksheets, certificates and transcripts.
- University admission or letter of admission.
- Course and fee details.
Co-Applicant Documents
- ID and address cards.
- Paychecks or income attestations.
- Where necessary, documents on income tax.
- Bank and employment history.
Collateral Documents
Title documents, ownership documents, property certificates, tax receipts and other documents requested by lenders may be needed as a security to the application.
The precision of an Education loan for New Zealand study India depends on the lender and applicant profile.
Prior to Application: Keep information the same as in your loans, university applications, income statements and visa applications.
Know about Sanction, Disbursement and Repayment.
The borrower of an Education loan for New Zealand study India should know that sanction and disbursement are not the same.
- Loan sanction: The lender grants the funding with supported terms and conditions.
- Loan disbursement: The lender literally disburses approved loans upon fulfilment of country-specific conditions.
The repayment planning is also crucial.
- Inquire about the interest, in case it is accrued throughout the study period and both repayment moratoriums on your loan.
- Look at the longer term repayment periods against their possible higher total repayment interest cost and then choose the most comfortable one.
- Be aware of prepayment terms prior to borrowing since timely repayments can go a long way in lowering your ultimate interest payment obligation.
An Education loan for New Zealand study India ought to be compared with the estimated total repayment, and not just the starting EMI.
Common Mistakes to Avoid
- Estimating tuition alone up to New Zealand would underestimate the cost of studying in this country.
- Fees, repayment terms, moratorium and other costs of borrowing can be ignored in the mere comparison of interest rates.
- It is also possible to borrow more money than you need, and this would raise the amount of money you have to pay back when you are done studying.
- Violation of the visa provisions may cause issues in proving satisfactory financial evidence to Immigration New Zealand.
- Conflation of sanction with disbursement may lead to wrong expectations regarding the time of availability of approved education-loan funds.
- The neglect of moratorium interest will augment the un-recovered balance of the loan to be paid later in the form of normal EMI repayment.
- There may be a risk of making assumptions about unsecured eligibility since the eligibility of NZ university loans varies on the basis of a number of factors.
- Late application might result in the lack of time to properly assess the loan, prepare the paperwork and verify collateral and visa.
Responsible Borrowing for New Zealand
When considering taking an Education loan for New Zealand study India, consider whether the burden of borrowing is within your financial capability.
| Reason | Why it matters. |
| To what extent should I borrow? | Prevents unnecessary debt |
| What happens during moratorium? | Identifies interest accumulation |
| Some possible total repayment? | Helps assess affordability |
| Is collateral involved? | Recognises family asset exposure. |
| Will my family be a safe contributor? | May reduce borrowing |
| Would currency movements have an impact on costs? | Identifies exchange-rate risk |
The appropriate Education loan for New Zealand study India package must be appropriate to your actual funds needs and your actual ability to repay.
Parent Tip: Students should never pick a loan only because it has the largest approved sanction or that it has the longest repayment period.
How Can Foreign Edu Loans Help?
Foreign Edu Loans can assist students who are looking at an Education loan for New Zealand study India by making lender comparison and applications easier.
- Foreign Edu Loans can assist students in finding appropriate education-loan programs depending on their education and financial backgrounds.
- Learners are able to rank competent banks, NBFCs and other institutions that disburse educational funds based on their respective financing needs.
- The site can help students compare secured and unsecured loans on the basis of availability of collateral and eligibility.
- Individuals may be helped with the paperwork and application-arranging as students are approaching the appropriate education-loan assistants.
- Foreign Edu Loans should allow students to learn about the terms of loans before they enrol in their choice of a lender.
The ultimate approval, interest rates, terms of the loan and the sum of the loan are all in the hands of the pertinent lender.
FAQs
What is the extent of Education loan for New Zealand study India?
There is no standard amount. Eligibility will be based on the cost of the university, requirement of the loan, lender policy, collateral, course, and profile of the applicant.
Would I be able to study in New Zealand with an unsecured education loan?
Yes, students can qualify who are sufficiently well. Academics, university, course, amount of loan, income of co-applicants and credit history are what lenders look at.
What defines the eligibility to borrow loans through the NZ universities?
The eligibility of loan implementation in NZ universities is based on academics, admissions, university, course, funding requirement, co-applicant profile, credit, and collateral.
Is living expense included in an education loan?
An Education loan for New Zealand study India will be allowed to cover approved living accommodation, travel, equipment and tuition (based on the policy of the lender).
How much does it cost to study in New Zealand?
The cost of studying in New Zealand depends on the university, programme, city, accommodation, lifestyle, and other education-related costs.
Do all Indian students have FTS?
No. The Funds Transfer Scheme is optional and is decided upon by Immigration New Zealand as it applies to a specific student visa application.
Would I go with the lowest rate lender?
Not automatically. Authorise the ultimate achievable rate, service fees, security, moratorium, repayment term, prepayment terms and disbursement terms.
Conclusion
An Education loan for New Zealand study India must commence with proper budgeting as opposed to as much funds as it can get. Estimate both your entire programme costs, family contribution and actual funding deficit and compare lenders.
Then consider secured and unsecured loans, visa policies, collateral, charges, moratorium terms and loan amounts. Interest rates cannot be a one-shoe-fits-all since the rate that applies may vary depending on the lender, amount of loan and the profile of the loan applicant.
An education loan must help fund your education without causing needless debts. Check the existing university expenses, Immigration New Zealand compulsory fees, lender conditions and authenticate them before proceeding.
Find your education loan options to apply to find out what options are available to you depending on your study and funding eligibility.