After senior secondary (Class 12), Indian students are eligible to get education loan for undergraduate studies abroad as long as the application passes the academic, financial and credit criteria of the lender. The usual evaluation criteria used to analyse a UG loan India application are the admission, school background, college, course, country, amount required, strength of co-applicant and available security. A bachelor’s degree abroad loan can be either secured (with collateral) or unsecured, and depending on the lender’s product, it may cover costs beyond tuition alone.
Loan balances, rates, margin, security, and payment and charge terms are subject to change. Last charges vary on the policy of lenders and profile of the applicant.
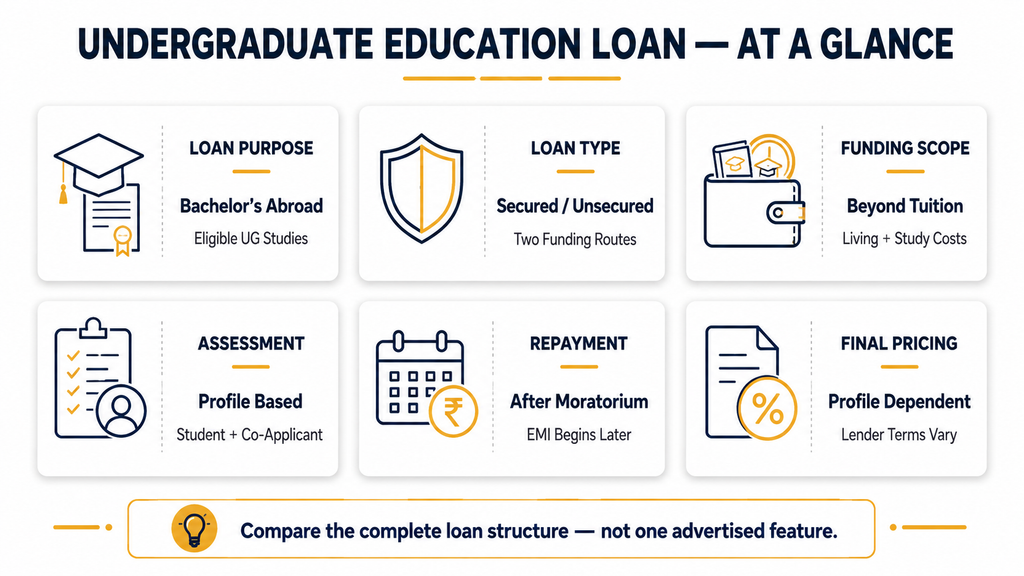
At a Glance: Education loan for undergraduate studies abroad
| Factor | What students need to know. |
| Loan purpose | Coverage of education loan for undergraduate studies abroad (bachelors or other eligible). |
| Loan type | In secured loans: Approachable collateral is used; in unsecured loans: It is more dependent on the profiles. |
| Funding scope | Accommodation, books, tuition, travel and approved academic costs may be eligible. |
| Applicant assessment | At the level of lenders, the student, university, course, country, co-applicant and amount requested are measured. |
| Repayment | EMI will usually start after the course and moratorium terms. |
| Final pricing | The rate used is determined based on the lender, product, amount, security and the borrower profile. |
An education loan for undergraduate studies abroad must not in any respect be rated on the basis of a single aspect advertised.
Is it possible to take an education loan for undergraduate studies abroad in Class 12?
Yes. Indian lenders facilitate eligibility for undergraduate programmes abroad which are financed by Indian lenders, but this does not necessarily mean objections to sanctions.
SBI Global Ed-Vantage scheme now subsidises regular foreign courses of full-time duration, and publishes allowances of over 7.5 lakh to 3 crore. The Bank of Baroda also offers its Baroda Scholar scheme that provides rates on eligible courses at the graduation level abroad, as required by products.
In case of a UG loan India application, lenders can look at:
- You must have a history of preparedness for the chosen overseas programme in your academic work.
- The offer letter to you has to specify the university, the course and the applicable tuition.
- Your co-applicant ought to have recorded earnings and viable current repayment packages.
- The amount that you ask for should be realistic in terms of cost of studying and family contribution.
- Your collateral should meet lender requirements in applying for secured financing.
A 12th pass student’s loan to study overseas is thus feasible without having a previous work record. Lenders pay close attention to the co-applicant and educational background.
Read out: Education Loans For India and Abroad
How to Get an Education Loan for Undergraduate Studies Abroad: Step-by-Step Process
Step 1: Estimate Before Selecting a Loan: Calculate the Complete Cost.
The education loan for undergraduate studies abroad will take multiple years before completion, making tuition fees not sufficient.
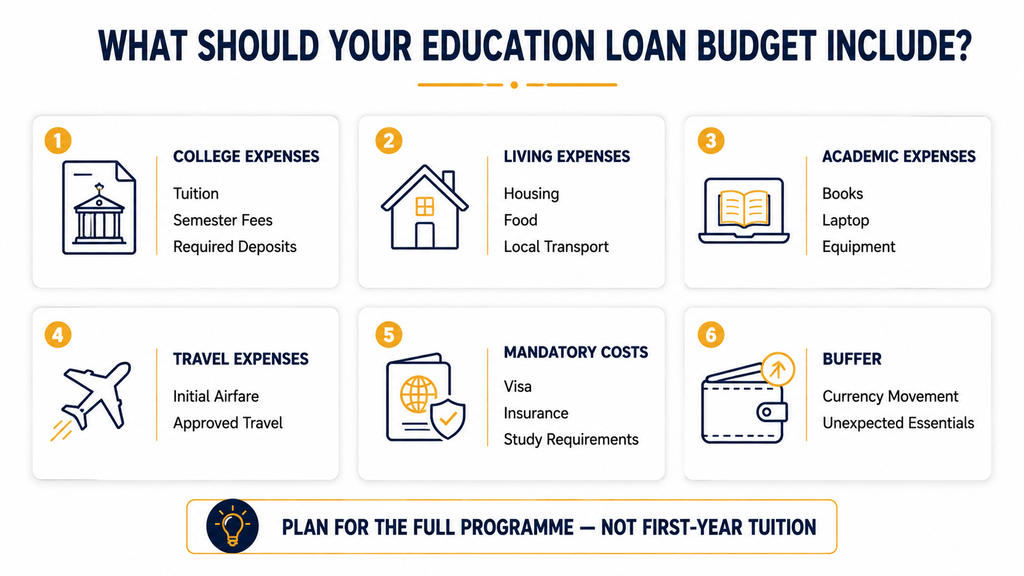
| Cost category | Examples to budget. |
| College expenses | Tuition, semester fees, laboratory fees and required institutional deposits. |
| Living expenses | Housing, meals, electricity and local transportation, personal necessities. |
| Academic expenses | Books, laptop, equipment, examination expenses and any project expenses. |
| Travel expenses | First air fare and expenses on travel which are sanctioned by the lender where the product allows. |
| Resistance expenses | Visa, insurance and other mandatory study-related expenses where applicable. |
| Buffer | A reasonable amount of money to move around and unexpected necessary costs. |
The list of non-tuition costs that both SBI and Bank of Baroda note as being eligible loan usage depends on the product, but both include a range of these costs. A loan to fund a bachelor’s degree in a foreign country is thus supposed to be on the complete programme budget.
Budgeting Rule: Compare total monetary resources of all academic years, not just first-year tuition.
Step 2: Choose Between Secured and Unsecured Financing
An education loan for undergraduate studies abroad which can be secured using collateral approved by the lender or be unsecured.
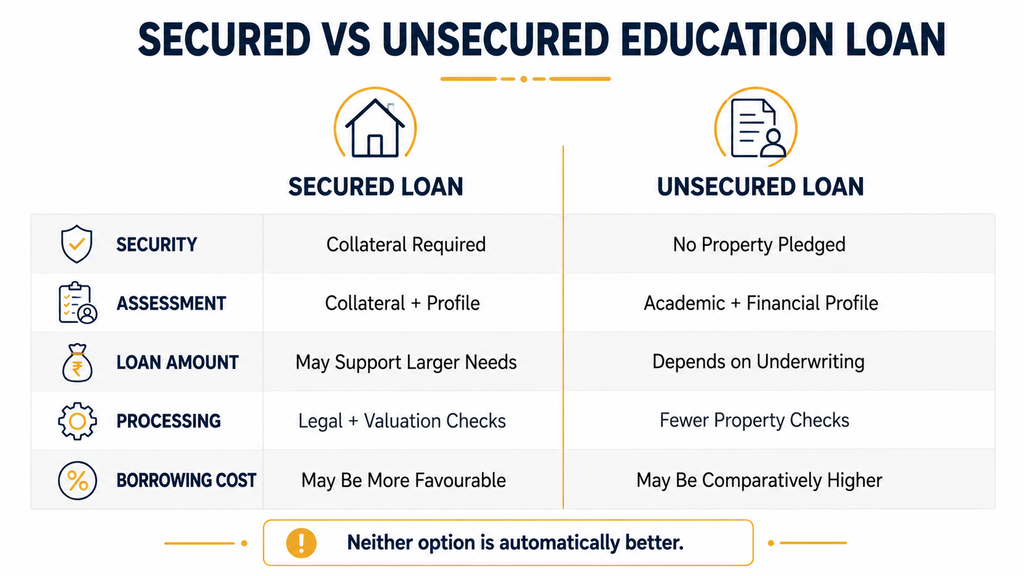
| Indicators | Secured loan | Unsecured loan. |
| Security | Needs of acceptable collateral pursuant to products regulation. | There is no collateral of property pledged. |
| Assessment | Considers collateral as well as student and co-applicant profiles. | Leverages greatly on academic, University and Co-Applicant profiles. |
| Loan amount | Will be able to finance larger needs in case of adequate security. | The lender underwriting and the quality of profile are critical factors in limits. |
| Processing | This may involve more stages with legal and valuation. | The decreased number of property verifications can streamline the documentation. |
| Cost of borrowing | May be granted relatively favourable prices on qualifying profiles. | The reason can be greater pricing due to less security provided by the lenders. |
Unsecured financing is not necessarily better assumed by the applicants. The invested structure could be used in the case of four years of funding that is required to be safe in case there is no issue with the security.
Step 3: Understand Why the Co-Applicant Matters
In the case of an education loan for undergraduate studies abroad, the co-applicant usually becomes very significant as the student might lack work history.
Lenders may consider:
- Family income history needs to show that the family can sustain their needed loan repayments.
- Verifiable financial documentation should be applied in establishing employment or business stability.
- There is an upper limit on the repayment capacity of the existing EMIs that can be used to engage in another borrowing obligation.
- Credit history can determine the approvals, terms and the ultimate pricing.
- Relationship requirements vary, and therefore ensure that you confirm with your lender on the family members granted.
Earnings and credit scores cannot be a sure thing for approval. Students studying in a foreign country who are 12th pass students will have to depend on the complete file and not on a single threshold of the loan.
Step 4: Check Eligibility Beyond Class 12 Marks
There are four areas that an education loan for undergraduate studies abroad is typically evaluated.
Student Factors
- Progression in the chosen bachelor’s programme should be supported by academic performance.
- English-language or entrance scores will be requested as needed for admission.
- The course and university must comply with the current policy of the current lender, with regard to eligibility.
Financial Factors
- The amount one requests should be equal to recorded living and education expenses.
- The portion that has to be financed can be modified based on the family contribution and scholarships.
- The availability of collateral may influence the appropriate structure of loans and the terms of sanction.
Lender Factors
- University lists may have an effect on unsecured eligibility and maximum permissible financing.
- Policies of the country and course over products and lending institutions may vary.
- Final approval is decided on by internal underwriters of all documentation after assessment.
The application is more effective in cases where academic choice and financial planning complement one another.
Step 5: Understand What Your Loan Can Pay.
The cost of an education loan for undergraduate studies abroad may include:
- The biggest financed part can be made up of tuition and mandatory university fees.
- Approved accommodation or hostel costs may be allowed as eligible living expenses.
- There can be books, equipment and laptops, which can be required to complete the course.
- The cost of travelling can be met with a special authorisation in lender policies.
- Deposits that are necessary and insurance could also be deemed as befitting product requirements.
There is official SBI and Bank of Baroda product information stating that overseas education financing can go beyond tuition and that the actual eligible-expense list is product-specific.
Step 6: Compare Interest Vs Total Borrowing Cost.
Do not take an education loan for undergraduate studies abroad at a single quoted. The cost may vary between different lenders, size, security, institution, user base and benchmark.
It is particularly critical as the rate given to a particular borrower will eventually be different as compared to the one given to another borrower, regardless of the fact that they are approaching the same lender.
Give the comparison of the following items instead:
- Before comparing the products, determine whether the rate is fixed, floating or is linked to a benchmark.
- Discuss the treatment of interest in the course and moratorium period.
- Evaluate processing, legal, value, insurance and all other charges apart.
- Knowledge of whether there is a restriction or a charge on early repayment on your product.
- Compare estimated repayment total and not just the initial EMI shown.
According to SBI, simple interest is charged when enrolled in the course and moratorium under Global Ed-Vantage, where accrued interest will be added before repayment of the EMI is made. The Bank of Baroda also mentions that simple interest will be applied when its Baroda Scholar is on repayment holiday.
Interest rate Check: You should always get the prevailing lender’s quote on a particular loan amount and profile.
Check out: Star Education Loan – Studies Abroad
Step 7: Prepare the Complete Document File
A comprehensive UG loan India application will help minimise unnecessary delays.
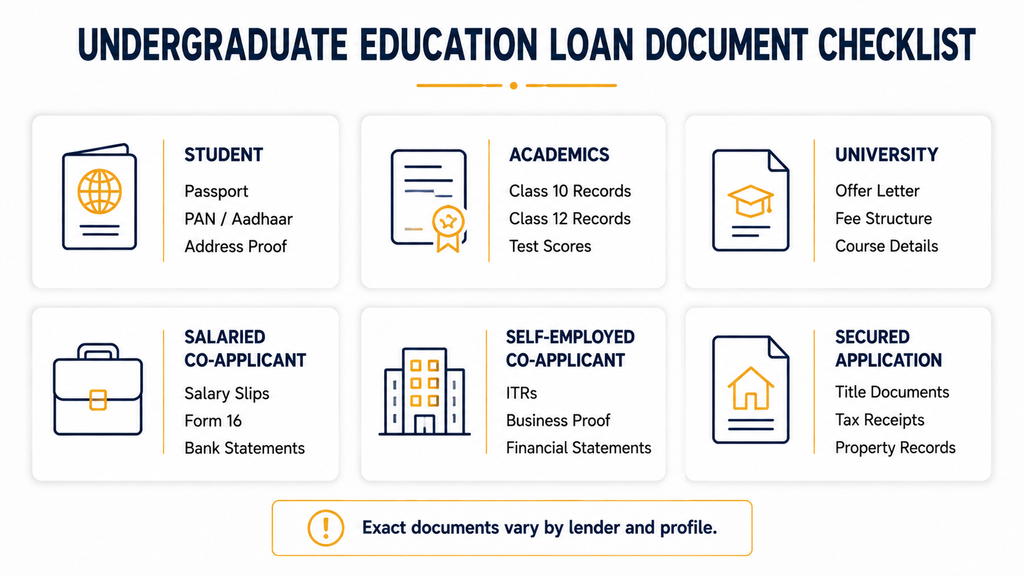
| Applicant | Samples of popular documents asked for. |
| Student | Passport, PAN /Aadhaar (where necessary), photographs and address proof. |
| Academics | 10 and 12 certificates, records and any applicable test scores. |
| University | Offer letter, fee structure, course content and admission confirmation. |
| Salaried co-applicant | PAN, salary slips, Form 16, bank statements and employment records. |
| Self-employed co-applicant | ITRs, bank statements, business proof and financial statements. |
| Secured application | Title documents, tax receipts as well as property records as requested by lenders. |
The lender might demand more documents according to the applicant, collateral, university or destination.
Step 8: Follow the Loan Process in the Correct Order
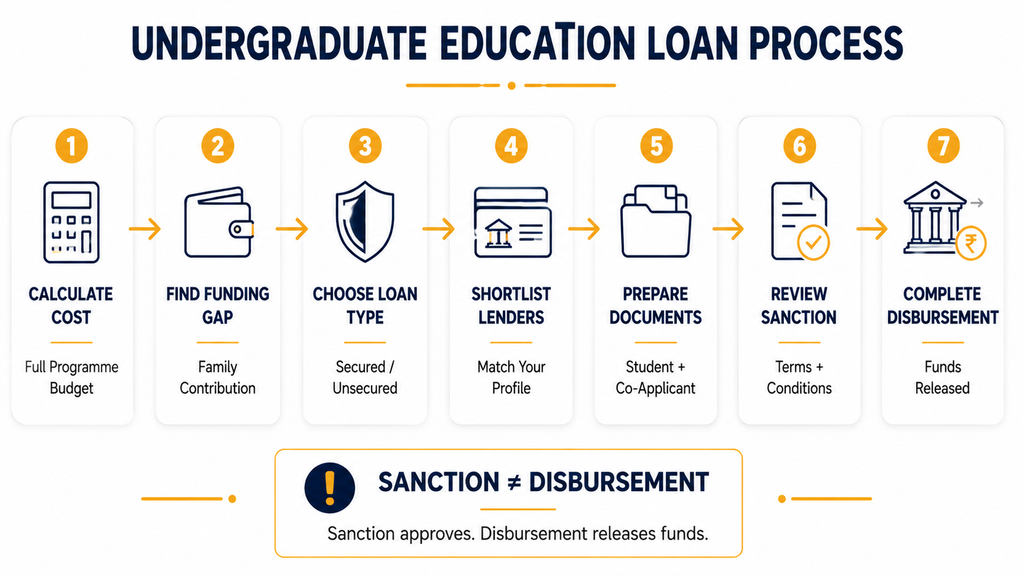
To get an education loan for undergraduate studies abroad, follow this order:
- Divide the information on the entire cost of the course and the contribution of the family.
- Determine the amount to be actually financed and the preferred route, whether supernatural or not.
- Filter lenders based on your university, course, country and amount requested.
- Prepare student/co-applicant/financial and collateral documents as needed.
- Apply and complete applications and lender verification requests on time.
- Read the letter of sanctions, terms, margin and repayment schedule.
- Full disbursements prior to university payment due dates.
No disbursement is sanctioned. Sanction grants financing under conditions; disbursement grants approved funding.
A loan for a bachelor’s degree in a foreign country can either be released on a semester basis or on the basis of the university requirements.
As an example, Bank of Baroda mentions that the payments that are qualified can be provided directly to institutions in portions based on the needs.
Step 9: Learn about Moratorium and Repayment Before Departure
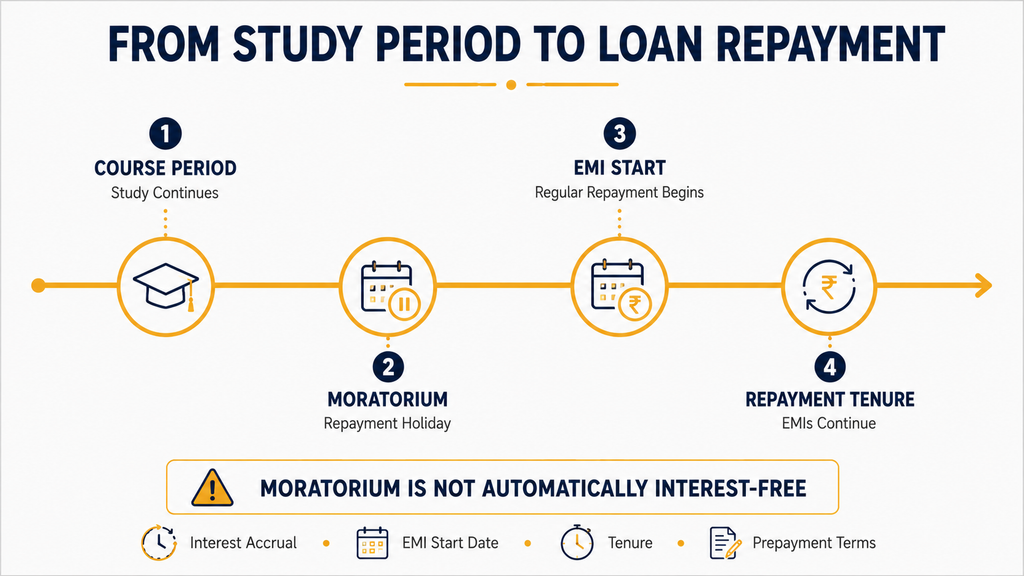
A typical education loan for undergraduate studies abroad does come with a set period of repayment holiday, although this does not necessarily imply a no-interest loan.
According to SBI, its overseas education repayment program, Global Ed-Vantage, starts six months following the completion of a course, and repayment can be made for a maximum of 15 years. According to the Baroda Scholar of Bank of Baroda, the period of the course plus 1 year is the repayment holiday, and the maximum repayment period is 10-15 years, according to the loan slab.
Before signing:
- Ask when interest begins to be accrued and what happens to the accrued interest at repayment.
- Establish the date on which regular EMI commitments start on your approved product.
- Compare long and short tenures in terms of total repayment and not EMI.
- Realise prepayment terms prior to strategising early and aggressive repayment.
Paying back Tip: The tenure will be greater, and this is likely to decrease the amount of EMI but increase the repayment.
Tax Treatment Families Should Verify
Section 80E gives an interest deduction of 100% of the interest on a qualifying education loan as far as the loan is repaid, either over 8 years of interest, or a maximum number of eligible interest, whichever is less. This is only deductible under filing under the old tax regime only and cannot be deducted under the new (default) tax regime brought about under Section 115BAC. Such a benefit is usually available to those families who have to make sure that they are filing under the regime that they are currently in before they assume that they are receiving the benefit since the majority of taxpayers now find themselves automatically under the new regime filing regime.
There is a similar change in overseas remittances. It is no longer subject to the 0.5% TCS originally imposed in case of education loan proceeds above 7lakh proceeds remitted abroad through a designated financial institution -that TCS is not applicable to loan-based remittances. It is important to note that TCS regulations on education remittances have been subject to constant changes; therefore, one needs to verify the current rate with his/her bank or tax advisor and not to use the previous rates to remit.
Common Mistakes to Avoid
These are the mistakes to avoid by students who are planning to use a education loan for undergraduate studies abroad:
- Borrowing on tuition in the first year and overlooking the residual programme and cost of living.
- Comparison of lenders based on the advertised rates without evaluating the complete cost of borrowing.
- It will come with the assumption that all unsecured applications get the highest amount advertised on the internet.
- Disregarding co-applicant liabilities until the lender starts its credit assessment.
- Began documentation with excessively little time to complete (before university deposit/visa deadline).
- Compensating the moratorium like a free interest-free period of study.
- Mixing loan sanction with actual disbursement of money to the university.
- Making the choice of the maximum tenure without knowing the extra accumulated interest.
The decision of an education loan for undergraduate studies abroad must be affordable, valuable and realistic to pay.
How Foreign Edu Loans Can Help.
Foreign Edu Loans facilitate students to gain knowledge on eligibility, comparison of appropriate financing plans and documentation.
In the case of an education loan for undergraduate studies abroad, it may be assisted by:
- Comparison of secured and unsecured loans based on the financing need of the student.
- Considering co-applicant, university and course considerations to potential lender eligibility.
- Arranging application documents prior to the filing of files to the lender.
- Assisting students to learn about the conditions of the sanctions, the requirement of disbursement and repayment structure.
- The comparison and support of applications should be provided by Foreign Edu Loans; final errors of credit are made by the respective lender.
- Assess your eligibility for an education loan for undergraduate studies abroad.
Know what possible financing options are available to you based on the course, university, funding requirement and profile of your co-applicant(s).
FAQs
Will I be able to get an education loan for undergraduate studies abroad country right after Class 12?
Yes. Students with reasonable admission to a good undergraduate programme abroad can apply. Academics, institution, course, destination, requested amount, co- applicant finances and collateral, where applicable, are examined by the lenders. There is no automatic approval.
Is it possible to take out a bachelor’s degree abroad loan without security?
Potentially, yes. Unsecured eligibility is based on the current policy, university, course, country of the Lender, the amount perceived and the co-applicant profile requested. Analyse the overall cost to make a decision on unsecured financing.
Is a working student necessary in an application for a UG loan in India?
No, Undergraduate applicants often do not have any record of employment. Lenders, however, give more emphasis on academics, quality of admission, co- applicant finances and, in case of collateral availability, collateral.
What is a typical loan of 12th pass students studying in a foreign country?
It can include tuition, accommodation, books and equipment, travel, insurance and allowable academic costs depending on the rules of the lenders. Before budgeting, always review the approved list of eligible expenses.
How early should families apply?
Apply when admission information has come into place, leaving room to do documentation, assessment and any collateral checks.
Conclusion
Education loan for undergraduate studies abroad, which means that the student must plan seriously for a 4-year commitment after Class 12. Divide the total programme cost, determine the true financing shortfall, contrast secured and unsecured, co-applicant, knowledge in treating interest and reading the sanction terms, and as a borrower before you borrow, know the difference between the two.
It is important that a bachelor’s degree abroad loan not only be in support of an otherwise financially and academically sound plan, but be a maximisation of the approved amount. The terms of a loan by lenders to 12th pass students studying in overseas countries need to be compared by the family since the lending amounts of loans to students include current security and margin, payments charged and repayment policies which are liable to variation.
Verify Your Education Loan Eligibility and thereafter lock in on an option of a lender or a final borrowing structure.