If you are wondering what happens if you default on education loan, the consequences depend on how long payments remain overdue, your loan structure and the lender’s applicable rules. A missed EMI can affect your repayment record, while continuing default may lead to negative credit reporting, applicable penal charges and recovery action. For qualifying secured loans, enforcement of collateral may eventually become possible through the applicable legal process.
Nevertheless, an EMI miss does not entail property auction and settlement or restructuring is never automatic. And in case you start to have a problem with making the repayments, then call your lender, see what you owe and inquire what options you have that are specific to your account rather than turning a blind eye to the problem.
Check out: Education Loan Moratorium Period & EMI
Education Loan Default Consequences at a Glance
| Situation | Possible consequence | What to do |
| EMI missed | Payment becomes overdue | Contact lender and check dues |
| Continued irregular repayment | Credit history may be affected | Monitor your credit report |
| Loan terms breached | Applicable penal charges may arise | Check lender’s disclosed charges |
| Prolonged overdue | NPA classification may become relevant | Review applicable lender framework |
| Serious secured-loan default | Security enforcement may eventually become possible | Review formal notices carefully |
| Settlement accepted | Account may be reported as “settled” | Understand credit implications |
The education loan default consequences generally become more serious when repayment problems remain unresolved.
Read out: How to Apply for Education Loan for Abroad: Step-by-Step (2026)
What Happens When You Miss an Education Loan EMI?
Students often research what happens if you default on education loan after missing their first repayment.
A payment becomes overdue when it is not paid on its contractual due date. RBI guidance emphasises that repayment due dates and the breakup of principal and interest should be clearly specified in the loan agreement.
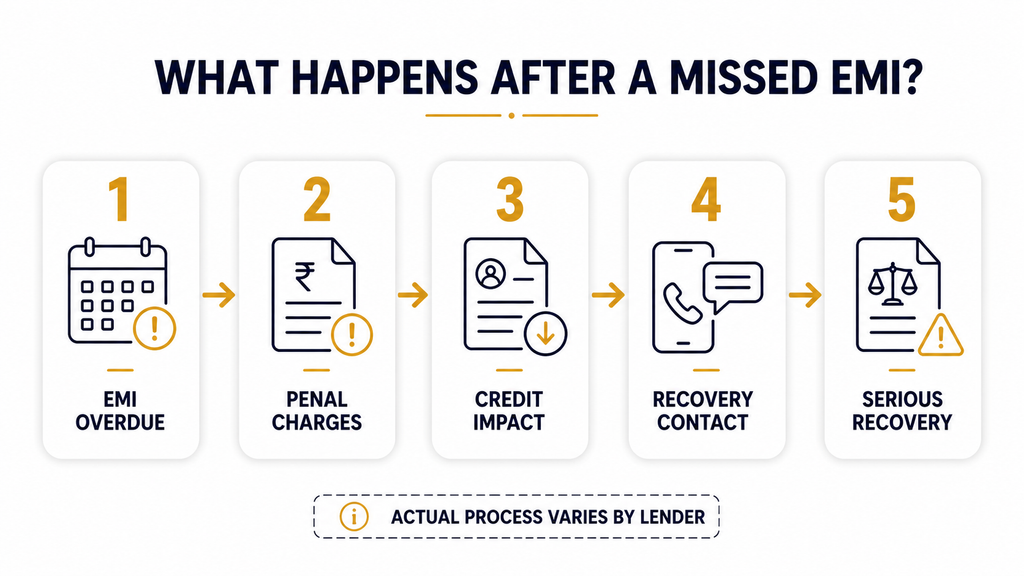
A repayment problem may progress through:
- EMI becoming overdue.
- Applicable penal charges arising.
- Repayment information affecting credit history.
- Collection and recovery communication.
- More serious recovery measures if default continues.
This is not a universal lender timeline. Actual procedures depend on the loan agreement, lender and applicable regulatory framework.
Read RBI’s official asset-classification guidance
How Many Missed EMIs Can Lead to Serious Action?
There is no responsible universal statement that a fixed number of missed EMIs automatically causes legal action.
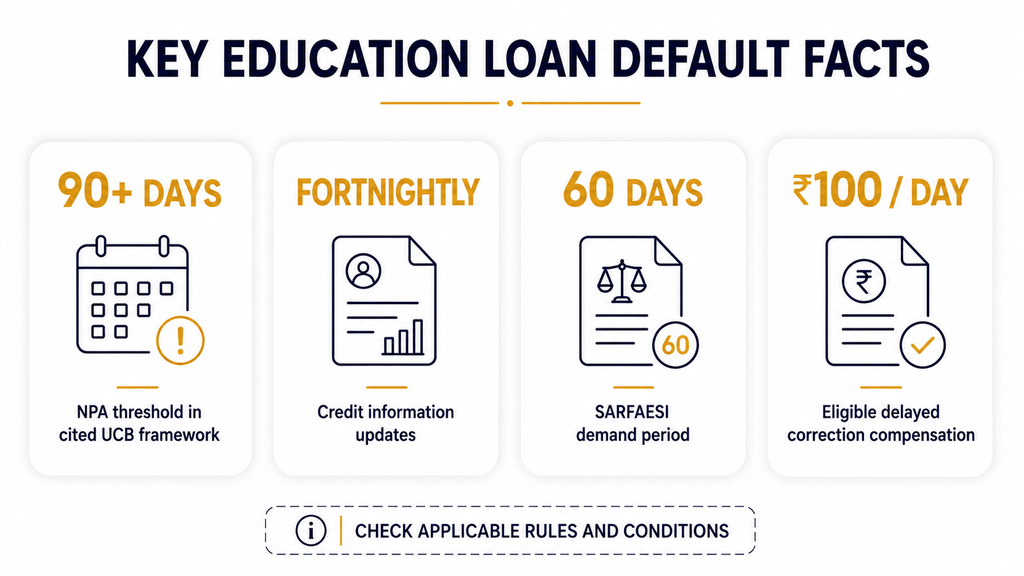
For example, the RBI Master Circular cited here specifically applies to Primary Urban Co-operative Banks (UCBs). Under that framework, a term loan becomes a non-performing asset when interest and/or an instalment of principal remains overdue for more than 90 days.
This UCB circular should not be used to claim that every bank, NBFC and education-loan product follows an identical operational process.
Therefore, when understanding what happens if you default on education loan, remember that NPA classification and legal recovery are separate concepts. The applicable framework for your lender must be checked.
What Is the CIBIL Impact of Education Loan Default?
The CIBIL impact of loan default is one of the most important long-term consequences.
TransUnion CIBIL explains that payment history is an important factor affecting the CIBIL Score and that late payments and defaults can negatively affect it.
Check CIBIL’s official credit-score guidance
However, there is no verified universal rule stating that one missed education-loan EMI reduces your score by a fixed number of points.
RBI has also required credit information to be updated on a fortnightly basis, as at the 15th and last day of each month, or at shorter mutually agreed intervals, with the revised frequency effective from 1 January 2025.
Read RBI’s credit-reporting requirements
This does not guarantee the exact date on which a particular missed payment will appear in your report.
Can Default Affect the Co-borrower?
Yes, depending on the person’s legal relationship with the loan.
This matters when considering what happens if you default on education loan with a parent or another person associated with the borrowing.
CIBIL credit reports recognise account ownership categories including individual, joint and guarantor. Students should therefore check the signed loan documents to understand who is legally responsible for repayment.
Read CIBIL’s credit-report guidance
The terms co-applicant, co-borrower and guarantor should not be assumed to be the same thing by law.
Is the Lender Allowed to Charge More on Late Payments?
Applicable penal charges may arise, but there is no universal education-loan default charge.
RBI’s Fair Lending Practice – Penal Charges in Loan Accounts framework states that penalties for non-compliance with material loan terms should be treated as penal charges, rather than being added to the interest rate as penal interest. RBI also states that penal charges should not be capitalised.
Read RBI’s penal-charges framework
Actual charges depend on the lender and product. Check your loan agreement and current schedule of charges.
Can a Lender Seize Property After Education Loan Default?
For borrowers asking what happens if you default on education loan secured by property or another eligible asset, the important point is that collateral is not automatically auctioned after one missed EMI.
The SARFAESI Act, 2002 provides a mechanism through which qualifying secured creditors can enforce security interests when statutory requirements are satisfied.
Under Section 13, where the applicable conditions are met, including relevant secured debt becoming an NPA, a secured creditor may issue a written demand requiring the borrower to discharge liabilities within 60 days before specified enforcement measures may follow.
Read the SARFAESI Act on India Code
Therefore, do not assume:
- One missed EMI causes immediate property auction.
- Every education loan qualifies for SARFAESI enforcement.
- A lender can ignore the applicable statutory process.
What Happens With an Unsecured Education Loan?
An unsecured education loan has no specific pledged collateral for the lender to enforce in the same manner.
But what happens if you default on education loan without collateral can still include negative credit consequences, applicable penal charges, collection activity and contractual or legal recovery where applicable.
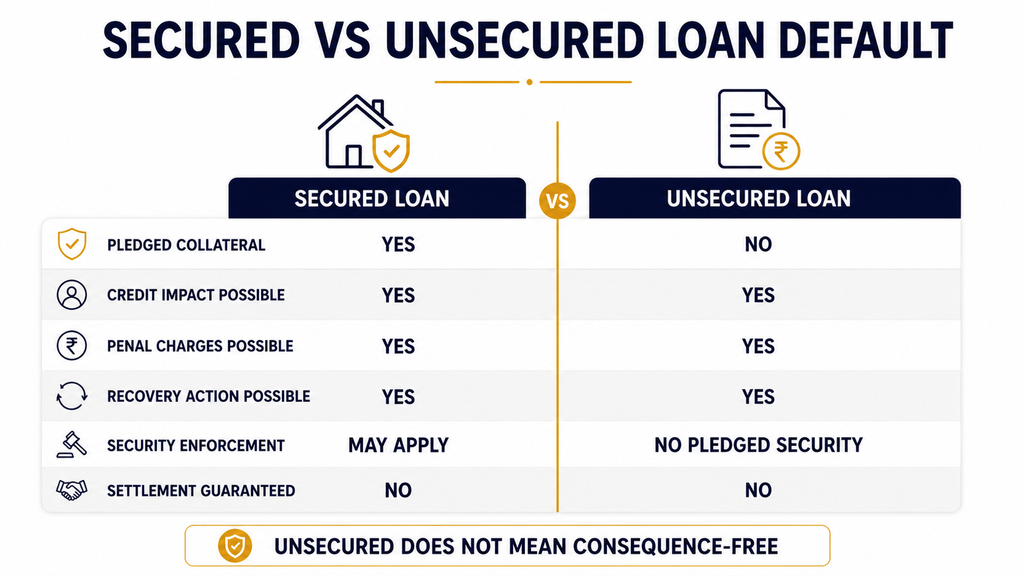
| Factor | Secured loan | Unsecured loan |
| Pledged collateral | Yes | No |
| Credit impact possible | Yes | Yes |
| Penal charges possible | Yes | Yes |
| Recovery action possible | Yes | Yes |
| Security enforcement | May apply if legal conditions are satisfied | No pledged security to enforce |
| Settlement guaranteed | No | No |
An unsecured loan therefore does not mean consequence-free borrowing.
Can Recovery Agents Harass You?
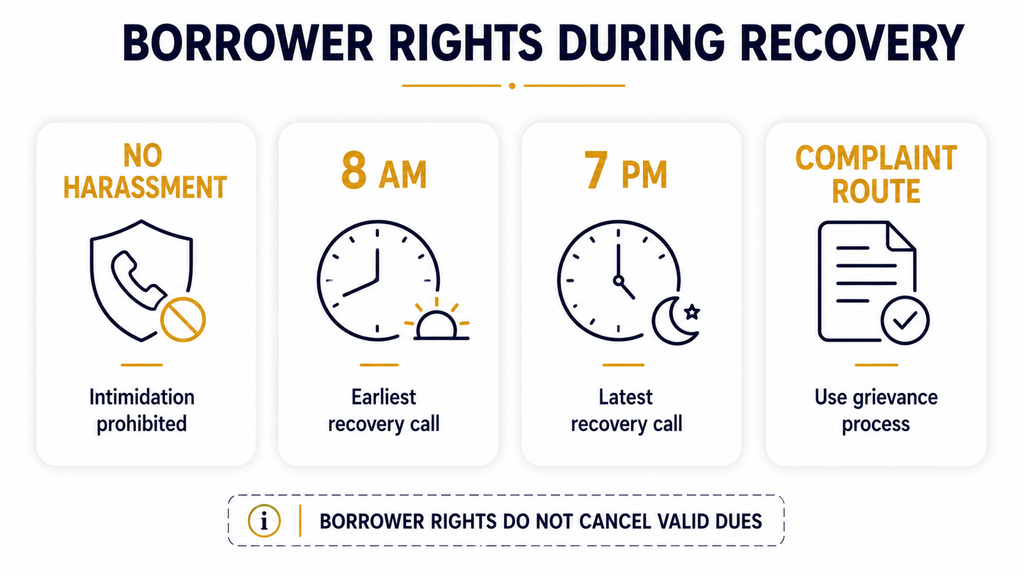
No. Default does not remove borrower protections against prohibited recovery practices.
RBI directions prohibit covered regulated entities and their recovery agents from practices including intimidation, harassment, public humiliation, privacy intrusion and threatening or anonymous calls. The applicable direction also restricts recovery calls before 8:00 a.m. and after 7:00 p.m.
Read RBI’s recovery-agent directions
These protections regulate recovery behaviour; they do not cancel a valid repayment obligation.
Can You Restructure an Education Loan?
When researching what happens if you default on education loan, restructuring should be treated as an option to ask about, not a guaranteed right.
Depending on the lender’s policy and circumstances, you can ask whether your account qualifies for:
- Repayment rescheduling
- Restructuring
- Changes to repayment dates
- Available hardship arrangements
- Other account-specific resolution options
The lender may need information about your financial difficulty, current outstanding amount and repayment capacity.
Do not assume restructuring automatically provides a lower EMI, longer tenure, additional moratorium, lower interest rate or waiver of overdue amounts.
Can You Settle an Education Loan?
Compromise settlement is a recognised resolution mechanism, but it is not guaranteed.
RBI’s Framework for Compromise Settlements and Technical Write-offs, issued on 8 June 2023, recognises compromise settlements for stressed accounts under Board-approved policies of covered regulated entities.
Read RBI’s compromise-settlement framework
The exact loan settlement options India borrowers receive depend on the lender’s policy and individual account.
Students researching what happens if you default on education loan should never assume that the lender must accept a proposed settlement amount.
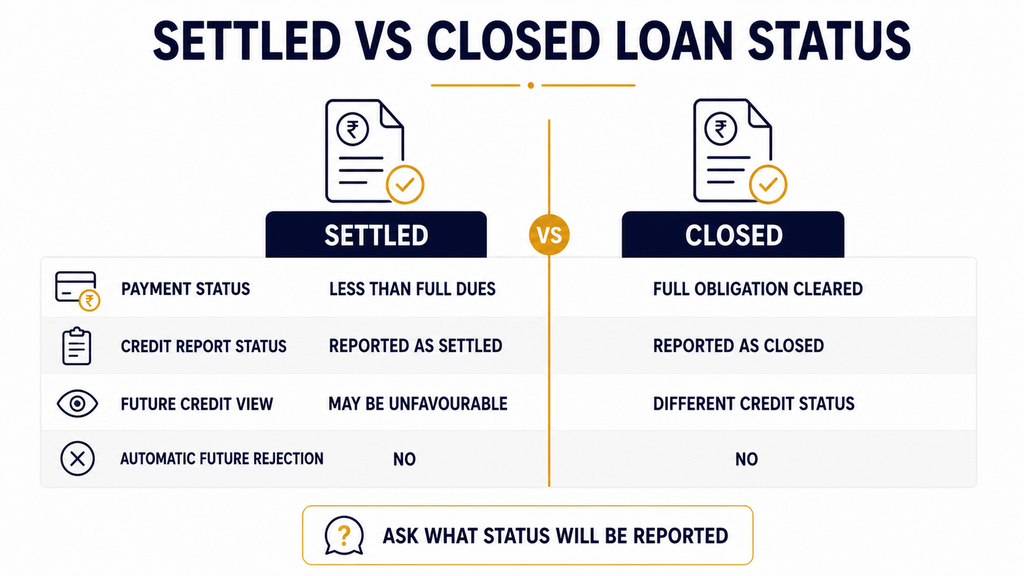
Is “Settled” the Same as “Closed” on CIBIL?
No.
CIBIL explains that where the borrower pays an amount lower than the complete amount payable under an agreed settlement, the account may be reported as “settled” rather than “closed.”
CIBIL also explains that a settled status may be viewed unfavourably by lenders considering a future credit application.
Read CIBIL’s explanation of settled status
This does not mean every future credit application will automatically be rejected.
Before accepting a settlement, ask the lender what account status will be reported after payment.
A technical write-off should also not be confused with debt forgiveness. RBI defines it as an accounting treatment that does not itself waive the lender’s claim against the borrower.
Read out: Public Bank vs Private Bank vs NBFC Education Loan: Which Is Best for Your Loan?
What Should You Do If You Cannot Pay Your Next EMI?
If you are researching what happens if you default on education loan because you expect repayment trouble, take practical action early.
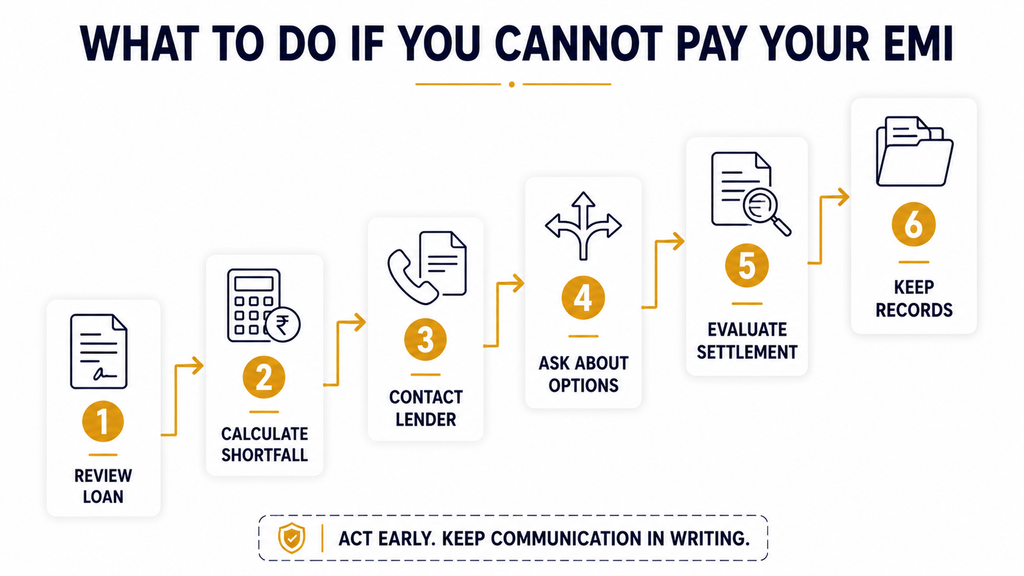
1. Review your loan agreement
Check the EMI date, outstanding amount, charges, security terms and repayment responsibilities.
2. Calculate the shortfall
Understand whether the problem is temporary or whether the existing repayment schedule has become unaffordable.
3. Contact the lender
Explain the situation and, where possible, maintain written communication.
4. Ask about available options
Ask whether restructuring, rescheduling or another resolution option is currently available for your account.
5. Evaluate settlement carefully
If settlement is proposed, understand the amount, deadline, remaining liability and credit-report treatment.
6. Keep records
Preserve payment receipts, emails, notices, settlement documents and closure or no-dues documents.
What If Your CIBIL Report Is Incorrect?
Understanding what happens if you default on education loan also requires separating genuine repayment problems from reporting errors.
RBI’s credit-information correction framework provides for ₹100 per calendar day compensation in qualifying cases where a complaint is not resolved within 30 calendar days, subject to applicable conditions and responsibility allocation.
Read RBI’s credit-information correction framework
A dispute process is for correcting inaccurate information. Accurate missed-payment information cannot simply be removed because it negatively affects the borrower.
Can You Complain About Recovery Practices?
Borrowers with genuine service grievances should first use the regulated entity’s grievance process.
Where the complaint falls within the applicable framework, RBI’s Ombudsman mechanism may become relevant. The Reserve Bank Integrated Ombudsman Scheme, 2026 came into effect on 1 July 2026.
Read RBI’s Integrated Ombudsman information
The Ombudsman mechanism addresses eligible service grievances. It does not eliminate a valid repayment obligation.
Common Mistakes to Avoid
When considering what happens if you default on education loan, avoid:
- Ignoring lender communication.
- Assuming one missed EMI means immediate property auction.
- Assuming unsecured loans carry no recovery consequences.
- Treating restructuring as guaranteed.
- Accepting settlement without checking credit-report implications.
- Treating “settled” and “closed” as identical.
- Assuming a technical write-off eliminates repayment liability.
- Ignoring incorrect credit-report information.
Responsible Borrowing Before Taking an Education Loan
The best time to understand what happens if you default on education loan is before signing the agreement.
| Check | Question to ask |
| Funding gap | How much do I actually need to borrow? |
| EMI affordability | Can future repayment realistically fit my finances? |
| Moratorium | Does interest continue during this period? |
| Co-borrower | Who becomes liable if repayment fails? |
| Collateral | Which family asset is being exposed? |
| Career uncertainty | Can repayment be managed if employment takes longer than expected? |
| Loan tenure | How does tenure affect the overall repayment commitment? |
Borrow based on your realistic funding requirement and repayment capacity, not simply the highest sanction available.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education.
Understanding what happens if you default on education loan highlights why repayment affordability should be considered before accepting a loan.
Foreign Edu Loans can help students explore suitable education-loan options, compare eligible lenders and understand secured and unsecured financing structures. It can also assist with documentation and application coordination.
Foreign Edu Loans is not the lender. Final approval, interest rate, loan amount and other terms are determined by the respective lender according to its current eligibility, underwriting and credit policies.
Check Your Education Loan Eligibility
FAQs
1. What happens if you default on education loan after one missed EMI?
The payment becomes overdue according to your loan agreement. Applicable charges and credit reporting may follow depending on the lender and circumstances. One missed EMI does not automatically mean immediate collateral auction.
2. How many EMIs can I miss before my education loan becomes an NPA?
Do not rely on a universal number of missed EMIs. Applicable RBI frameworks consider overdue periods. For example, the cited UCB framework uses more than 90 days overdue for term-loan NPA classification.
3. Can education-loan default reduce my CIBIL score?
Yes. CIBIL states that late payments and defaults can negatively affect the CIBIL Score. However, there is no universal fixed score reduction for one missed EMI.
4. Can a lender immediately auction collateral?
No. For qualifying secured debts, applicable statutory conditions and procedures must be followed. One missed EMI does not automatically result in immediate auction.
5. Can I settle an education loan?
A lender may consider compromise settlement according to its policy and the circumstances of the account. Settlement is not guaranteed, and its credit-reporting implications should be understood first.
6. What should I do if I cannot pay my next EMI?
Contact the lender, check your exact outstanding obligation and ask about available account-specific options. Do not assume restructuring or settlement will automatically be approved.
Conclusion
Knowing what happens if you default on education loan helps students and families respond appropriately when repayment becomes difficult. Missed payments can affect credit history, result in applicable penal charges and lead to increasing recovery activity. For qualifying secured loans, collateral enforcement may eventually become possible, but applicable legal conditions and procedures must be followed.
Restructuring and settlement may provide options in some cases, but neither is guaranteed. Review your loan documents, contact the lender, keep written records and monitor your credit information.
Most importantly, before taking an education loan, assess the complete repayment responsibility rather than focusing only on the sanctioned amount.