Yes, an education loan for students with backlogs or gap year may still be possible. A backlog or study gap does not automatically prove ineligibility, but university admission does not guarantee loan approval either. SBI’s Global Ed-Vantage scheme asks for a gap certificate when applicable. Avanse says an inconsistent academic record is not the only criterion it considers, while InCred says assessment can include past academic and career records, future income potential and co-borrower creditworthiness.
For anyone researching an education loan for students with backlogs or gap year, the key question is how the complete profile fits the lender’s current policy.
Education Loan with Backlogs or Gap Year: At a Glance
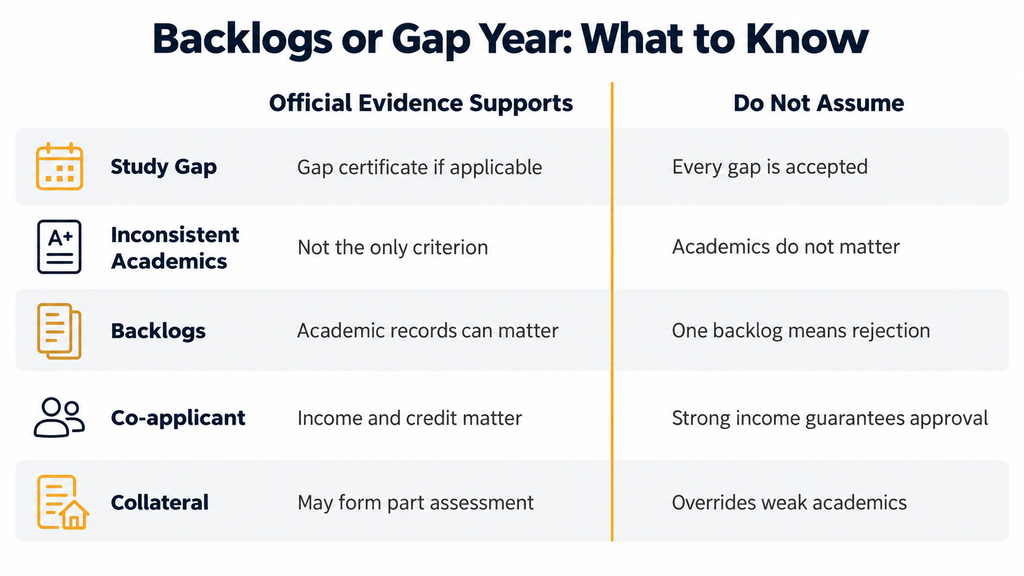
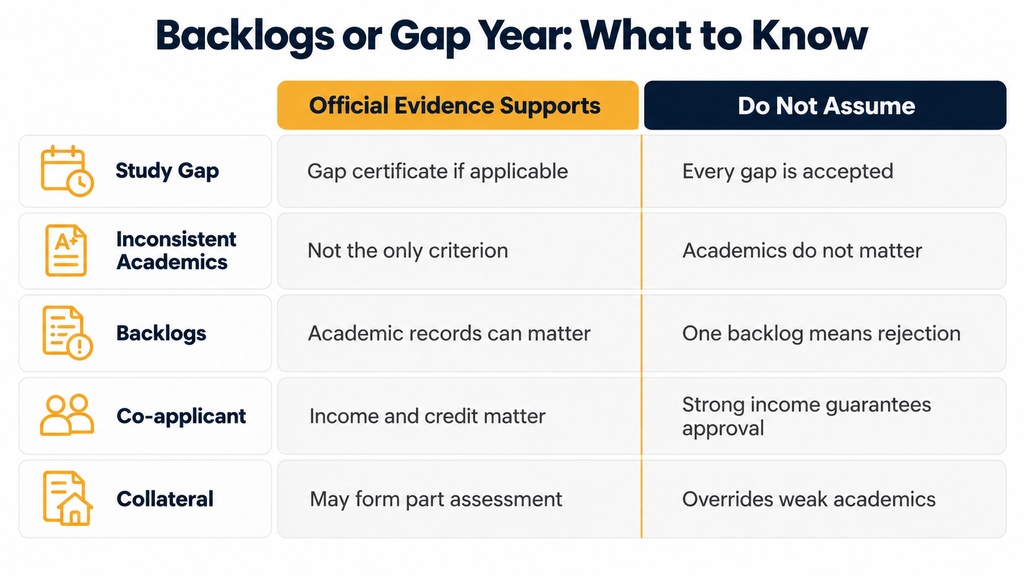
| Situation | What official evidence supports | Do not assume |
| Study gap | SBI asks for a gap certificate if applicable | Every gap is accepted |
| Inconsistent academics | Avanse says academics are not its only criterion | Academics do not matter |
| Backlogs | InCred says academic performance and records can matter | One backlog means rejection |
| Co-applicant | Creditworthiness and income can matter | Strong income guarantees approval |
| Collateral | Security may form part of assessment | Collateral overrides weak academics |
Bottom line: an education loan for students with backlogs or gap year is a profile-based credit decision. No approved official source reviewed here establishes a universal backlog limit or maximum study-gap period.
Can You Get an Education Loan If You Have Backlogs?
You may still apply, but the backlog impact on education loan assessment depends on the lender and the rest of your profile.
InCred’s official guidance says academic performance plays a major role in student-loan approvals and advises students to avoid academic backlogs where possible. Its education-loan FAQ also says assessment can include past academic and career records, projected future income and co-borrower creditworthiness.
That means an education loan for students with backlogs or gap year should not be presented as automatically available. It is equally inaccurate to say any backlog automatically causes rejection.
What may matter alongside backlogs?
- Previous academic performance and consistency
- Course and institution
- Past academic or career records
- Expected repayment potential
- Co-applicant income and creditworthiness
- Collateral, where applicable
- Complete, verifiable documents
For loan eligibility despite academic gaps, backlog count is only one part of a wider assessment.
Is There a Maximum Number of Backlogs Allowed?
There is no verified market-wide number in the approved official sources used for this article.
Claims such as “five backlogs are acceptable” should not be treated as general rules unless the specific lender publishes that policy.
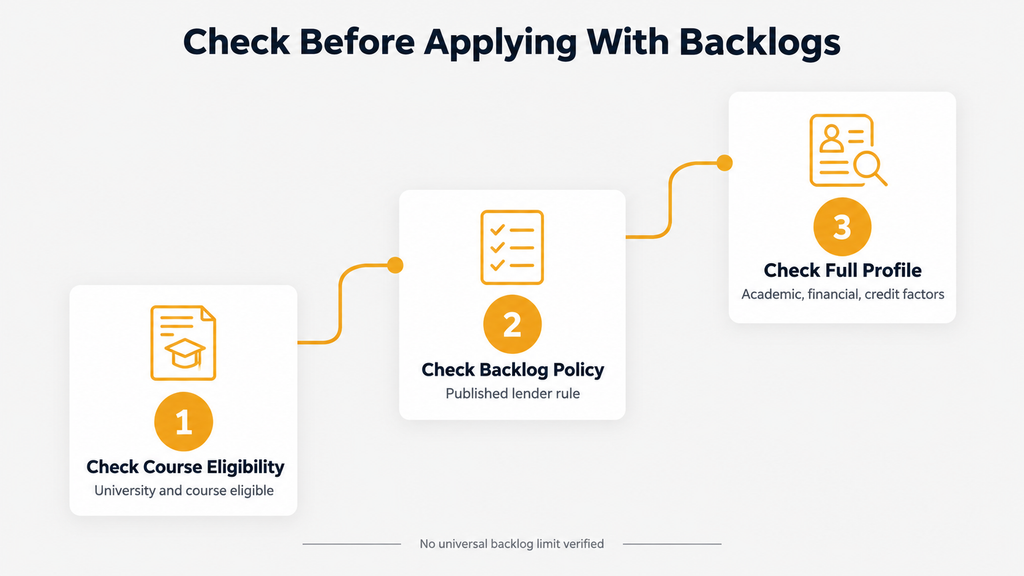
If you need an education loan for students with backlogs or gap year, verify three things with the lender:
- Whether your university and course are eligible.
- Whether the lender publishes a backlog rule.
- What other academic, financial and credit factors will be assessed.
This distinction matters because lender underwriting policies can differ. A number quoted by a consultant, forum or another student should not be assumed to apply to your application.
Can You Get an Education Loan After a Gap Year?
A study gap can require explanation, but the reviewed evidence does not show that a gap automatically makes an application impossible.
SBI’s Global Ed-Vantage checklist includes a “gap certificate, if applicable”, described as a self-declaration from the student for a gap in studies. Its checklist also asks for academic marksheets, proof of admission, course expenses and co-applicant or guarantor documents.
This means an education loan for students with backlogs or gap year can still be assessed when a study gap exists. It does not guarantee gap year loan approval.
Is a one-year or two-year gap automatically acceptable?
No universal duration was found. Do not rely on fixed gap-year limits unless your lender confirms them.
For gap year loan approval, disclose the gap honestly and provide the explanation or certificate the lender requires.
What Do Lenders Check Besides Academic Gaps?
An education loan for students with backlogs or gap year is not necessarily judged on academics alone.
InCred says its evaluation combines educational and financial information, including past academic and career records, projected income and co-borrower creditworthiness. Avanse’s study-abroad loan FAQ says an inconsistent academic record is not its only criterion. Avanse also states that its unsecured study-abroad loans are based on factors including academic merit, course and co-borrower profile.
| Profile factor | Why it may matter |
| Academic history | Shows previous performance and consistency |
| Course and institution | Can affect lender eligibility and risk assessment |
| Co-applicant profile | Income and creditworthiness may affect repayment assessment |
| Career history | Can contribute to the overall profile |
| Collateral | Relevant for secured loans |
| Documentation | Allows the lender to verify your information |
For loan eligibility despite academic gaps, one weak factor does not determine the final decision.
Secured vs Unsecured: Is Either Better for Backlogs?
Neither should be treated as a shortcut.
Avanse says its unsecured study-abroad loans consider academic merit, course and co-borrower profile. An unsecured loan does not bypass academic assessment.
A secured loan can involve collateral, but the evidence does not say collateral automatically compensates for academic gaps.
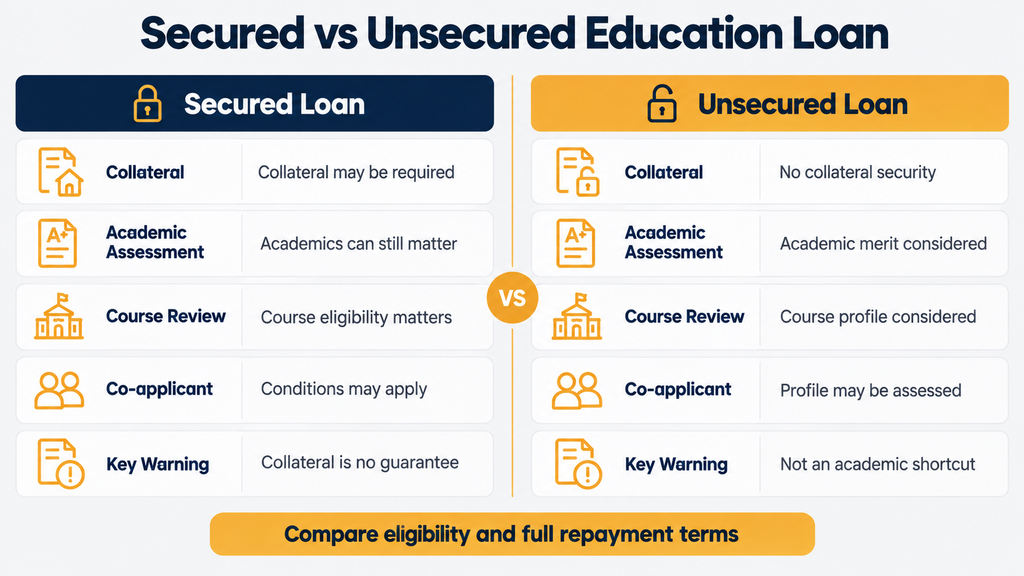
When comparing an education loan for students with backlogs or gap year, review both routes on:
- Course and university eligibility
- Collateral requirement
- Co-applicant conditions
- Interest and total borrowing cost
- Repayment and moratorium terms
- Documentation and final lender conditions
Foreign Edu Loans’ internal guide on collateral versus non-collateral education loans explains the basic distinction before you compare lender offers.
What Documents Should You Prepare?
SBI’s official checklist illustrates why an organised file matters. Exact requirements vary by lender.
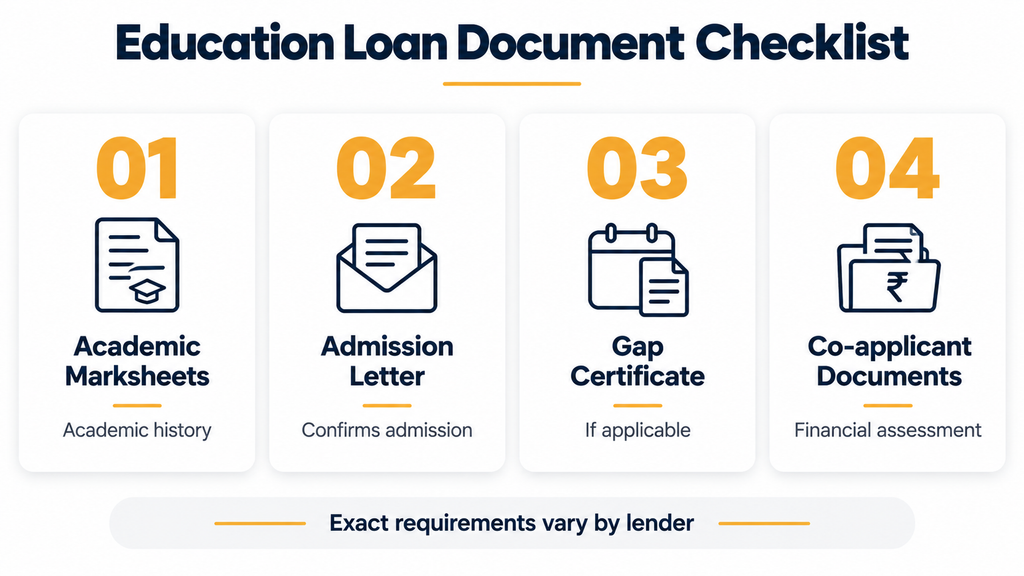
| Document | Purpose |
| Academic marksheets | Establish academic history |
| Entrance-exam result, if applicable | Supports the academic or admission profile |
| Offer or admission letter | Confirms admission |
| Course expense schedule | Establishes funding requirement |
| Gap certificate, if applicable | Explains a study gap in SBI’s process |
| Co-applicant income documents and bank statements | Supports financial assessment |
| Collateral papers, where applicable | Supports a secured application |
If you are seeking an education loan for students with backlogs or gap year, submit a complete and consistent file. Hiding failed subjects, changing dates or giving contradictory explanations can create verification problems.
What Can You Do to Strengthen the Application?
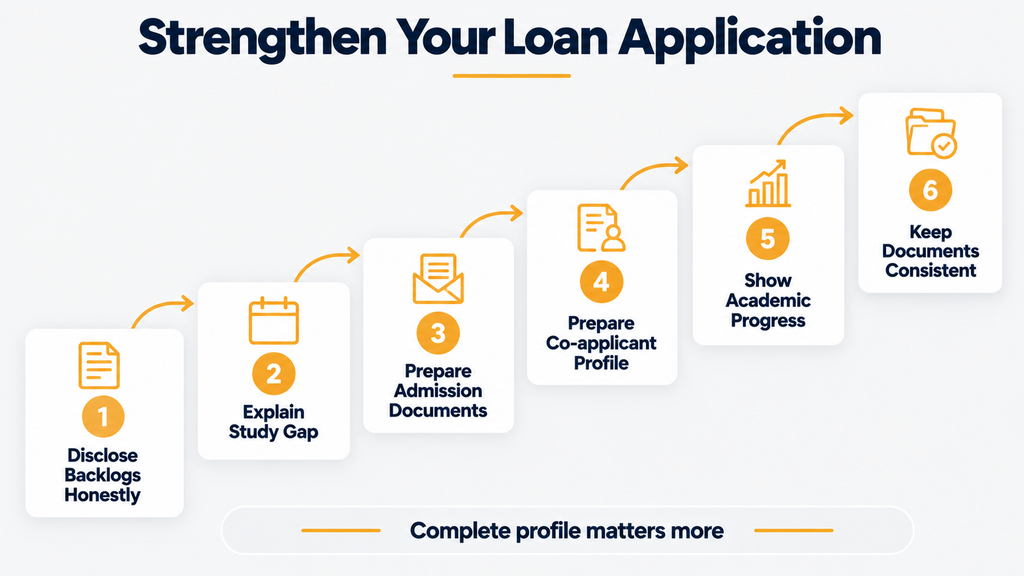
- Be transparent about backlogs and submit complete, accurate academic records.
- Explain your study gap clearly and keep a gap certificate ready if required. SBI Global Ed-Vantage Scheme
- Keep your offer letter, course details and fee schedule ready for verification.
- Prepare the co-applicant’s income, banking and credit documents because the co-borrower profile can form part of loan assessment.
- Highlight genuine academic progress, relevant career history and work experience where applicable.
- Keep all documents complete and consistent when applying for an education loan for students with backlogs or gap year.
- Compare lender-specific criteria instead of assuming every bank follows the same backlog or gap-year policy. RBI confirms that banks can make changes within the broader Model Education Loan Scheme guidelines. RBI Education Loan FAQ
- Compare unsecured and secured alternatives on the basis of eligibility, the terms of repayment, collateral and overall cost of borrowing as opposed to simply deciding to borrow on the basis of probable approval.
Responsible Borrowing Still Matters
Getting an education loan for students with backlogs or gap year is only one part of the decision. The debt must also be affordable.
Before accepting a sanction, compare:
- Actual funding gap after family contribution or scholarship
- Final lender-offered interest rate
- Applicable fees and charges
- Interest treatment during study and moratorium
- Repayment tenure and expected EMI
- Co-applicant repayment responsibility
- Collateral exposure, if any
- Uncertainty around future income
Foreign Edu Loans’ internal guide to the education-loan moratorium period and EMI explains why a moratorium should not automatically be treated as interest-free.
Borrowing rule: compare the complete repayment commitment, not only the sanctioned amount or advertised starting rate.
Common Mistakes to Avoid
- Hiding backlogs: academic records can form part of underwriting.
- Treating admission as approval: university admission and lender sanction are separate decisions.
- Believing one backlog number applies everywhere: the backlog impact on education loan remains lender-specific.
- Treating a gap certificate as approval: it documents the gap but does not guarantee gap year loan approval.
- Assuming collateral fixes everything: the reviewed evidence does not show that security overrides academic, credit or affordability concerns.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform, not a bank or NBFC. Its Terms and Conditions state that it can help students understand loan requirements, provide preliminary indicative eligibility assessments, present loan-option comparisons, conduct administrative document checks, coordinate with lenders and assist with application submission and tracking. Final credit decisions remain with the relevant lender.
If you are exploring an education loan for students with backlogs or gap year, start with the Foreign Edu Loans loan-product overview and lender disclosure before discussing your profile.
Its disclosure explains that displayed rates, amounts and lender information are indicative until confirmed by the relevant lender, which matters when assessing loan eligibility despite academic gaps.
FAQs
Can I get an education loan if I have backlogs?
You may still be considered. InCred says academic history matters, but its assessment also includes other educational and financial factors. No approved source used here says one backlog automatically means rejection.
How many backlogs are allowed?
The approved sources are not verified of any universal number. In the case of an education loan for students with backlogs or gap year, see the existing eligibility policy of the particular lender.
Will my loan be denied due to 1-year or 2 years gap?
SBI’s reviewed process includes a gap certificate where applicable, but no approved source establishes a universal one-year, two-year or three-year acceptance rule. Gap year loan approval remains lender-specific.
Is an unsecured loan easier if I have backlogs?
Not automatically. Avanse says unsecured study-abroad loans consider academic merit, course and co-borrower profile, so the backlog impact on education loan assessment does not disappear simply because collateral is not required.
Does university admission guarantee loan approval?
No. Admission can support the application, but the lender makes a separate credit and eligibility decision. Foreign Edu Loans’ published terms also state that it cannot guarantee approval, sanction, amount, rate or tenure.
Conclusion
An education loan for students with backlogs or gap year may be possible, but approval should never be assumed. Academic history can matter, while the course, institution, co-applicant profile, creditworthiness, documentation and collateral where applicable may also influence the lender’s decision.
No official limit on backlog and maximum gaps time has been found to be verified within the verified sources of this guide. Disclose your academic history, gather materials that are asked, and analyze lender-specific requirements and evaluate the entire loan payment before loaning.