If you are looking for a Prodigy Finance education loan review India, the short answer is yes: Prodigy Finance currently offers eligible Indian master’s students education loans without traditional collateral or a co-signer. But “collateral-free” does not mean free money, guaranteed approval or automatically cheaper borrowing. Your university and programme must be supported, your application remains subject to assessment, and interest, fees and repayment obligations still apply.
For Indian students, the real decision is whether the absence of collateral outweighs factors such as variable interest, fees, foreign-currency exposure and repayment responsibility. This Prodigy Finance education loan review India examines those factors using current official information.
Accuracy Note: This article was fact-checked on 27 August 2026. Prodigy Finance rates, eligibility, fees, funding availability and product conditions can change. Check the current lender information and your individual offer before borrowing.
Read out: Prodigy Finance, India Student Loans
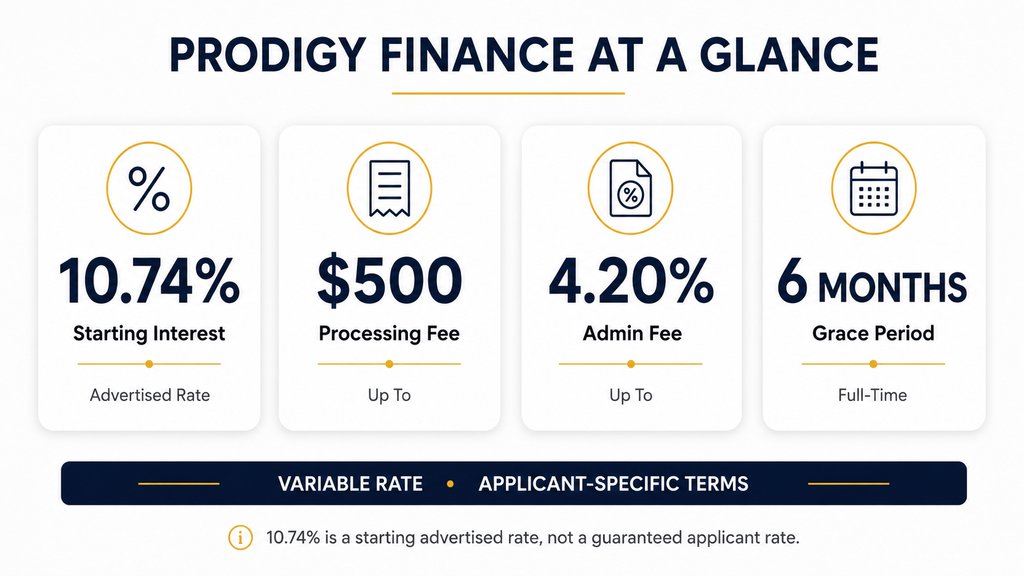
Prodigy Finance Education Loan Review India: At a Glance
| Feature | Current Position |
| Target study level | Master’s study at supported universities/programmes |
| Traditional collateral | Not required for eligible applicants |
| Co-signer | Not required |
| Advertised starting interest | From 10.74% |
| Interest structure | Variable |
| Rate construction | Fixed margin + variable benchmark |
| Processing fee | Up to USD 500 |
| Admin fee | Up to 4.20% |
| Full-time in-school payment | USD 100/month where applicable |
| Full-time grace period | 6 months after course completion |
| Early repayment | No early-repayment penalty |
| Tuition disbursement | Directly to the school |
| Final terms | Applicant-specific |
*The 10.74% figure is an advertised starting interest rate, not a guaranteed rate for every student. Individual offers are subject to eligibility, funding and credit assessment.
Check out: Prodigy Finance, Am I eligible for a loan?
Key takeaway: This Prodigy Finance education loan review India shows that collateral is only one part of the decision. The complete borrowing commitment matters more.
Is Prodigy Finance Really Collateral-Free for Indian Students?
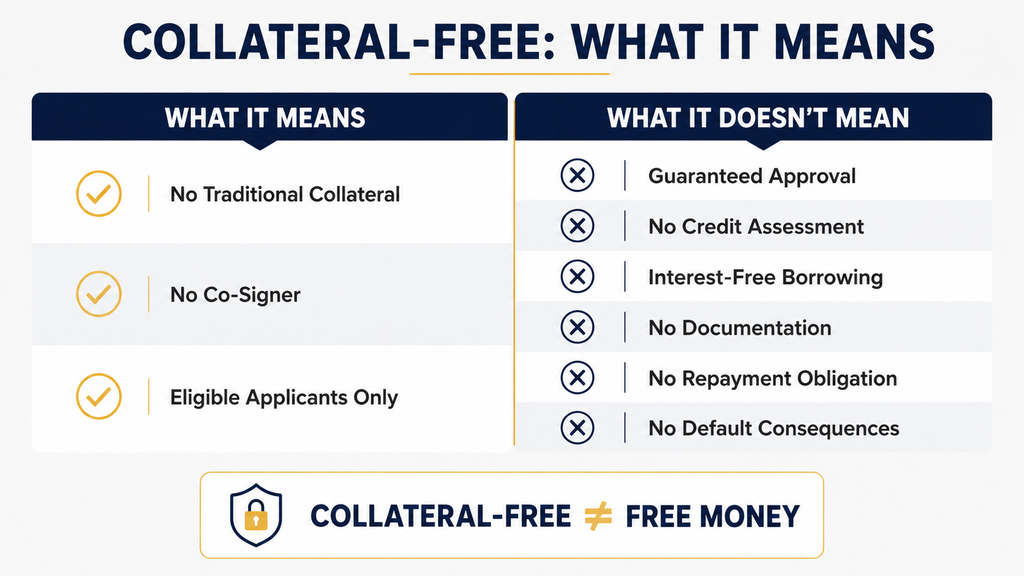
Yes, according to Prodigy’s current India and eligibility pages.
Prodigy states that eligible students can apply without pledging family property or arranging a co-signer or guarantor. Its assessment considers factors including university acceptance, affordability and future earning potential.
That makes the collateral-free structure one of the strongest features identified in this Prodigy Finance education loan review India.
However, collateral-free does not mean:
- guaranteed approval;
- no credit assessment;
- interest-free borrowing;
- no documentation;
- no repayment obligation;
- no financial consequences for default.
A student still enters into a loan contract and remains responsible for repayment.
This distinction matters when researching no-collateral international lenders. Removing the requirement to pledge an asset can solve one financing problem, but it does not remove the cost or risk of borrowing.
Read out: Am I eligible for a loan?
Who Is Eligible for Prodigy Finance From India?
Prodigy Finance eligibility India depends on more than nationality.
Current Prodigy information requires applicants, subject to assessment, to have a supported school and programme, study abroad and satisfy applicable residence and funding conditions.
For Indian students, the current India page specifically positions the product for master’s study abroad.
Students should therefore check:
- Whether their exact university is supported.
- Whether their exact course is supported.
- Whether their study destination is eligible.
- Whether their intake currently has funding availability.
- Whether they satisfy Prodigy’s assessment requirements.
Prodigy also states that students can check eligibility and obtain a quote before programme acceptance, although proof of admission is needed when completing the loan.
The current eligibility page additionally warns that Fall 2026 applications are being released by country according to funding availability.
So, Prodigy Finance eligibility India does not mean every Indian student automatically qualifies.
What Does the 10.74% Starting Interest Rate Mean?
This is one of the most important financial points in this Prodigy Finance education loan review India.
As checked on 27 August 2026, Prodigy’s current main student-loan page and India page advertise:
Master’s loans starting from 10.74% interest rate.
That figure must be interpreted correctly.
It is a starting advertised rate, not a promise that an Indian applicant will receive 10.74%.
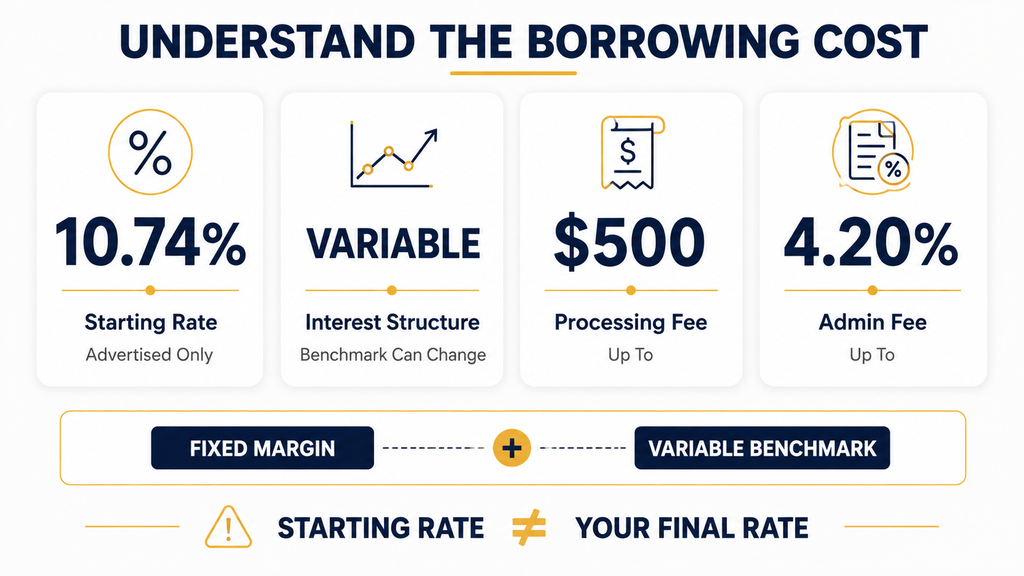
Prodigy explains that its interest rate is variable and consists of:
Fixed Prodigy margin + variable benchmark rate
The benchmark component can change, meaning the applicable rate can also change.
Prodigy also states that it uses simple interest. However, interest accruing during the grace period is capitalised on the first repayment date, after which simple interest applies to the resulting balance.
Therefore, a responsible Prodigy Finance education loan review India should never compare 10.74% directly with another lender’s headline rate without checking whether the products, fees, benchmarks and repayment assumptions are comparable.
What Fees Does Prodigy Finance Charge?
Interest is not the complete borrowing cost.
Current Prodigy information shows:
| Cost | Current Published Position | How It Works |
| Processing fee | Up to USD 500 | Paid to reserve matched funds |
| Admin fee | Up to 4.20% | Added to the loan |
| Early repayment fee | None | Early repayment permitted |
Prodigy states that its processing fee is payable after funding is matched and before finalisation.
The administration fee can be up to 4.20% of the loan amount and is added to the loan instead of being paid upfront.
This is important in any Prodigy Finance education loan review India because a lower-looking interest rate does not automatically mean a lower total borrowing cost.
Read out: How is the interest rate and admin fee calculated?
When Do You Start Repaying?
For the current full-time product structure, Prodigy states that students pay USD 100 per month while studying and during the six-month grace period, with full repayments beginning after that grace period.
However, product structures can differ by intake. Prodigy explicitly says repayment terms may vary, so your final loan offer and agreement remain decisive.
The six-month grace period should also not be interpreted as interest-free.
Can you repay early?
Yes. Prodigy’s current repayment information states that borrowers can repay early without penalties or extra fees.
For this Prodigy Finance education loan review India, that is a useful feature because students who later have additional funds are not contractually prevented by an early-repayment penalty from reducing the outstanding balance sooner.
Prodigy Finance: Advantages and Limitations
A genuine Prodigy Finance education loan review India should assess both sides rather than presenting “no collateral” as an automatic recommendation.
| Potential Advantage | Limitation to Consider |
| No traditional collateral for eligible applicants | Eligibility is limited to supported programmes and destinations |
| No co-signer required | Approval is not guaranteed |
| Master’s-focused international financing | Variable interest creates rate uncertainty |
| Early repayment without penalty | Processing and admin fees apply |
| Tuition and eligible living costs may be financed | Final funding depends on assessment |
| Future earning potential forms part of assessment | Foreign-currency repayment can create INR exposure |
Verdict from the table: Prodigy solves an important collateral problem for some Indian students, but that benefit should be weighed against cost, eligibility and repayment risks.
What Documents and Credit Checks Can Apply?
No collateral does not mean no verification.
Prodigy’s application process gathers academic, personal and financial information. Its current application guidance also refers to credit verification before a conditional provisional offer.
For Indian applicants, this is important because students should not assume that “collateral-free” means “no credit assessment”.
A provisional offer is also not the same as final approval. Prodigy explicitly states that provisional offers remain subject to verification and full assessment.
This distinction strengthens the accuracy of this Prodigy Finance education loan review India.
Check out: How to complete your application
How Does the Application Process Work?
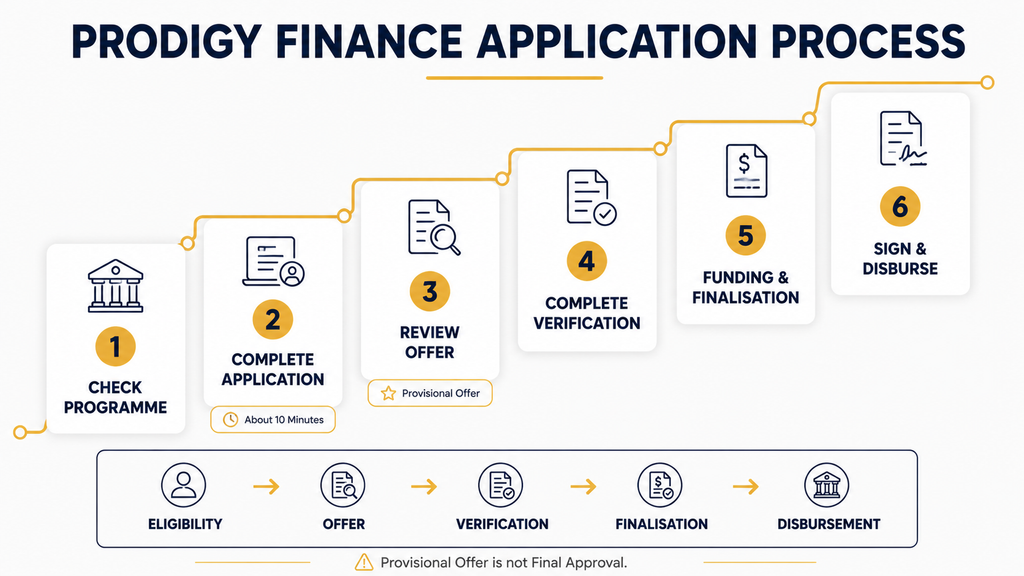
Step 1: Check Your School and Programme
Confirm that Prodigy currently supports your exact university, course and intake.
Step 2: Complete Your Application
Enter the requested academic, personal and financial information.
Prodigy currently says the application itself takes about 10 minutes and eligible applicants may receive a provisional offer instantly or within two business days.
These are published process timings, not guaranteed approval timings.
Step 3: Review the Provisional Offer
The provisional offer can show the estimated loan amount, available term, estimated interest rate and estimated monthly repayment.
Step 4: Complete Verification
Supporting information and documents are checked.
Step 5: Funding and Finalisation
If the application successfully completes the required stages and funding is available, the loan progresses towards finalisation.
Step 6: Sign the Agreement and Disburse Funds
The applicable loan agreement is signed and funds are disbursed according to the agreed structure.
A useful lesson from this Prodigy Finance education loan review India is that eligibility, provisional offer, verification, final approval and disbursement are different stages.
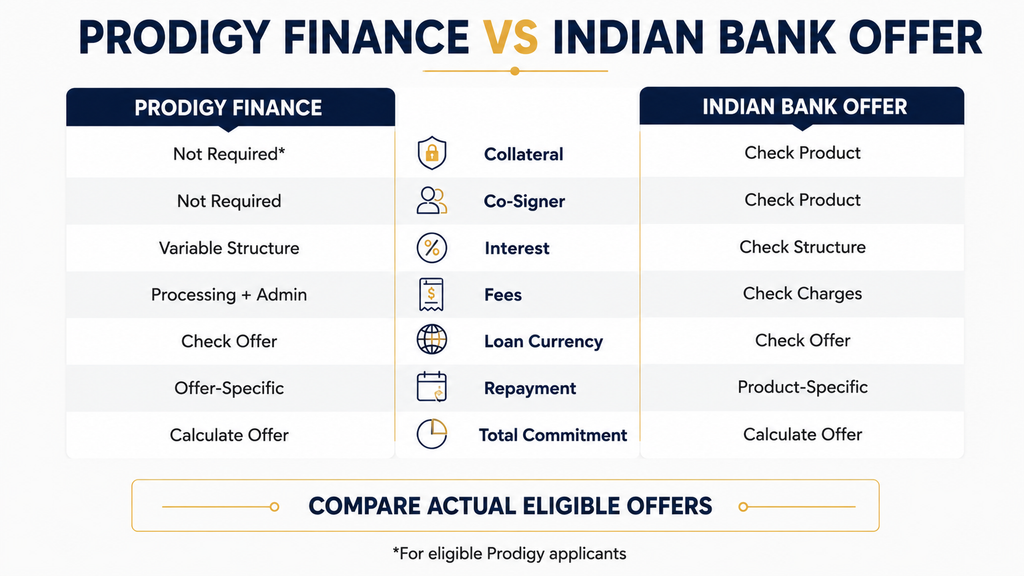
Prodigy Finance vs Indian Banks: What Should You Compare?
There is no responsible universal answer to whether Prodigy or an Indian bank is “better”.
This Prodigy Finance education loan review India deliberately avoids inserting generic Indian-bank rates because rates, collateral rules, margins, fees and eligibility need to be verified for each lender and product.
Instead, compare your actual eligible offers using the same criteria:
| Decision Factor | Prodigy Finance | Indian Bank Offer |
| Collateral | Not required for eligible Prodigy applicants | Check selected product |
| Co-signer | Not required | Check selected product |
| Interest structure | Variable benchmark + fixed margin | Check lender’s current structure |
| Fees | Processing + admin fee | Check lender’s current charges |
| Loan currency | Check individual Prodigy offer | Check bank offer |
| Repayment | Offer-specific | Product-specific |
| Total borrowing commitment | Calculate from actual offer | Calculate from actual offer |
Interpretation: A meaningful Prodigy Finance vs Indian banks comparison starts with actual eligible offers, not marketing headlines.
7 Checks Before Accepting a Prodigy Finance Offer
Before using this Prodigy Finance education loan review India to make your final decision, check:
- Is my exact university and programme supported?
- What interest rate appears in my individual offer?
- Which variable benchmark applies?
- What processing and admin fees apply?
- What currency will I borrow and repay in?
- What will happen to interest before full repayment begins?
- How does the complete Prodigy offer compare with another education-loan option available to me?
This checklist is more useful than deciding based only on the phrase “collateral-free”.
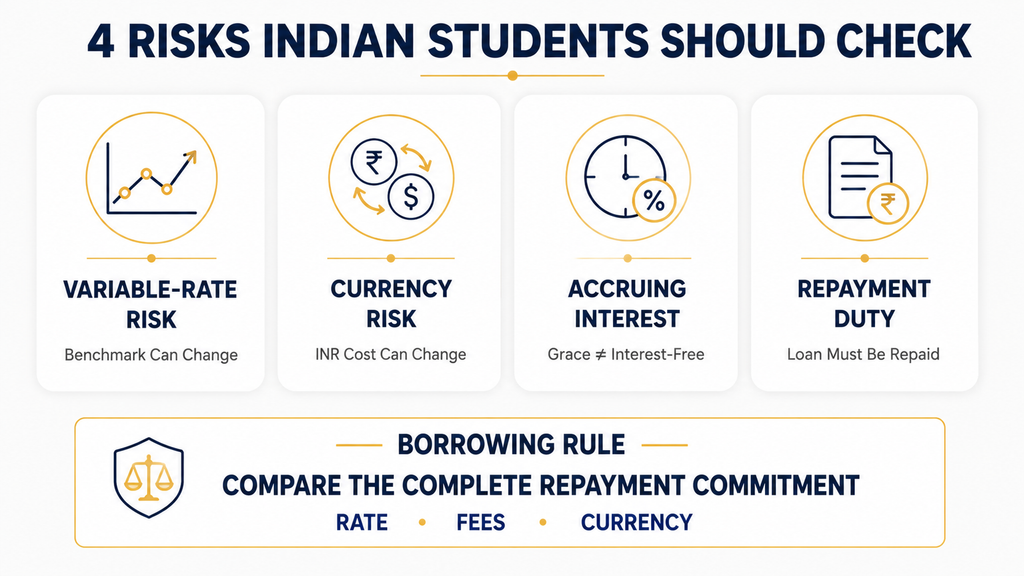
What Risks Should Indian Students Consider?
A balanced Prodigy Finance education loan review India should make four risks especially clear.
- Variable-rate risk: The benchmark component can change, affecting the applicable interest rate.
- Currency risk: Where an Indian borrower earns or holds money in INR but must repay a foreign-currency loan, exchange-rate movements can change the INR amount needed for repayment.
- Accruing interest: A grace period does not automatically mean an interest-free period.
- Repayment responsibility: No collateral does not eliminate the legal obligation to repay the loan.
Borrowing Rule: Compare the complete repayment commitment, not only the sanctioned amount, advertised starting rate or absence of collateral.
Final Verdict: Is Prodigy Finance Worth Considering?
Yes, for the right borrower.
Based on the current evidence reviewed for this Prodigy Finance education loan review India, Prodigy can be worth considering for an eligible Indian master’s student who cannot or does not want to pledge traditional collateral or arrange a co-signer.
Its collateral-free structure is genuine under the current published eligibility framework. But the decision should ultimately depend on your individual interest rate, variable benchmark, fees, loan currency, repayment schedule and overall affordability.
The strongest approach is to compare the final Prodigy offer with other education-loan options for which you actually qualify.
How Foreign Edu Loans Can Help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education. It is not a bank or NBFC and does not itself sanction or disburse loans.
Foreign Edu Loans can help students explore financing options, understand different loan structures and coordinate the education-loan application process.
Students using this Prodigy Finance education loan review India can also explore the following Foreign Edu Loans resources:
Final approval, interest rates, APR, loan amount, tenure, security requirements and charges remain determined by the respective lender. Foreign Edu Loans lender disclosure
FAQs
Is Prodigy Finance really collateral-free for Indian students?
Yes, for eligible applicants under its current product framework. Prodigy states that Indian master’s students can apply without traditional collateral or a co-signer. Eligibility and final approval remain subject to assessment.
Does Prodigy Finance offer everyone a 10.74% rate?
No. This Prodigy Finance education loan review India uses 10.74% only as the starting rate currently advertised by Prodigy. Your individual rate can differ.
Does collateral-free mean guaranteed approval?
No. Prodigy states that applications are subject to eligibility, funding and credit assessment criteria.
Can I repay Prodigy Finance early?
Yes. Current Prodigy information states that early repayment is allowed without penalties or extra fees.
Is Prodigy Finance better than an Indian bank?
Not universally. A useful Prodigy Finance education loan review India should compare actual eligible offers across interest, fees, collateral, repayment, currency and overall borrowing commitment.
Does Prodigy require a co-applicant?
Prodigy states that eligible applicants do not require a co-signer. Its current application guidance may still request parent or guardian contact information for verification purposes, but it specifically states that this does not make that person responsible for the loan.
Conclusion
The conclusion of this Prodigy Finance education loan review India is that Prodigy offers a genuinely different financing structure for eligible Indian master’s students: no traditional collateral and no co-signer requirement. That can be valuable when family property or an Indian guarantor is unavailable.
However, collateral-free should never be confused with cost-free or risk-free. Check your individual rate, variable benchmark, fees, repayment schedule, loan currency and total borrowing commitment. Then compare that offer with other financing options available to you.
The best education loan is not automatically the one offering the highest amount or requiring no collateral. It is the option whose complete repayment responsibility you understand and can reasonably manage.