The impact of USD-INR exchange rate on education loan EMI is real, but it is often explained badly. If your loan is in INR and your university charges in USD, a weaker rupee can increase the INR needed for a future tuition payment. If that higher requirement becomes part of the amount ultimately financed, your later repayment burden can rise. However, an already-fixed INR EMI does not automatically increase every time USD-INR moves. With a USD-denominated loan repaid from INR income, exchange-rate movements can affect the rupee-equivalent monthly payment more directly.
This guide covers the impact of USD-INR exchange rate on education loan EMI, loan-currency exposure, remittance rates, hedging, common mistakes and a borrower checklist.
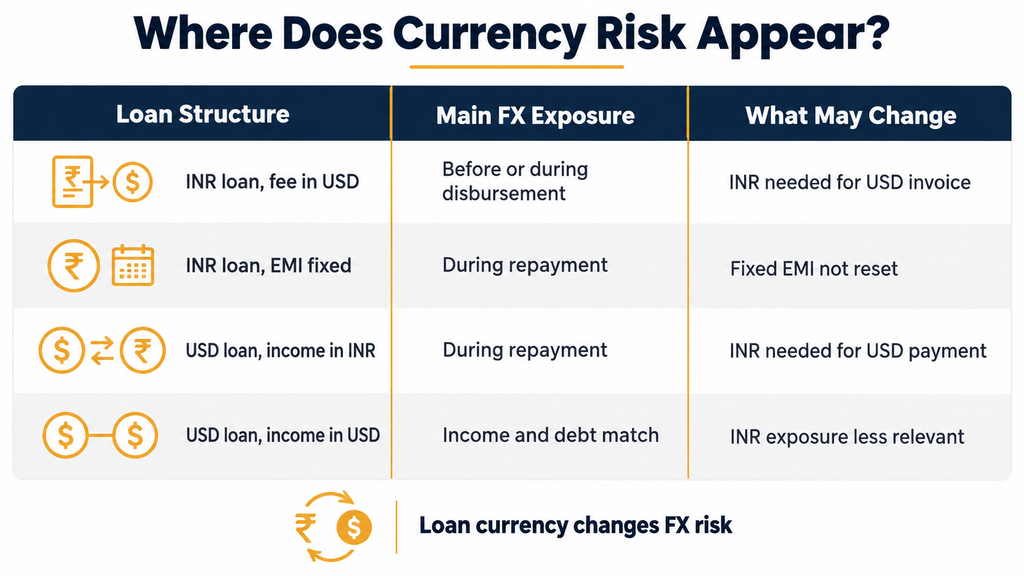
At a glance: where does currency risk appear?
| Loan structure | Main FX exposure | What may change |
| INR loan, fee in USD | Before or during overseas disbursement | INR needed for the USD invoice |
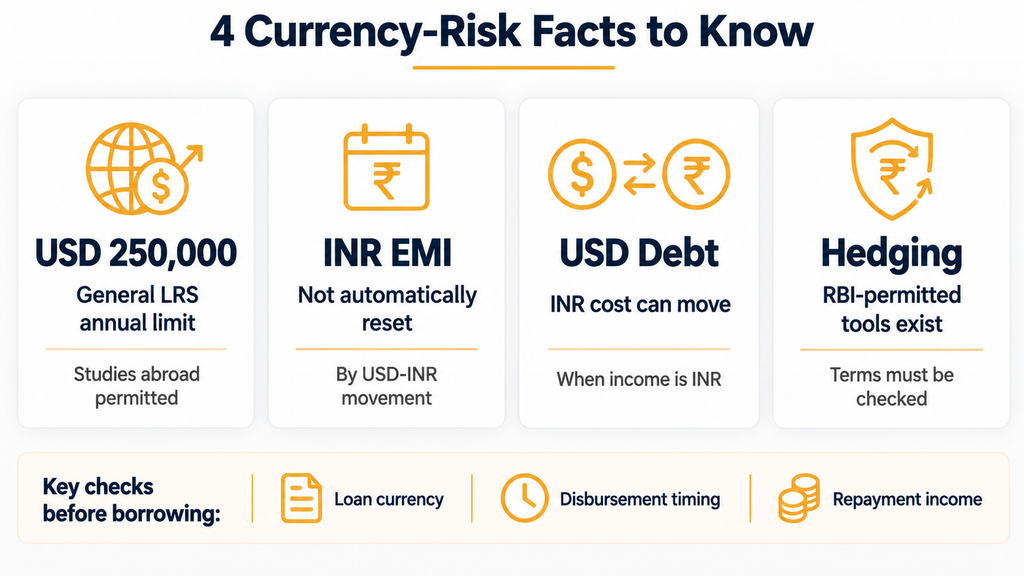
| INR loan, EMI already fixed | During repayment | USD-INR does not automatically reset the fixed EMI |
| USD loan, income in INR | During repayment | INR needed for the same USD payment |
| USD loan, income in USD | Income and debt match | INR exposure may be less relevant |
Read out: How to Apply for Education Loan for Abroad: Step-by-Step (2026)
What does the impact of USD-INR exchange rate on education loan EMI really mean?
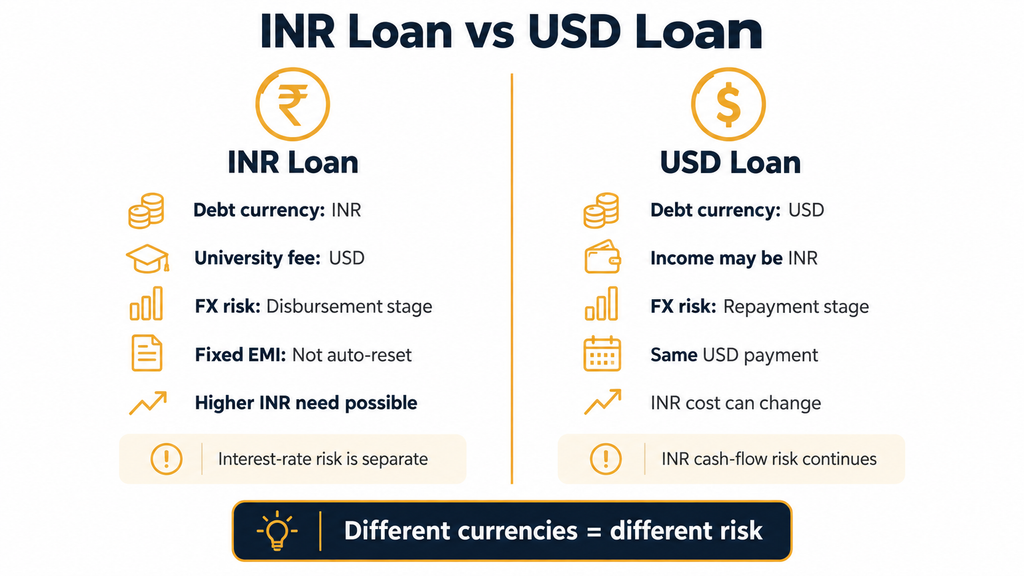
For an INR education loan, the first effect of a weaker rupee is usually on the INR cost of the foreign-currency expense, not on an existing EMI.
SBI’s Global Ed-Vantage terms describe overseas education financing in INR and permit staged disbursement according to the institution’s requirement. SBI’s MITC specifically states that disbursements may be made in stages according to requirement.
If a later university invoice remains in USD and the rupee is weaker when payment is due, more INR may be required. This is a central forex risk education loan issue. Forex risk education loan planning should begin before the next fee payment.
The impact of USD-INR exchange rate on education loan EMI then depends on how the higher INR requirement is funded. No universal rule requiring automatic sanction enhancement was verified.
Why can a falling rupee increase your education funding requirement?
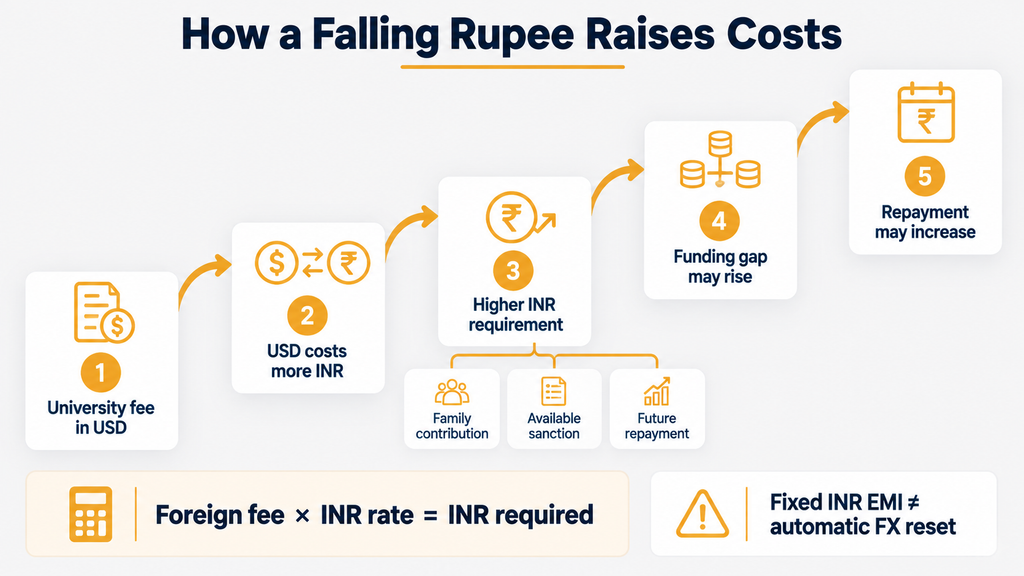
The basic relationship is:
Foreign-currency fee × applicable INR conversion rate = INR amount required
If the USD fee is unchanged but one dollar costs more rupees, the INR requirement rises.
That can affect:
- Family contribution: more INR may be needed.
- Available sanction: a later disbursement may consume more of it.
- Future repayment: if more INR is actually financed, the repayment base can be higher.
This is why the impact of USD-INR exchange rate on education loan EMI can be indirect but still important for an INR loan.
Before borrowing, compare the loan structure, not only the headline rate. Foreign Edu Loans’ Loan Products page can help you review broad financing routes.
Does the rupee falling make an existing INR EMI rise automatically?
No.
Once an INR repayment amount is fixed under the loan’s terms, USD-INR does not automatically re-price it. A floating-rate INR loan can still change because of its benchmark. That is interest-rate risk, not currency risk.
SBI’s official education-loan information separately explains that accrued interest during the course and moratorium can be added to principal before EMI is fixed, depending on the product terms.
When assessing the impact of USD-INR exchange rate on education loan EMI, separate these questions:
- Can the exchange rate change how many rupees are needed for a future overseas payment?
- Can the interest-rate structure change the INR repayment schedule?
Confusing them can make EMI fluctuation due to exchange rate sound universal when it is not.
Check out: Public Bank vs Private Bank vs NBFC Education Loan: Which Is Best for Your Loan?
When does the impact of USD-INR exchange rate on education loan EMI become direct?
The connection is clearer when the loan itself is denominated in USD and the borrower later earns in INR.
MPOWER’s official guidance for Indian students states that its relevant U.S. study loans are disbursed and repaid in U.S. dollars. Borrowers returning to India therefore need to budget for rupee-to-dollar conversion.
The mechanism is simple: the obligation is in USD, but the borrower’s cash flow may be in INR. If USD becomes more expensive, more rupees are needed for the same USD payment.
This is the clearest form of EMI fluctuation due to exchange rate from an Indian borrower’s cash-flow perspective.
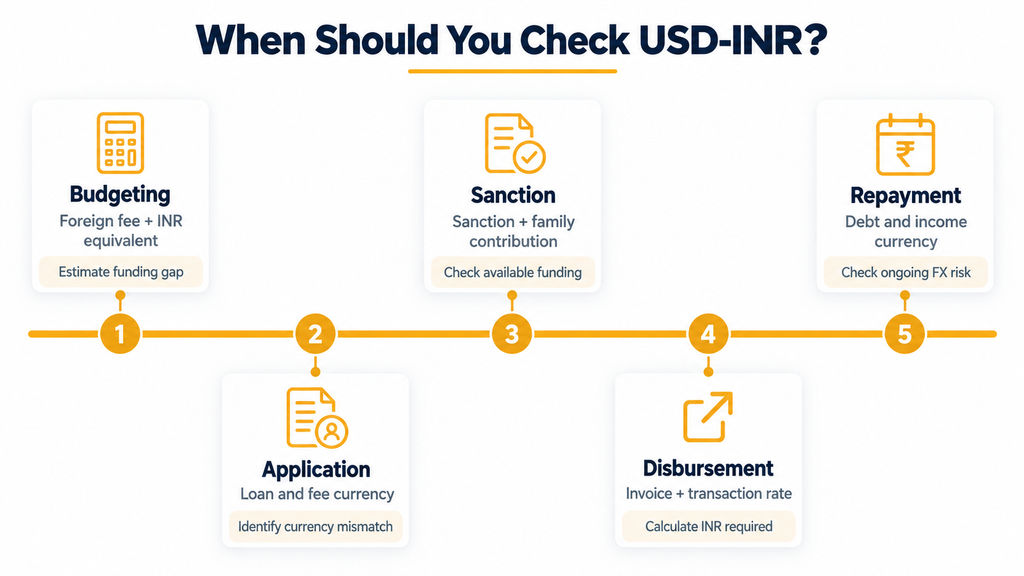
At which stages should you check USD-INR?
The impact of USD-INR exchange rate on education loan EMI should not be assessed only when you submit the loan application.
| Stage | What to check | Why it matters |
| Budgeting | Foreign fee and INR equivalent | Estimates the funding gap |
| Application | Currency of loan and fee | Identifies currency mismatch |
| Sanction | INR sanction and family contribution | Shows available funding |
| Disbursement | Invoice and transaction rate | Determines INR required |
| Repayment | Currency of debt and income | Shows whether FX risk continues |
Which USD-INR rate should students use?
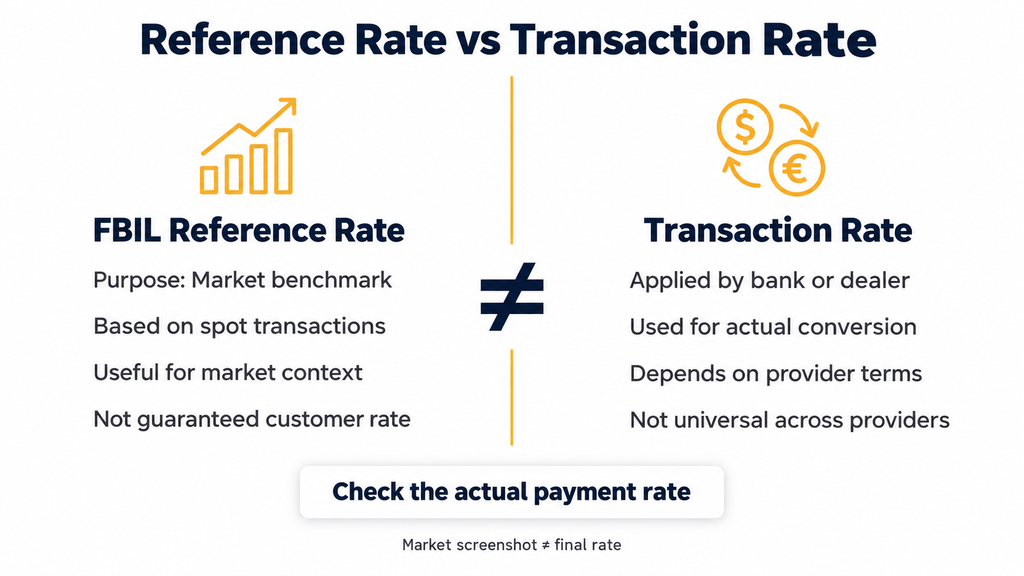
FBIL’s USD-INR Reference Rate methodology explains that its benchmark is calculated using actual spot USD-INR transactions under a defined methodology. This makes the reference rate useful for market context, but it does not make it the guaranteed customer remittance rate.
SBI’s official FX-Out FAQ states that the applicable TT Selling Card Rate is used for the relevant outward-remittance transaction. SBI’s terms similarly state that the applicable TT Selling Card Rate on the remittance date is binding on the applicant.
Reference rate versus transaction rate
| Rate | Use it for | Do not assume |
| FBIL reference rate | Market benchmark | Your bank will transact at exactly this rate |
| Bank or authorised-dealer rate | Actual conversion under its terms | Every provider uses the same rate |
The impact of USD-INR exchange rate on education loan EMI should therefore be assessed using the rate actually applicable to the payment, not a random market screenshot.
Use the Foreign Edu Loans EMI Calculator for scenario planning once your assumptions are clear. Treat the result as an estimate, not a lender quote.
Check out: Documents Required for Education Loan (2026 Checklist)
Illustrative Example: isolate the currency effect
No approved hypothetical tuition amount or loan rate was supplied, so this example uses variables rather than invented numbers.
Assume:
- University invoice = USD X
- Planning rate = R1 INR per USD
- Payment rate = R2 INR per USD
Then:
Planned INR requirement = X × R1
Actual INR requirement = X × R2
Currency-driven difference = X × (R2 – R1)
If R2 is higher than R1, more INR is required for the same USD invoice.
This isolates currency movement only. It does not assume the lender will finance the difference and excludes interest, processing fees, remittance charges and moratorium interest. That keeps the impact of USD-INR exchange rate on education loan EMI separate from other borrowing costs.
Does RBI’s Liberalised Remittance Scheme matter?
Yes, but it is a supporting issue rather than the EMI mechanism.
The RBI Liberalised Remittance Scheme FAQ states that resident individuals may remit up to USD 250,000 per financial year for permissible transactions. Its list of eligible purposes includes studies abroad.
LRS concerns overseas remittances. It does not mean USD-INR directly resets an INR EMI.
Can students use currency hedging for education loan exposure?
The RBI Foreign Exchange Transactions FAQ confirms that specified forex derivatives are available to retail users for hedging exchange-rate risk, including foreign-exchange forwards and certain options.
However, currency hedging for education loan exposure is not an automatic solution.
We did not verify a universal student-specific minimum amount, fee or product condition.
For currency hedging for education loan exposure, ask an RBI-authorised dealer what is available for your genuine obligation and what it costs. A hedge does not guarantee savings.
The impact of USD-INR exchange rate on education loan EMI should be managed through planning, not currency speculation.
Five mistakes students and parents should avoid
- Assuming every INR EMI moves with USD-INR.
A fixed INR EMI is not automatically indexed to the dollar. - Budgeting every semester at one exchange rate.
Later payments can occur at different rates. - Treating a reference rate as the final remittance rate.
The transaction provider may use another applicable rate. - Ignoring the loan currency.
USD debt repaid from INR income creates a different risk from INR debt used for USD tuition. - Assuming the lender will cover an FX shortfall.
No universal sanction-enhancement rule was verified.
These mistakes can distort the impact of USD-INR exchange rate on education loan EMI and cause families to underestimate their funding gap.
Currency-risk checklist before taking the loan
| Ask this | Why it matters |
| What currency is the university invoice in? | Defines the foreign obligation |
| What currency is the loan in? | Shows whether the debt itself has FX exposure |
| Is disbursement staged? | Future exchange rates may matter |
| Which rate applies to remittance? | Helps estimate the real INR need |
| What must the family contribute? | Shows who absorbs higher INR costs |
| What happens if costs rise after sanction? | Avoids assuming extra finance |
| What currency will I earn in later? | Important for foreign-currency debt |
The impact of USD-INR exchange rate on education loan EMI is easier to manage when these questions are answered before the money is due.
Responsible borrowing: look beyond the EMI
Understanding the impact of USD-INR exchange rate on education loan EMI matters only when it improves the borrowing decision.
Currency is only one part of education-loan risk. Also examine the actual funding gap, moratorium interest, repayment tenure, fixed or floating rate structure, collateral and co-applicant responsibility, prepayment terms, and the currency of expected income.
Borrowing Rule: Compare the complete repayment commitment, not only the sanctioned amount or an advertised starting rate.
Good forex risk education loan planning matters only if it improves the borrowing decision.
How Foreign Edu Loans can help
Foreign Edu Loans is an education-loan facilitation and guidance platform for students pursuing international education. It is not a bank or NBFC and does not make the final credit decision.
Foreign Edu Loans can help students explore suitable education-loan routes, compare eligible lender options, and coordinate documentation and applications.
Review the Foreign Edu Loans Loan Products page, test scenarios with the EMI Calculator, or Check Your Education Loan Eligibility when ready.
Final approval, applicable rate, sanction amount, security requirements and other terms are determined by the respective lender.
FAQs
1. What is the impact of USD-INR exchange rate on education loan EMI for an INR loan?
It can increase the INR cost of future USD university payments. If that leads to a higher amount actually financed, the later repayment burden can rise. A fixed INR EMI does not automatically change every time USD-INR moves.
2. Can EMI fluctuation due to exchange rate happen with a USD loan?
Yes, from an INR cash-flow perspective. If debt must be repaid in USD but income is in INR, the rupees required for the same USD payment can change with the exchange rate.
3. Is the FBIL USD-INR rate the rate my lender will use?
Not necessarily. FBIL publishes a benchmark reference rate. The bank or authorised dealer processing the payment may apply the rate specified under its own terms.
4. Is currency hedging for education loan exposure always useful?
There is no universal answer. RBI permits specified forex derivatives for retail users to hedge exchange-rate risk, but availability, suitability, cost and conditions need to be checked with an authorised dealer.
5. What should I ask my lender before accepting the loan?
Ask about loan currency, disbursement schedule, family contribution, applicable FX conversion process, treatment of a funding shortfall, interest-rate structure, moratorium terms and repayment currency.
Conclusion
The impact of USD-INR exchange rate on education loan EMI depends on where currency risk enters your borrowing. With an INR loan funding USD tuition, a weaker rupee can increase the INR needed for future foreign payments and may increase the amount ultimately financed. It does not automatically make an already-fixed INR EMI fluctuate. With a USD-denominated loan repaid from INR income, the link is more direct because more rupees may be needed for the same USD payment.
Before borrowing, map the currency of your tuition, loan, disbursements and expected income. Compare the complete repayment commitment and plan for uncertainty rather than assuming today’s exchange rate will hold. Check Your Education Loan Eligibility