When deciding on SBI Global Ed-Vantage vs HDFC Credila, it is not possible to choose one over the other based on an advertised interest rate. The one which saves more will be the alternative that you eventually sign with, based on loan amount, collateral, contribution by family, rate of processing, moratorium interest and payment plan. The defined overseas education-loan program by the State Bank of India is called SBI Global Ed-Vantage, and customised education financing is offered by Credila Financial Services Limited, formerly HDFC Credila Financial Services Limited. In this SBI Global Ed-Vantage vs HDFC Credila comparison, the key expenses and terms that the students and parents ought to take into consideration are discussed. The point is straightforward: compare wholesome loan applications instead of choosing a lender due to one of the numbers appearing in the advertisement being less than the other.
Rates on education loans, eligibility, fees and the terms and conditions of lending may vary. The ultimate conditions are subject to the value of the loan, profile of the applicant and the evaluation by the lender. Confirm terms actually with the lender.
Read out: How to Apply for Education Loan for Abroad: Step-by-Step (2026)
SBI Global Ed-Vantage vs HDFC Credila: Speedy Comparison.
| Factor | Credila | SBI Global Ed-Vantage |
| Loan structure | Customised financing | Public-sector bank |
| Lender | Education-finance NBFC | Bank, Education-finance NBFC |
| Maximum amount published | Profile/product dependent | Defined overseas scheme |
| Interest | Applicant/product dependent | To a maximum of 50 lakh in case of select top-end institutions. |
| Collateral-free | Profile/product dependent | Up to ₹3 crore |
| Processing | Applicable lender charges | Floating, benchmark-linked |
| Approval | Credila assessment | Up to 15 years |
| Repayment | Product/sanction dependent | ₹10,000 per application |
What it relieves you of: Written offers of the same amount of funding should be used to compare SBI Global Ed-Vantage with HDFC Credila.
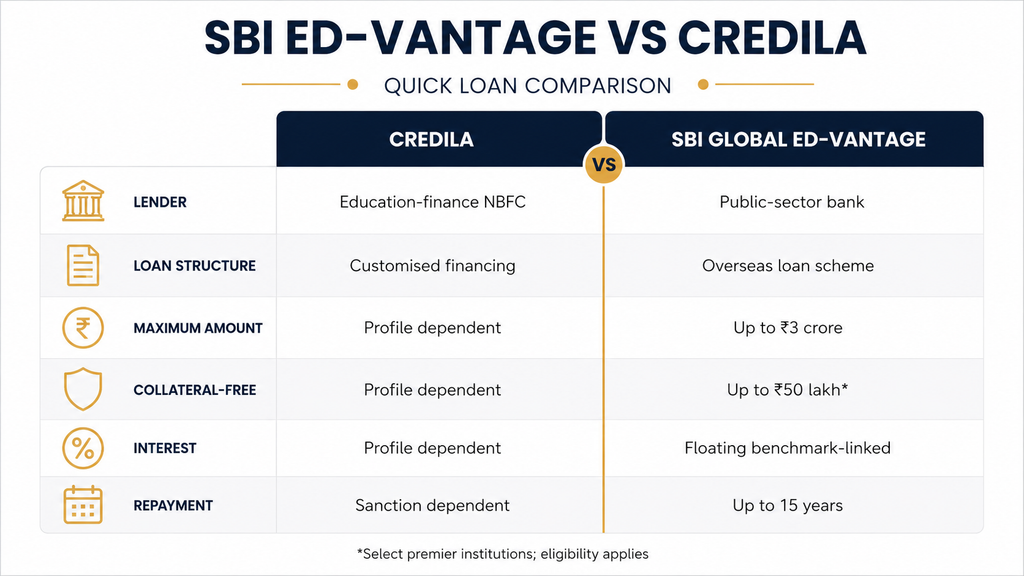
SBI Global Ed-Vantage vs HDFC Credila: What is the difference between them?
Lending structure is the basic disparity between SBI Global Ed-Vantage and HDFC credit cards.
SBI Global Ed-Vantage
SBI defines Global Ed-Vantage as a foreign university and college education loan for full-time regular courses.
Eligible studies include:
- Graduate and post-graduate degrees.
- Courses in diplomas and certificate programs.
- Doctorate programmes.
In the scheme, SBI currently offers this loan scheme up to 3 crore.
Credila
Credila Financial Services Limited is an NBFC which specialises in education funding. Previously, it was called HDFC Credila Financial Services Limited.
Its loans are tailored based on factors like:
- Learner and academic description.
- University and course.
- Destination.
- Funding requirement.
- Co-applicant.
- Unsafe and credit evaluation.
This difference is essential when reading an SBI Ed-Vantage review since Credila is not always going to evaluate a loan in terms of the scheme structure applied by SBI.
Read out: Education Loan Interest Rates 2026: Bank vs NBFC Explained
SBI Global Ed-Vantage Brown vs HDFC Credila Interest Rates.
Interest is at the centre of SBI Global Ed-Vantage vs HDFC Credila; however, making comparisons with one of the headline percentages can mislead.
SBI publishes the price of its education loans on its pro-official interest-rate fantasy. Global Ed-Vantage adopts floating prices that are benchmarked.
Applicable pricing used by Credila is solely dependent on its product, the borrower profile and underwriting examination.
To have a useful SBI vs Credila interest rate analysis, request:
- Last year of interest rate.
- Permanent or floating building.
- Benchmark and spread.
- Reset conditions.
- Applicable concessions.
- Moratorium interest treatment.
The rate advertised is not a sure way to have a lower total cost.
As an illustration, total repayment can vary with a variation in processing charges, interest or repayment tenure moratoria, even though it appears to have similar starting rates.
Interest Rate Check: Compare SBI vs Credila, the interest rate on your profile on the same date. Old online comparison tables should not be your ultimate source of decision.
Check out: Study Abroad Budget Guide 2026: Total Costs, Scholarships & Loan Guide
SBI Global Ed-Vantage vs HDFC Credila: Amount Lent and Family contribution.
In SBI Global Ed-Vantage vs HDFC Credila, another key determinant is the size of the loan.
SBI currently states:
- Loans can be available up to ₹3 crore.
- Some of the leading institutions could be offered collateral-free financing up to 50 lakh.
These are scheme limits, not mandated amounts of sanctions.
Credila is based on a tailored evaluation. It also promotes up to 100 per cent funding, which is on its official site, as terms and eligibility are subject to terms and conditions.
Divide to determine what you actually need.
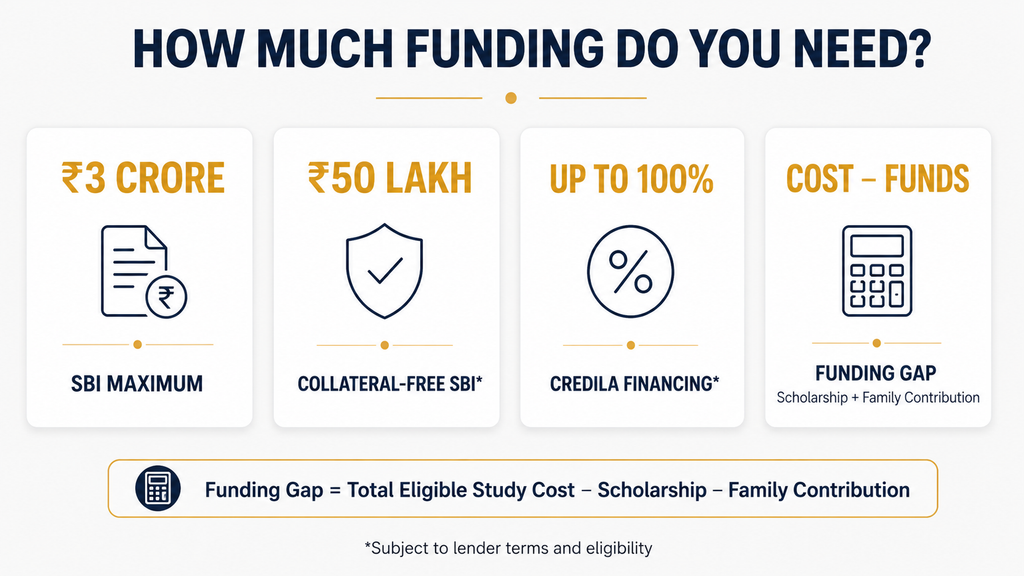
Use:
Total eligible study cost – confirmed scholarship – family contribution = funding gap
Education expenses permissible comprise approved tuition and accommodations, books, equipment, travel and other educational expenses.
Margin requirements should also be considered as part of an SBI Ed-Vantage review. This scheme of SBI offers an option of margin to the borrower, where scholarship or assistantship can be taken into consideration under the required circumstances on the margin.
Parent Tip: Do not select a lender because it allows more to be sanctioned. Borrow according to your genuine funding requirement.
SBI Global Ed-Vantage vs HDFC Credila: Collateral
Collateral will have a palpable influence on SBI Global Ed-Vantage vs HDFC Credila.
SBI now indicates a potential offering of collateral-free Global Ed-Vantage loans up to ₹50 lakh to students who have been admitted to select top institutions. Security requirements are used beyond pertinent collateral-free types.
The security needs of Credila are not fixed; they are based on their loan structure and the profile of the applicant.
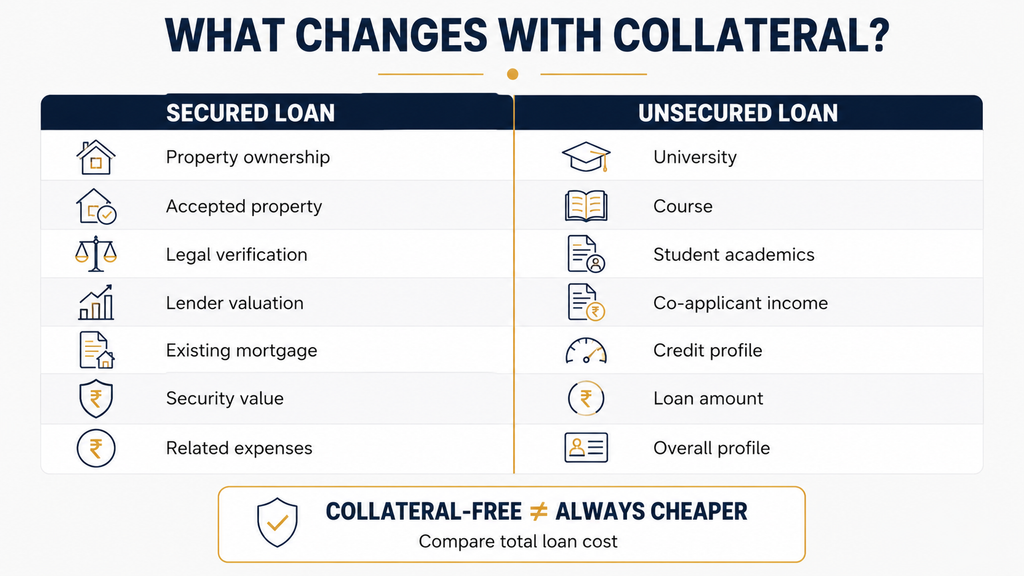
In case of secured loans, compare:
- Property ownership
- Accepted property
- Legal verification
- Lender valuation
- Existing mortgage
- Related expenses
- Security value
In unsecured financing, the lenders might put a greater emphasis on the university, course and student academics, co-applicant’s income, credit profile and loan amount required.
What this translates to you: This does not necessarily mean that collateral-free will be cheaper. Compare the rate and payment of the entire amount.
SBI Global Ed-Vantage vs HDFC Credila: Fees and Other Costs
The influence of Processing on SBI Global Ed-Vantage vs HDFC Credila may relate to large loans.
SBI now has a processing fee of 10,000 rupees as per the application in Global Ed-Vantage.
Credila adheres to its relevant policies of origination and charges. The precise amount to apply in relation to your loan must be stipulated in your lender papers.
Check for:
- GST on levies charged
- Processing/origination fee
- Legal and appraisal costs
- Insurance-related costs
- Mortgage-related expenses
- Late-payment or penalty fees
Reading sanction documents and any applicable disclosures to the borrowers should be included in the HDFC Credila loan process.
Loan Tip: Compare the fees not only in portions but also in rupees as well.
SBI Global Ed-Vantage vs HDFC Credila: Moratorium and Repayment
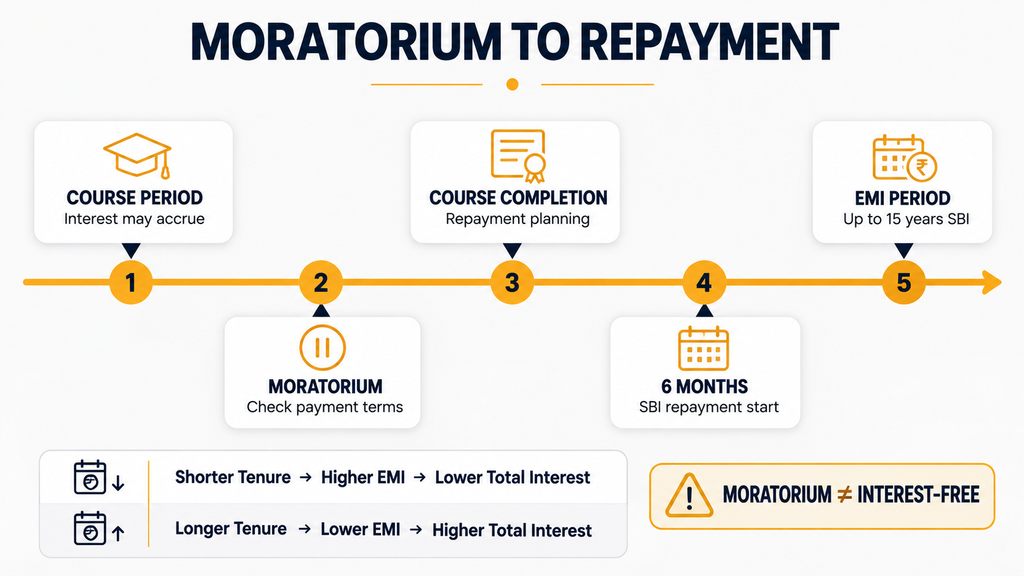
Moratorium may have a huge influence on the ultimate price of SBI Global Ed-Vantage HDFC Credila.
According to SBI, simple interest is paid during the term of the course and moratorium. Repayment begins six months after taking the courses. Principal can be added with accrued interest prior to the payment of EMI.
As such, moratorium is not free of interest.
Credila’s conditions of the study period and repayment of loans will determine the approved loan agreement. Borrowers ought to ensure that there is complete or partial interest servicing.
Ask both lenders:
- What is to be paid when studying?
- What will be the interest accrued?
- What will be the start of EMI?
- What will be the resultant balance?
SBI is presently making it possible to repay up to 15 years via Global Ed-Vantage. The tenure of the Credila will be based on the terms and conditions of products and sanctions.
| Option of Repayment | Interest deduction. | EMI |
| Shorter tenure | Tend to be lower. | Tend to be higher |
| Long tenure | Usually higher | Usually lower |
| Premature repayment | Can lead to lower interest in the future. | Lessens debt later. |
An excellent SBI Ed-Vantage review would thus consider the overall repayment term as opposed to EMI.
Check out: Education Loan Moratorium Period & EMI
SBI Global Ed-Vantage vs HDFC Credila: Process of application.
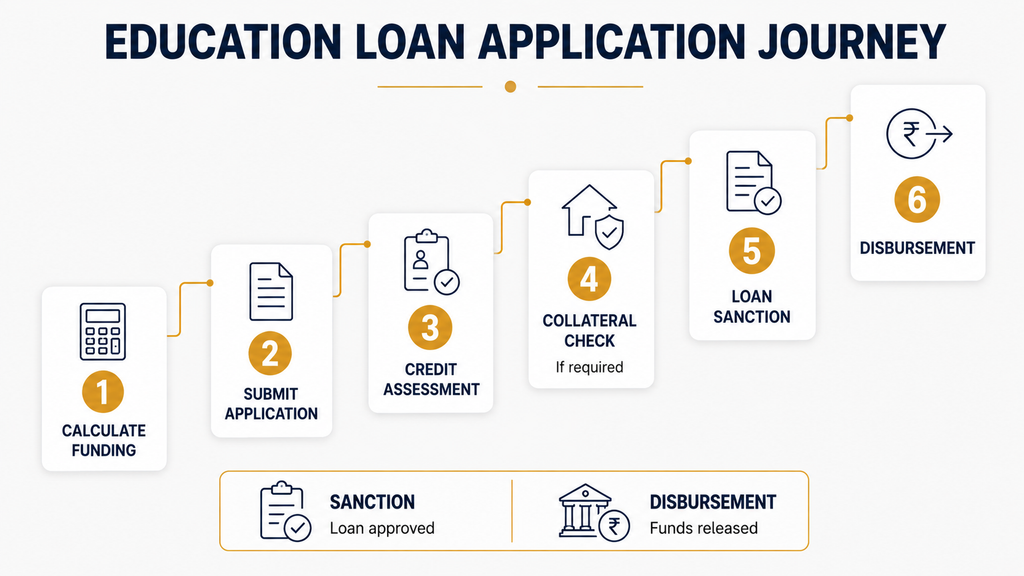
The SBI Global Ed-Vantage vs HDFC Credila application process adheres to slightly different lending processes, albeit with different documentation and underwriting.
Typical stages are:
- Calculate funding requirement.
- Turn in application and documents.
- Complete credit assessment.
- Complete collateral checks, if required.
- Accept penalty upon being approved.
- Meet sanction conditions.
- Complete disbursement requirements.
- Funds are released.
The HDFC Credila loan procedure is based on the credit appraisal and the documentation requirements by Credila. SBI applications should meet the requirements of the Global Ed-Vantage scheme.
Sanction is an authorisation by the lender of the loan, but on terms.
Disbursement refers to the authorised money being indeed handed out.
These terms are not to be used interchangeably.
SBI Global Ed-Vantage vs HDFC Credila: Which Saves More?
No one wins in SBI Global Ed-Vantage vs HDFC Credila.
SBI would be appealing when:
- Your profile is suitable for Global Ed-Vantage.
- Your school is eligible for preferential treatment.
- You will be able to satisfy security requirements.
- SBI also provides a competitive final rate.
- Minimum required family contribution is bearable.
Credila can be enticing when:
- You need individualised financing.
- Your profile is eligible for appropriate secured or unsecured funds.
- Prepayment in the family is a noteworthy issue.
- Credila offers financial terms which are competitive.
- The interest rate of SBI vs Credila is thus not the only aspect of the solution.
Use this formula
Family contribution + charges + moratorium interest + principal + interest paid during repayment period + other charges = total financial commitment.
That would be a better gauge of which lender really saves you money.
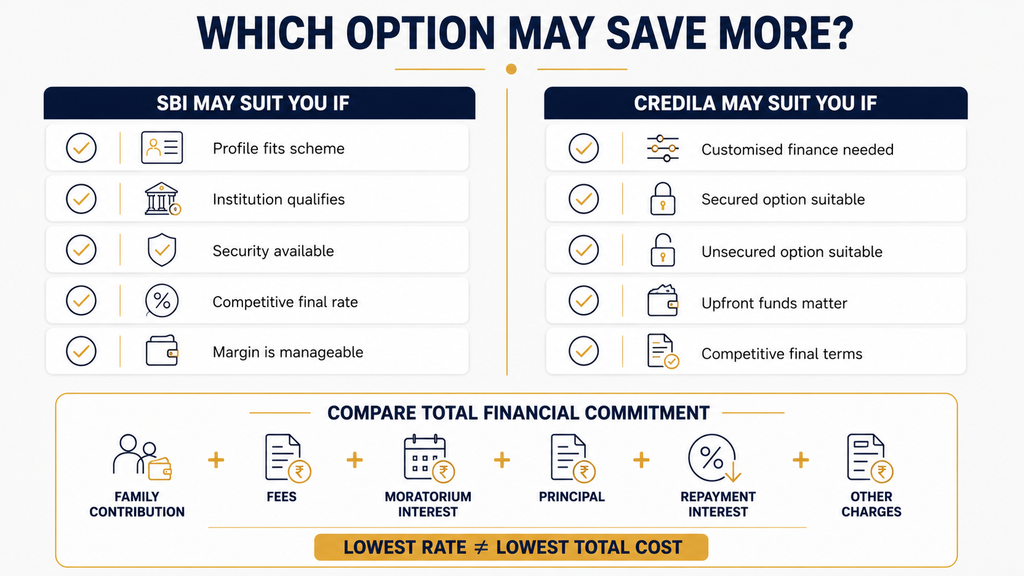
Table of final decision: SBI Global Ed-Vantage vs HDFC Credila.
Compare the written offers before choosing SBI Global Ed-Vantage vs HDFC Credila.
| Factor | Credila | SBI |
| Final rate | Check | Check |
| Sanctioned amount | Check | Check |
| Family contribution | Calculate | Calculate |
| Fees | Calculate | Calculate |
| Collateral | Check | Check |
| Moratorium cost | Calculate | Calculate |
| Tenure | Check | Check |
| EMI-start balance | Calculate | Calculate |
| Total repayment | Calculate | Calculate |
| Prepayment terms | Check | Check |
This has implications for you: The lowest starting rate may not necessarily be the lowest cost lender.
Common Mistakes When Comparing SBI Global Ed-Vantage vs HDFC Credila
Avoid these mistakes:
- Choosing between SBI Global Ed-Vantage vs HDFC Credila based on the advertised interest rates alone cannot exhibit the complete cost of borrowing.
- Using an outdated SBI vs Credila interest rate can lead to an inaccurate loan comparison.
- Failure to comply with margin regulations can leave families unprepared to make their contribution.
- Ignoring mortgage interest may amplify the balance of the loan being taken.
- Overlooking processing costs and other expenses may escalate the total cost of borrowing.
- The assumption that unsecured loans have never been better can lead to an expensive financing option.
- Taking more than the necessary can cause a cumulation of repayment.
- Mixing up loan sanction with disbursement may derail payment planning in universities.
Responsible Borrowing
Prior to making a decision on either SBI Global Ed-Vantage or HDFC Credila:
- Determine the overall cost of programmes.
- Deduct scholarships and family contribution.
- Set up an emergency reserve.
- Understand collateral risk.
- Calculate debt at the beginning of EMI.
- Consider currency fluctuations.
- Review repayment affordability.
- Look through the sanction documents.
Borrowing Rule: The amount sanctioned is excessive and should not be the primary consideration before borrowing an education loan. Assess the entire repayment commitment.
The help of Foreign Edu Loans.
Foreign Edu Loan will assist students in making a comparison of SBI Global Ed-Vantage and HDFC Credila and other eligible education loans based on their university, course, destination, requirement of funds, profile of collateral and co-applicant.
Foreign Edu Loans is an education-loan facilitation and guidance facility. The rate of interest to be charged and lending terms, as well as the final approval and the amount to be sanctioned, are determined by the respective lender.
Check Your Eligibility for an Education Loan.
Know what education loans can be appropriate to your educational plans and financial situation.
FAQs
Which is better: SBI Global Ed-Vantage vs HDFC Credila?
Neither of them is universal in terms of its superiority. Compare your real rate, security, family deposit, charges, moratorium and amortising repayment.
Which does Credila and SBI have the lower interest rate?
It is based on the terms of the applicant and the current lender. Compare the written offers which were issued approximately at the same date.
Is SBI Global Ed-Vantage collateral-free?
According to SBI, loans for some of the premier institutions up to ₹50 lakh can be without collateral, provided they are eligible.
Is Credila 100% financed?
Credila offers financing as high as 100% (where applicable) based on eligibility, underwriting and loan terms.
How is HDFC Credila loaned out?
The HDFC Credila loan process has the following steps that normally include application, documentation, credit appraisal, sanctioning, fulfilling conditions and disbursement.
Conclusion
This is because the winner in SBI Global Ed-Vantage vs HDFC Credila is dependent on the offer of your loan and not a rate that has been advertised. SBI offers an organised foreign education-loan program, whereas Credila has a tailored education-financing system.
Compare the funding requirements of both lenders. Verify the last applicable rate, family contribution, collateral, charges, moratorium interest, and EMI-start balance, term of repayment and the estimated total repayment.
An appropriate decision between SBI Global Ed-Vantage and HDFC Credila must determine the loan that fulfils your real funding need without burdening the overall loan repayment obligation.
Be sure to check your eligibility for Education Loans before completing your final decision.